Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY trades at 772.17, sitting squarely on the put wall at 772.00 with dealers in Negative Gamma and net GEX at -$3.99B - a knife's-edge setup where a tick below flip at 773.41 unlocks dealer selling. Call wall sits at 775.00 and the gamma flip is -0.0213684899 from spot, so the band 772.00-775.00 is today's trading cage until proven otherwise. Dealer vanna at -$103.42B and charm at -$4.7M both lean negative - a vol spike adds sell pressure and time decay nudges dealers to shed delta into the close. VIX at 15.99 with term structure in Steep Contango (Steep contango - vol sellers favored), VVIX at 89.49 rated Low, and SPY VRP at 0.74% says options are paid rich to realized. Zero-DTE share of GEX is 36.9%% so intraday whip is elevated into expiry. QQQ at 723.34 prints a deeper -$9.96B short-gamma pit than SPY - tech is the amplifier today. Bottom line: sell premium with defined wings - iron condor 30-45 DTE wrapping 772.00/775.00 is the trade; abandon short vol if SPY closes below 773.41 with VIX>18.
SPY at 772.17 is pinned directly on the put wall with dealers in Negative Gamma, meaning any slip below amplifies downside while a reclaim of the flip restores dealer support. VIX term structure stays in Steep Contango and VVIX at 89.49 keeps vol-of-vol tame, so premium sellers get paid - but QQQ's steeper short-gamma stack says tech leads the tape in either direction. The signal: harvest VRP via defined-risk condors in the 30-45 DTE window and let the charm pivot at 772 be the trip wire.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
772.17
773.41
-0.16%
775
772
765
-$3.99B
Short gamma
QQQ
723.34
731.64
-1.13%
730
720
725
-$9.96B
Short gamma
IWM
275.73
289.76
-4.84%
277
275
280
-$4.42B
-
VIX
15.96
16.05
-0.55%
20
15
19
-$108.65M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.34
9.60
+0.74
1.62
2.29
1.47
QQQ
18.13
16.03
+2.10
1.93
1.44
1.11
IWM
15.30
13.72
+1.58
0.84
2.14
0.79
VIX
72.44
69.27
+3.17
-99.53
0.32
0.38
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
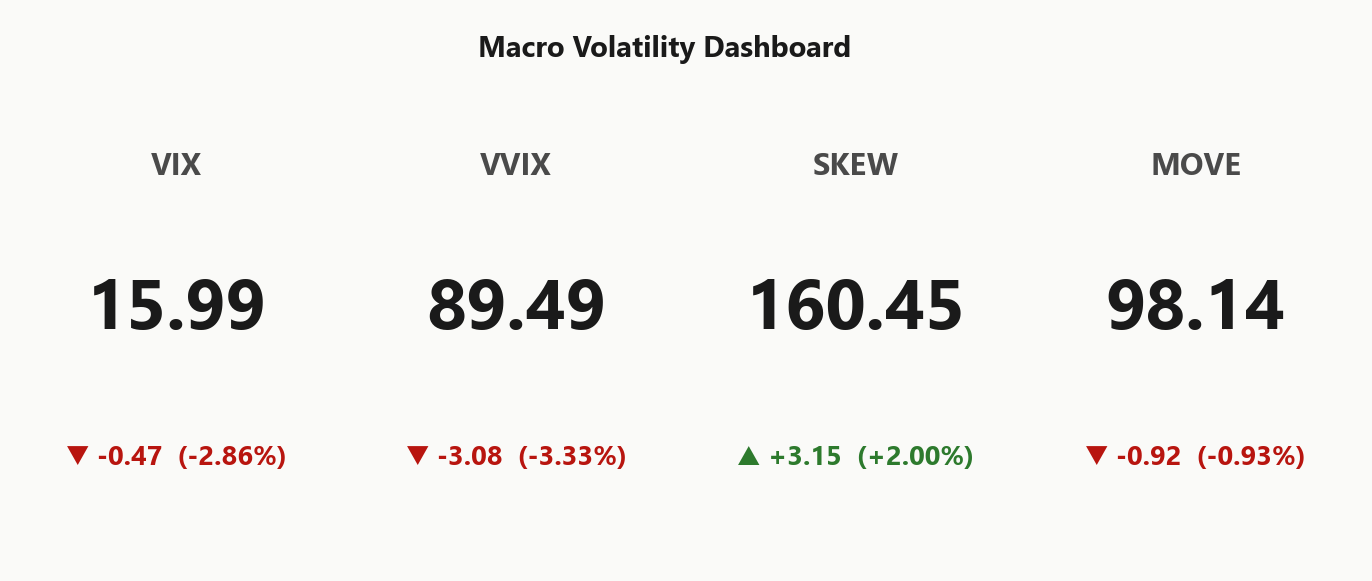
15.99
-2.86%
VVIX
89.49
-3.33%
SPX
7,748.43
+0.06%
SKEW index
160.45
+2.00%
MOVE (bond vol)
98.14
-0.93%
VIX term (9d/30d/3m/6m)
13.97 / 15.92 / 18.49 / 20.24
Steep contango
VVIX / VIX
5.60
Low
Regime
Elevated / Watchful
Regime Assessment
The tape is sitting in a Elevated state - Elevated / Watchful - with VIX at 15.99 and a measured half-life of 15 sessions. That's a sticky regime, not a transitional one: the modal path is more of the same, not a break.
Transition math backs the stance. Probability of a panic migration over the next five sessions prints 0.05 - negligible - while the ten-session drift to low-vol clocks 0.45, a materially higher but still coin-flip-shy chance. Signal color is Yellow for a reason: no shock priced, but no all-clear either.
Playbook: harvest the regime, don't fight it. Short premium carries edge while the elevated bucket holds, but size for persistence - the half-life says this doesn't resolve this week.
What it means for your trading
Elevated-but-watchful regime with sticky 15-session half-life; panic migration at 0.05 is a non-event while the 0.45 drift-to-calm bias favors measured premium selling over directional bets.
Trading readVIX cooling, VVIX cooling faster, SKEW firm, MOVE calm - rates aren't tense, equities are easing. Divergence to watch: SKEW stays elevated while VIX falls, meaning tail is still bid under the hood.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
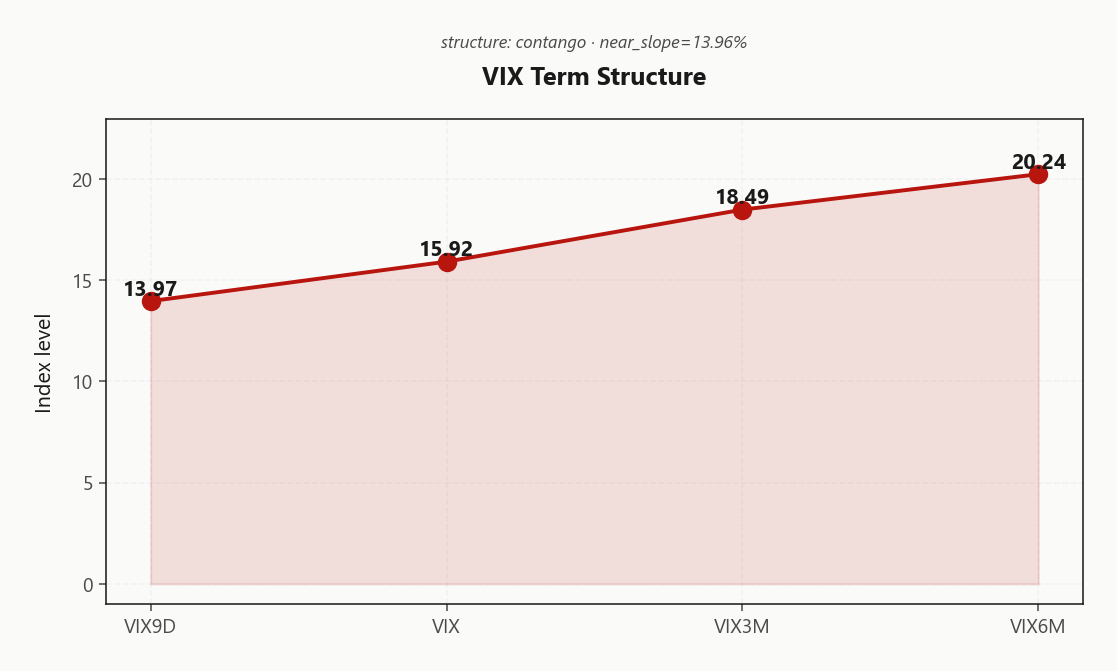
The VIX complex prints Contango front-to-back: VIX9D at 13.97 sits beneath spot VIX 15.92, with the 3M at 18.49 and 6M stacked at 20.24. Near slope of 13.96%% confirms the carry - the front end is suppressed while term premium builds further out the curve.
Derived regime reads Steep Contango - Steep contango - vol sellers favored. Forward 30-60 pricing comes in at 19.649349862 and 60-90 at 21.8502883276, so the mid-curve is pricing stable, not stressed. The geometry greenlights vol selling, with the sweet spot squarely in the belly: enough theta to compensate, past the near-dated gamma pit, and still inside the contango carry window.
Trade implication: 30-45 DTE is where the curve pays you - shorter dates get chopped by the gamma pit, longer dates give back the carry edge.
What it means for your trading
Steep Contango with near slope 13.96%% and forward 30-60 at 19.649349862 greenlights premium selling in the 30-45 DTE belly. Kill the carry trade only if the front end inverts or VIX9D crosses back above spot VIX.
Trading readSteep contango front-to-back - vol sellers get paid the carry, and the market isn't pricing an imminent event. Term structure says 'no shock on the radar' while skew says 'still hedge the tail.'Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 10.34% prints above 20-day realized of 9.6, keeping the volatility risk premium live at 0.74%. HV60 at 10.98 sits a touch above HV20, so recent tape is decelerating into a still-paid implied - the carry window is open for sellers who respect dealer short gamma below spot.
QQQ is where the premium stacks richest: VRP of 2.1% dwarfs the index and prices tech options overpaid to realized. IWM carries its own cushion at 1.58%, a wider spread than SPY - small-cap vol is bid above what the tape has actually delivered.
Signal is vrp_active: harvest the premium through defined-wing structures at 30-45 DTE, with QQQ carrying the fattest per-unit edge. Naked short vol stays off the table while dealers remain in Negative Gamma.
What it means for your trading
Implieds are paid rich to realized across the complex - SPY VRP at 0.74%, QQQ the richest at 2.1%, IWM wider than SPY at 1.58%. Sell premium with wings, let the carry work, and keep tech as the preferred vehicle.
Skew Convexity
SPY's quarter-delta skew prints 1.62% with put IV at 8.94% against call IV at 7.32% - downside is paid, but the bid is ordered, not panicked. The smile ratio at 1.22% confirms no tail-chase steepening; this is positioned hedging, not fresh fear.
The upside tells its own story: call IV sits well below ATM at 8.26%, meaning conviction in a melt-up is absent. Dealers aren't paying for calls - they're paying for puts, and the geometry rewards spread protection over naked downside wings. Buying puts outright overpays the ordered skew; put spreads harvest the richness without funding the whole smile.
Contrast with VIX: call 25d IV at 124.67% dwarfs the VIX put side - the vol-of-vol tail is still bid aggressively. Translation: the market is calm in equities but hedged for a spike. Keep a cheap OTM VIX call wing on; the convexity is cheaper than the equity-side tail suggests.
What it means for your trading
Ordered skew with a 1.22% smile ratio favors put spreads over naked puts for downside protection, while the extreme VIX call bid at 124.67% keeps vol-spike convexity worth owning.
Vol-of-Vol Structure
VVIX at 89.49 against spot VIX of 15.99 prints a ratio of 5.60 - vol-of-vol rated Low. The surface is unimodal; jump-risk pricing has drained relative to historical panic prints, and the signal color reads Green. Translation: the market is paying realistic premium for a vol spike, not reaching for convexity.
VVIX moved -3.33%% on the session, extending the compression - a tell that dealers aren't bidding up vega-of-vega into a known event. With no bimodal pricing in the surface, sizing guidance is Standard Size; there's no haircut to apply for a jump regime that isn't being priced.
The read: short premium carries cleanly here. Low vol-of-vol plus active VRP means iron condors in the 30-45 DTE window get paid without the gamma-up-in-vol trap. Hedge the tail with cheap VIX convexity rather than fattening the body.
What it means for your trading
VVIX/VIX ratio at 5.60 keeps vol-of-vol in the Low regime with signal Green - size standard and sell the wings, no bimodal pricing in the surface to force a discount.
Dispersion Spread
The vol surface is screaming dispersion, not direction. QQQ ATM IV at 18.13% prints nearly twice SPY's 10.34%, with IWM wedged between at 15.3% - single-name and sector vol are carrying premium the index refuses to pay.
That gap is the tell: correlation is low, idiosyncratic risk is high. Index hedges will leak against a tech-led tape or a small-cap air-pocket because the beta won't translate cleanly. The derived read confirms it - section signal rates Moderate, enough to matter, not enough to size up on a dispersion book.
Trade implication: harvest the richer premium at the index level - SPY/SPX short vol wins the risk-adjusted lane over single-name premium, which is where the realized tail actually prints. Let QQQ's fat IV be the warning light on your single-stock book, not the invitation to sell it.
What it means for your trading
Dispersion is Moderate with QQQ IV at 18.13% running near 2x SPY's 10.34% - sell index vol, respect single-name tails.
Liquidity & Microstructure
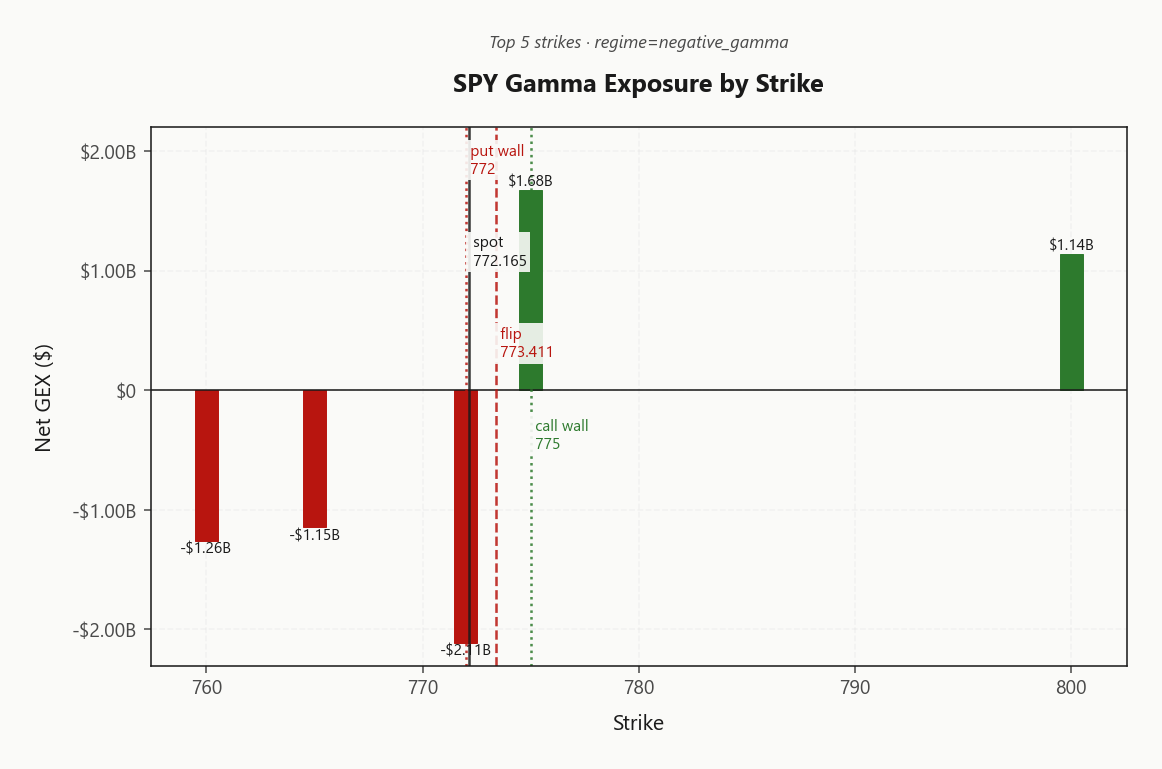
The 500 strike remains the book's historical ballast - legacy LEAPS positioning that anchors long-dated OI but does not drive today's tape. The live action sits far higher, in the gamma pit at 772.00 where dealers carry -$2.11B of concentrated short gamma - the single densest hedging node in the chain.
Spot at 772.17 is pinned directly on the put wall at 772.00, with the dealer sell-flip at 773.41 sitting just overhead. The band 772.00-775.00 is today's cage: a reclaim of the flip restores dealer support and compresses range toward the call wall, while any slip through the put wall unlocks amplified selling as dealers chase delta lower.
This is a knife-edge microstructure - the pit, the flip, and spot are stacked within a hair of one another. Trade the band; do not chase the breakout until spot leaves it cleanly.
What it means for your trading
Spot pinned on the put wall at 772.00 with the flip at 773.41 overhead - the 772.00-775.00 cage holds until proven otherwise, with the gamma pit at 772.00 as the acceleration node on either side.
Trading readDealer short-gamma clusters directly on the put wall at 772.00 - any slip through it amplifies selling, while a reclaim of 773.41 flips dealers back to buyers. Trade the band, don't chase the breakout.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer second-order Greeks lean the same direction as gamma: net VEX at -$103.42B prints negative, so any uptick in implied vol forces incremental dealer selling into the tape rather than absorbing it. Net CHEX at -$4.7M extends that pressure through the clock - time decay nudges dealers to shed delta into the close rather than mark it back.
The charm pivot sits at 772, flagged as a Put Wall level with spot sitting -0.0213684899 away - a knife-edge, bias reads Neutral. There is no cushion in the greek stack: vanna, charm, and gamma all reinforce the same sell-the-rally, amplify-the-dip mechanic.
Trade the pivot as the single trip wire. Hold the band while spot stays pinned; a close through 772 unlocks the vanna-charm feedback loop and short-vol structures have to come off.
What it means for your trading
Dealer vanna and charm both negative - vol-up and time-decay reinforce the short-gamma pin, and the charm pivot at 772 is the one level that flips the regime.
Cross-Asset Confirmation
MOVE at 98.14 keeps bond vol subdued - no credit-shock vibration bleeding into equity hedges - while Fear & Greed prints 31 (Fear), a contrarian setup brewing beneath a calm rates tape. This is an equity-centric caution regime, not a systemic one.
QQQ at 723.34 and IWM at 275.73 both ride the same short-gamma leg as SPY - cross-asset regime reads Aligned with tone Unknown. Divergence check False confirms no index split; mega-cap tech and small-caps are rowing with SPX, not against it.
The read: credit isn't flagging, sentiment is already defensive, and every index points the same direction. Fade the fear, respect the walls, size standard.
What it means for your trading
MOVE at 98.14 and aligned short-gamma across SPY/QQQ/IWM say this is an equity positioning story, not a credit event - Fear & Greed at 31 (Fear) is the contrarian tell to watch.
Scenario EV
The scorecard lands on Iron Condor at 38, clearing the put spread at 25 by a wide enough margin to make the structure choice obvious. VRP reads Unknown and VVIX regime Low - premium is paid, vol-of-vol is tame, and defined-risk wings earn the carry without demanding a volatility hedge.
Sweet spot is 30-45 DTE: far enough out to clear the gamma pit at 773.41, close enough in to monetize the Steep contango - vol sellers favored curve. Sell the wings outside 772.00 and 775.00 - the band dealers are already defending - and let charm pin from -$4.7M do the work.
Size Standard Size; the VVIX regime at 89.49 doesn't demand a haircut. Kill the trade on a close below 772.
What it means for your trading
Iron condor at 30-45 DTE wrapping 772.00/775.00 is the trade; standard sizing, trip wire at 772.
Trip wire: a close below the charm pivot at 772 kills the short-vol thesis. Below that line, dealers in Negative Gamma amplify downside and the carry stops paying - flatten wings, don't average.
Avoid naked short puts and 0DTE short gamma; zero-DTE share at 36.9% of total GEX guarantees chop into print. Hedge the tail cheaply: VIX calls remain bid in Steep contango - vol sellers favored, so a thin OTM convexity wing offsets the gap risk the condor can't absorb.
What it means for your trading
The edge is iron-condor carry inside the 772.00/775.00 cage at 30-45 DTE - standard size, VIX wing on, and 772 as the kill switch.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.96 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 773.41 against a spot of 772.17. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.34% with a volatility risk premium of 0.74%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.99. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime