Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 767.49 is sitting below the 772.25 gamma flip with net GEX at -$12.59B - dealers are short gamma and will chase moves. Call wall at 770.00 caps upside, put wall at 765.00 is the pivot; break it and dealer selling accelerates. Net DEX at $4.01B with negative vanna -$49.91B means a vol pop sells more delta - vanna is working against bulls. VIX at 17.25 is in steep contango vs VIX3M 18.88 and VIX6M 20.56, VVIX 95.37 is normal - vol-sellers' carry is intact but no complacency. VRP active with ATM IV at 11.61% vs HV20 9.85, so premium is paid above realized. QQQ runs a deeper negative-gamma profile with 51.3%% of GEX in 0DTE, IWM gamma-flip remains unverified. Bottom line: structure iron condors in 30-45 DTE around 765.00/770.00, size standard per Standard Size, and treat 765.00 as the risk-off tripwire.
Negative-gamma SPY/QQQ, VIX 17.25 contango, Iron Condor preferred
Index complex is pressing into short-gamma territory with SPY at 767.49 just below the 772.25 flip and QQQ printing a steeper negative-GEX regime. VIX term structure holds steep contango with VVIX normal, so forward vol carry remains the cleaner edge than directional tail hedges. Charm pivot sits at the 765.00 put wall - defend it and dealers stabilize, lose it and the amplification machine turns on.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
767.49
772.25
-0.62%
770
765
765
-$12.59B
Short gamma
QQQ
716.95
730.86
-1.90%
720
715
725
-$13.47B
Short gamma
IWM
271.86
286.91
-5.25%
275
270
280
-$6.88B
-
VIX
17.25
17.54
-1.63%
20
17
19
-$14.02M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.61
9.85
+1.76
2.23
2.29
1.31
QQQ
19.82
16.91
+2.91
2.90
1.44
0.97
IWM
16.39
14.11
+2.28
2.06
2.14
1.89
VIX
75.96
68.65
+7.31
-94.86
0.32
0.24
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
17.25
+4.80%
VVIX
95.37
+3.02%
SPX
7,700.78
-0.56%
SKEW index
160.45
+2.00%
MOVE (bond vol)
98.14
-0.93%
VIX term (9d/30d/3m/6m)
14.87 / 17.11 / 18.88 / 20.56
Steep contango
VVIX / VIX
5.53
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in an Elevated / Watchful regime with VIX at 17.25 — firm enough to respect, not hot enough to chase. The transition matrix prints a panic probability of only 0.05 over five sessions, so the right tail is quiet; meanwhile the probability of resolving back to a low-vol state within ten sessions runs 0.45, a coin-flip that argues against aggressive long-vol carry.
Half-life clocks 15 sessions — sticky, but not entrenched. That is the window to work: long enough that short-premium carry compounds, short enough that complacency has no shelf life. Cross-asset confirmation is Aligned with SPY and QQQ both below their flips, so the elevated label is a positioning read, not a macro shock.
Trade the regime, don't fight it. VRP is active, VVIX is Normal, and the term structure sits in Contango; that stack favors Iron Condor structures over directional convexity. Watchful means sized, not sidelined.
What it means for your trading
Elevated / Watchful with VIX at 17.25 and a 15-session half-life — carry the regime via Iron Condor, standard size, and let the panic-probability floor do the heavy lifting.
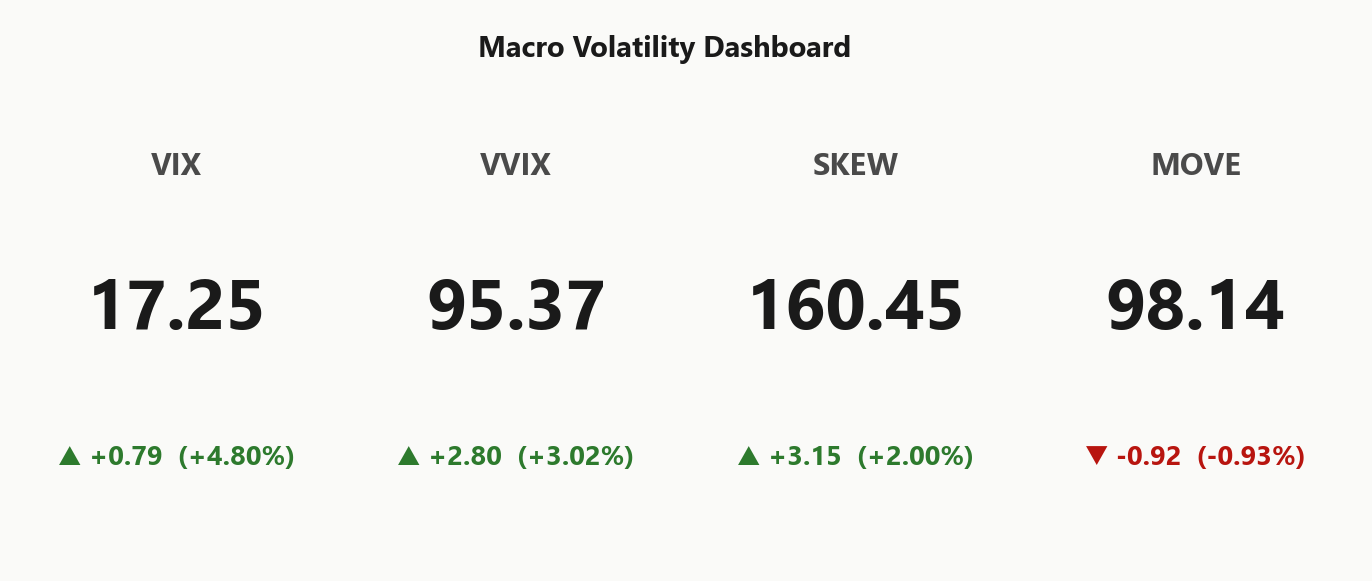
Trading readVIX firming, VVIX firming, SKEW up, MOVE softening - equity-vol complex is heating in isolation; this is a positioning story, not a macro shock.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
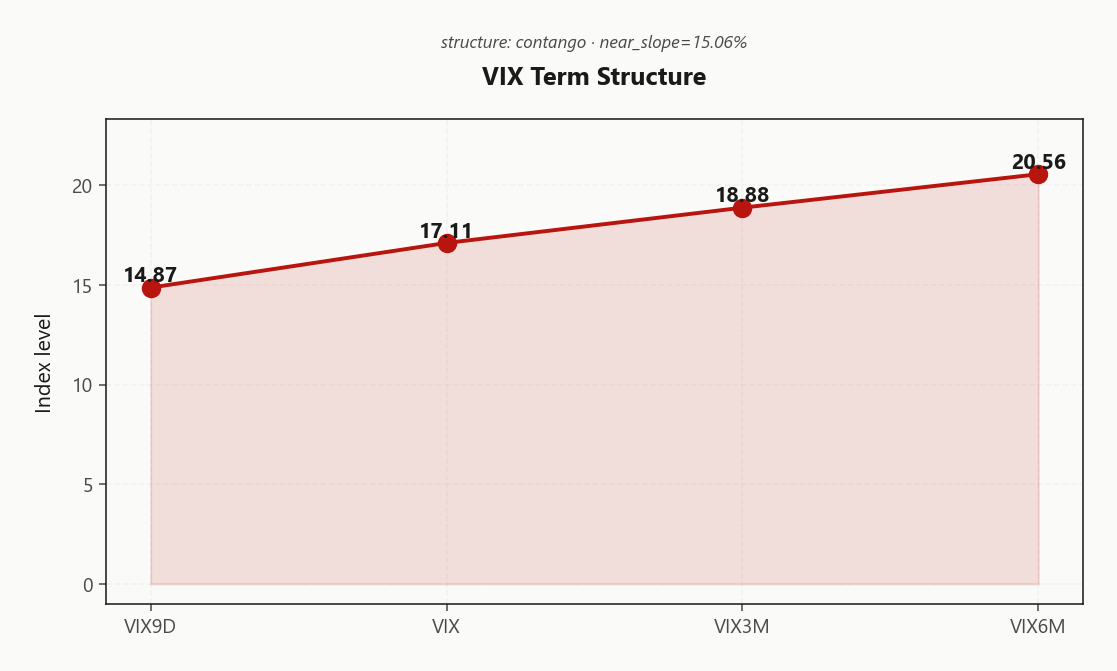
The curve is in Steep Contango with VIX9D at 14.87 sitting well under spot VIX at 17.11 - the market is pricing the immediate tape as calm even while spot presses the gamma flip. That gap is the carry edge: front-week premium is being handed out cheaply relative to the belly, and the belly is where the structural bid sits.
Pulling further out, VIX3M 18.88 over VIX6M 20.56 keeps the slope rewarding calendar carry, and the front-month futures basis of 10.55%% says the roll yield is intact. Structure label reads Steep contango - vol sellers favored - vol sellers favored, but not blindly: the near slope is where the first crack would show.
Trade the shape, not the headline. Favor 30-45 DTE short-vol over front-week, where theta decays into the belly's richness without catching the full gamma whip of a VIX9D spike. If VIX9D crosses VIX, the carry edge inverts and the trade flips to defense.
What it means for your trading
Steep contango from 14.87 through 20.56 with intact roll yield rewards calendar carry, but position in the 30-45 DTE belly - the near slope is the tripwire.
Trading readSteep contango carry remains the base trade but the near slope is lifting - the moment VIX9D crosses VIX, flip to defense.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Options are pricing more than the tape is delivering. SPY ATM IV at 11.61% stands above HV20 9.85, with VRP running 1.76% - a live premium that hasn't been eroded by realized follow-through. HV60 at 10.72 stays below implied as well, so the cushion is structural rather than a one-session artefact.
QQQ carries the richer bid: ATM IV 19.82% against HV20 16.91 leaves VRP at 2.91%, the widest of the complex and consistent with AI-chain headline risk being paid for through index premium rather than single-name wings. IWM is the thin spot - VRP at 2.28% leaves the slimmest buffer for a realization pop.
Tape stays contained while the quote-side firms: short-premium carry remains defensible, but size by product. Index vehicles - SPY first, then QQQ - are where the paid premium is cleanest; IWM's thinner cushion argues for smaller clips or a spread rather than a naked short.
What it means for your trading
Realized is lagging implied across the complex - VRP at 1.76% on SPY and the wider 2.91% on QQQ pay short-premium structures while tape stays contained. IWM's VRP of 2.28% is the thinnest buffer and should be sized accordingly.
Skew Convexity
The 25-delta put skew prints 2.23% with a smile ratio of 1.28% - downside is bid in an ordered fashion, not the panic-style wing lift that precedes forced hedging. Put 25d IV at 10.34% sits a measured step above ATM at 8.79%; the premium for downside protection is being paid, but methodically.
The call wing tells the other half of the story: 25-delta call IV at 8.11% is below ATM - upside hedging is absent and no one is reaching for convexity to the top side. That asymmetry is consistent with the short-gamma complex sitting below the 772.25 flip: rallies cap into 770.00, downside gets methodically hedged, no one chases.
SKEW index at 160.45, up 2%, confirms the tail bid is firming quietly without screaming. Trade implication: put spreads over naked puts - the ordered curve means the long leg prices fairly against the short, and you avoid overpaying for a wing that isn't being lifted aggressively. Reserve naked downside for a VVIX break or a SKEW surge; neither is here yet.
What it means for your trading
Skew is ordered-bid on puts with flat calls - a measured hedging regime, not panic. Favor put spreads over naked puts; the curve rewards structure over directional conviction while SKEW firms quietly at 160.45.
Vol-of-Vol Structure
VVIX prints 95.37 against VIX 17.25, pinning the ratio at 5.53 - squarely in Normal territory. The vol-of-vol complex is firming on the day with VVIX changing 3.02%, but the move is contained and nowhere near the bimodal jump-premium regime that forces defensive sizing.
No crush-or-spike tail is being priced into options-on-VIX, which is the quiet green light under an otherwise watchful tape. That absence is doing real work: it tells you the market isn't paying up for a gamma-squeeze convexity move in VIX itself, and the Steep contango - vol sellers favored term structure can be harvested without a second-derivative hedge stapled on top.
Translation to execution: run Standard Size on short-premium structures - the vol-of-vol tape is not asking you to shrink. Short premium is defensible here; the risk management lives at the charm pivot 765 and the VIX9D print 14.87, not in the sizing dial.
What it means for your trading
VVIX at 95.37 and VVIX/VIX at 5.53 keep the regime Normal, so size short-premium trades at Standard Size. No bimodal jump premium being paid means the carry edge from contango is the clean trade - defend it at the charm pivot, not at the sizing level.
Dispersion Spread
Index-level vol is running contained while single-name correlation sits moderate - SPY ATM IV at 11.61% prints well under QQQ at 19.82%, a tech-premium spread wide enough to flag that idiosyncratic AI-chain risk is being paid at the component level, not absorbed by the index wrapper.
IWM at 16.39% threads between the two, confirming small-cap dispersion is muted and the richness sits specifically in the mega-cap tech complex. With META earnings next week and NVDA/AMZN rotating through the top GEX moves, the component vol bid is doing work the index hedge dollar cannot - SPY premium bought as portfolio insurance will underpay against a single-name AI print.
The trade geometry is clean: harvest index vol where correlation smooths the surface, leave single-name premium to the earnings-cycle sellers who can defend the gamma. Prefer SPY/SPX vol-selling over single-name for the next cycle - iron condor at 30-45 DTE sits inside the carry window, and the dispersion gap says the index wrapper is the cheaper short.
What it means for your trading
Tech-premium spread between SPY 11.61% and QQQ 19.82% flags where the idiosyncratic risk is really priced; sell index vol, let the single-name sellers own the earnings gamma.
Liquidity & Microstructure
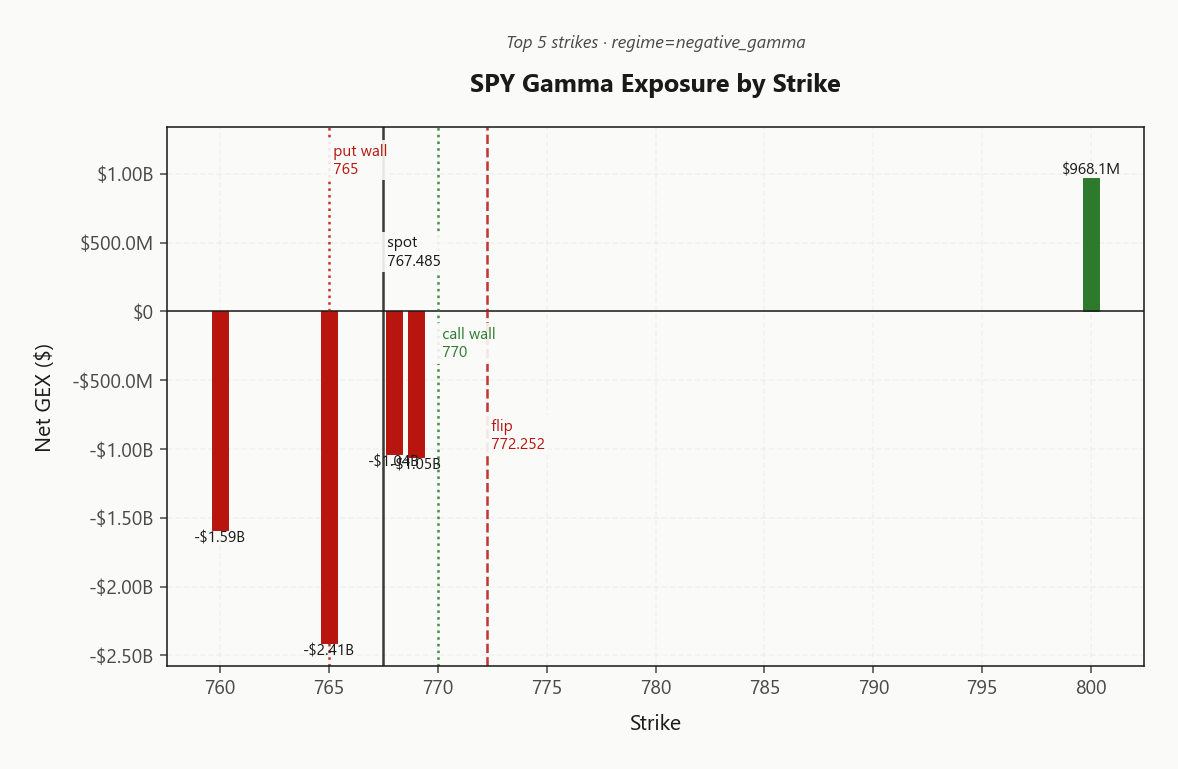
Open-interest anchor sits at 500 - well beneath spot - while the gamma flip at 772.25 hovers directly overhead. Spot is pinned inside the amplification zone with the 770.00 call wall capping any lift and the 765.00 put wall standing as the tripwire. The top strike at 765.00 carries net GEX of -$2.41B, a heavy put-side anchor that defines the floor's magnetism.
Mechanics are binary at the flip: above 772.25, dealers damp moves; below, they amplify them. With 46.2% of total GEX concentrated in 0DTE, intraday regime leans trend over chop - opening-range breaks tend to extend rather than fade, and dealer hedging stacks on itself through the session.
IWM's gamma-flip read is flagged insufficient_local_coverage, so the small-cap level is indicative only - don't size off it. Trade the SPY structure: respect the 770.00 ceiling, defend the 765.00 floor, and treat a decisive break of the put wall as the regime-change trigger.
What it means for your trading
Spot sits in the amplification zone between 765.00 and the 772.25 flip - the put wall is the pivot, and 0DTE-heavy gamma biases intraday toward trend over mean-reversion.
Trading readDense negative-gamma stack from 765.00 up through the flip means dealers amplify every push lower; the 770.00 ceiling pins rallies even as the floor stays fragile.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
The charm pivot at 765 - a Put Wall sitting -0.3237848297 from spot - is THE level of the session. Above it, charm bleeds dealer shorts into pins and the tape stabilizes into the close. Lose it and vanna takes over: any VIX uptick trips a mechanical delta-sell, which realizes vol, which trips more selling.
Current bias reads Neutral - a knife-edge, not a trend. Defend the pivot and the iron condor edge compounds through theta and charm decay; break it and the structure flips from carry to tail. Trade accordingly.
What it means for your trading
Vanna is working against bulls at -$49.91B while charm offers conditional support only above 765; bias is Neutral and the pivot is the only line that matters into the close.
Cross-Asset Confirmation
Cross-asset tape reads Unknown with regime divergence Aligned - QQQ at 716.95 and IWM at 271.86 both sit under their respective flips, confirming the SPY short-gamma lineage rather than fragmenting it. This is not a scattered tape; it is a coordinated press into negative-gamma territory across the index complex.
MOVE at 98.14 is down-0.93% - rates vol is easing as equity vol firms. That split matters: no credit or rates stress is piling into the equity drawdown, which fingerprints this as an isolated equity/AI-chain positioning event rather than a macro shock radiating from the funding side.
Fear & Greed prints 25 (Fear) - sentiment capitulation is underway while the macro plumbing stays quiet. Trade the regime as aligned-fragile: short-vol structures remain defensible with MOVE as the tripwire. A MOVE lift alongside VIX is the signal that this stops being contained and starts being systemic.
What it means for your trading
Index complex aligned below flips with MOVE softening confirms an isolated equity-vol event, not a cross-asset shock - Fear & Greed at 25 (Fear) marks sentiment capitulation. Watch MOVE as the regime-change tripwire; a joint MOVE/VIX lift turns this systemic.
Scenario EV
The scenario engine ranks Iron Condor top of the book at a score of 44, with the put spread trailing at 32 as the directional backup. The sweet spot sits in the 30-45 DTE window - far enough out to collect theta past the charm pivot at 765, close enough that contango carry still bites.
VRP reads Unknown on the structured tag, but the underlying math is cleaner than the label suggests: ATM IV at 11.61% stacks over HV20 9.85 and HV60 10.72, so premium is paid above realized across the horizon. Pair that with VVIX at 95.37 inside the Normal band and the term structure printing Steep Contango, and the carry regime stacks the deck for defined-risk short premium.
Wrap the body around the 765.00 / 770.00 walls, size Standard Size per the vol-of-vol band, and treat the charm pivot as the kill switch - lose it and the structure converts into a directional put spread.
What it means for your trading
Iron condor in 30-45 DTE around the 765.00/770.00 corridor is the edge - contango carry plus normal VVIX makes Standard Size defensible. Pivot the structure to a put spread if 765 breaks.
Actionable Summary
Preferred structure is Iron Condor in 30-45 DTE wrapping 765.00 and 770.00. VRP is active with ATM IV at 11.61% against HV20 9.85, VVIX at 95.37 keeps sizing at Standard Size, and contango carry across VIX9D 14.87 through VIX6M 20.56 stacks the deck for premium sellers.
Defend the charm pivot at 765 - lose it and short-gamma amplification turns on beneath the 772.25 flip, with net VEX -$49.91B adding a vanna accelerant on any vol pop. Avoid chasing short-dated vol under the flip and skip naked wings; VVIX normalcy says the tail isn't being bid, and ordered put skew 2.23% rewards spreads over outright hedges.
Watch MOVE at 98.14 for cross-asset confirmation - rates vol softening keeps this an isolated equity-vol event, aligned with Aligned SPY/QQQ regimes. A VIX9D push through VIX flips the carry edge; until then, Elevated / Watchful stays the operating label.
What it means for your trading
Sell the Iron Condor at 30-45 DTE, defend 765, and treat a VIX9D spike through 17.11 as the signal to flatten carry.
Warsh's 'very bumpy' AI road from a Fed Chair candidate is both a monetary-path and AI-cycle signal - relevant to both VIX futures slope and tech dispersion.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.25 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 772.25 against a spot of 767.49. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.61% with a volatility risk premium of 1.76%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.25. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime