Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
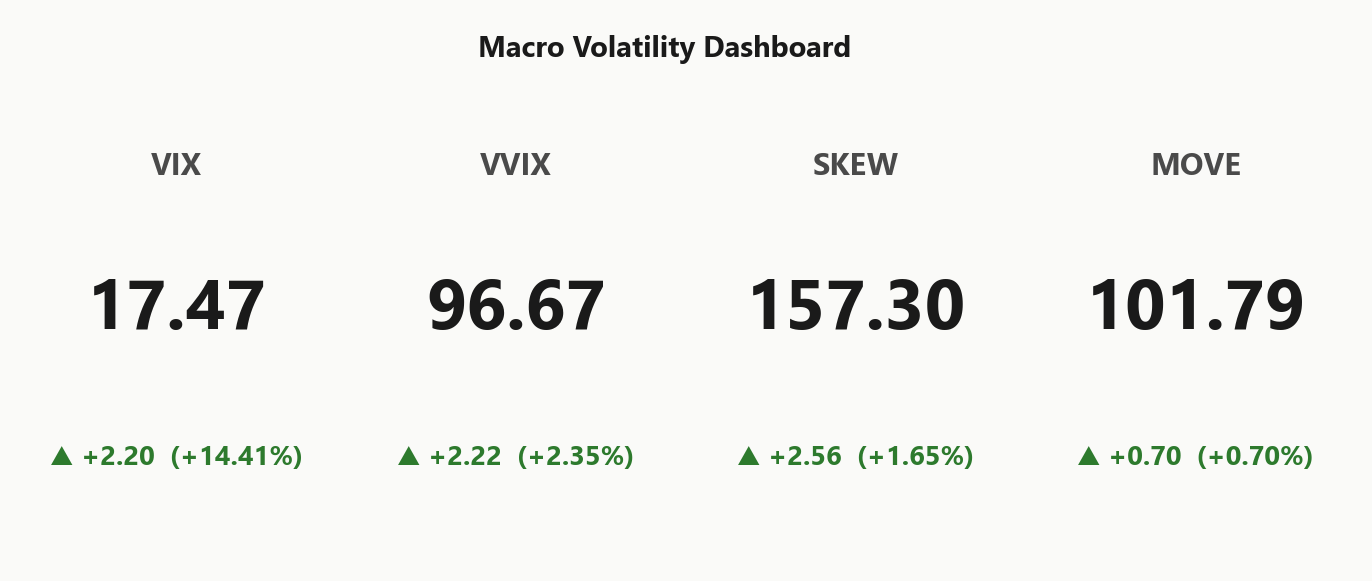
SPY at 766.83 enters the session in Negative Gamma territory with net GEX -$12.26B - dealers short gamma, so intraday swings get amplified not dampened. Gamma flip sits at 771.42 with spot below; call wall 770.00, put wall 765.00, max pain 766.00 - reclaiming the flip is the hinge trade for the tape. Dealers hold net DEX -$3.07B and net VEX -$35.14B, so a vol spike compounds downside selling pressure (Vol up = dealers sell delta - downside amplified if vol spikes). VIX printed 17.47 (+14.41%%) with term structure Contango and front slope 20.15%% - carry is available but front-month is being bid. VRP sits at 2.45% vol points over 20d realized, VVIX at 96.67 (Normal), Fear & Greed Fear at 25. Bottom line: derived structure Iron Condor in the 30-45 DTE window - fade the vol spike with defined risk, keep sizing Standard Size, and treat 771.42 as the flip switch for the day.
Index complex short gamma below flip; VIX at 17.47 spiking into contango carry window.
SPY opens below gamma flip at 766.83 with dealers net short gamma (-$12.26B) and VIX ripping to 17.47 on a tech-led flight to Treasuries. QQQ mirrors the regime while IWM's flip reads sensitive - the actionable edge is harvesting steep near-dated contango in the 30-45 DTE window via the derived iron condor read. Watch max pain at 766.00 as the first magnet before dealers would need to re-engage on a reclaim of 771.42.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
766.83
771.42
-0.60%
770
765
766
-$12.26B
Short gamma
QQQ
720.19
733.57
-1.82%
730
720
728
-$10.58B
Short gamma
IWM
271.69
282.73
-3.90%
280
270
280
-$6.40B
-
VIX
17.47
17.53
-0.33%
20
17
19
-$8.00M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.76
10.31
+2.45
2.05
2.27
1.34
QQQ
20.67
17.02
+3.65
3.00
1.46
1.04
IWM
18.35
12.77
+5.58
-0.26
2.20
1.06
VIX
76.50
70.28
+6.22
-79.81
0.32
0.29
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
17.47
+14.41%
VVIX
96.67
+2.35%
SPX
7,693.88
-0.32%
SKEW index
157.30
+1.65%
MOVE (bond vol)
101.79
+0.70%
VIX term (9d/30d/3m/6m)
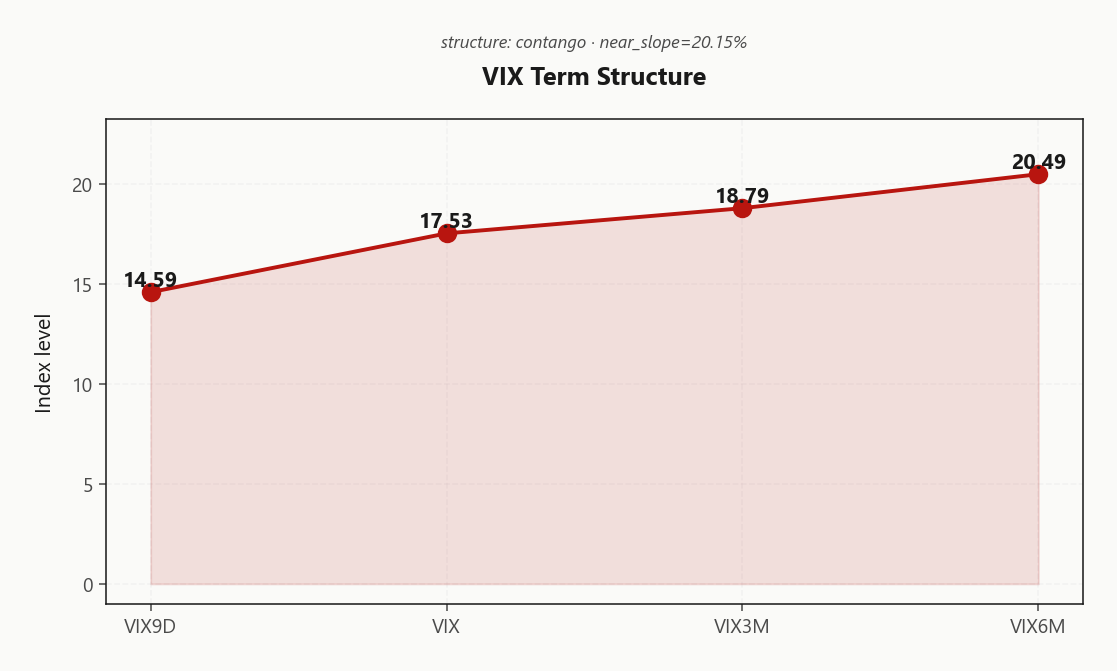
14.59 / 17.53 / 18.79 / 20.49
Contango
VVIX / VIX
5.53
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape prints Elevated - Elevated / Watchful - with VIX anchored at 17.47. This is not the capitulation regime: it's the watchful one, where dealers reprice risk without demanding a tail bid. The transition matrix is doing the heavy lifting here, not the headlines.
Panic probability over the next five sessions sits at 0.05 - a thin tail, not a fat one. The drop-to-low read over ten sessions is 0.45, which makes mean-reversion the base case, not trend-continuation of the vol spike. Half-life of 15 sessions says this regime decays on a measured clock, not a jump.
Trade the structure, not the narrative. Harvest the Iron Condor in the 30-45 DTE window at Standard Size; don't overcommit to the vol-spike story when the base rate says it fades.
What it means for your trading
Regime reads Elevated / Watchful with half-life 15 sessions and to-low probability 0.45 - base case is decay, not escalation, so fade the vol pop with defined risk.
Trading readVIX ripping while MOVE stays near 101.79 and VVIX only edging up to 96.67 = equity-isolated event, not a cross-asset meltdown - divergence favors mean reversion over regime shift.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Contango with 9D at 14.59 stacked under spot 17.53, 3M at 18.79, and 6M at 20.49. Front slope reads 20.15%%, which keeps the structural short-vol carry alive even as spot VIX lifts fast toward the front future. The derived label is Contango - structural carry available with signal Green - carry is on, but the easiest zone at the front is being compressed in real time.
Forward 30-to-60 clears at 19.3893192248 and 60-to-90 at 22.0593766911, flagging the belly as the richest roll-down bucket rather than the week. That geometry routes short-vol harvest into the 30-45 DTE window - long enough to escape the vanna-hostile front, short enough to still earn the contango bleed before the back curve flattens.
What it means for your trading
Term structure is in Contango but the front is being bid toward spot - fade the vol pop in the 30-45 DTE belly, not the front week.
Trading readNear slope 20.15%% in Contango says carry is available but the market is pricing stress into the front - fade the pop in the belly, don't chase short vol in the near week.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV at 12.76% prints over HV20 10.31 and HV60 10.97, leaving a VRP of 2.45% vol points - options stay rich to realized even with VIX ripping to 17.47. The structural read: short-vol premium is still accessible, and the trader question is whether today's tape confirms a realized breakout or decays back under the implied.
HV20 10.31 sitting under HV60 10.97 says realized hasn't ramped yet - the vol spike is being priced forward, not yet delivered. Carry remains active, but any session where HV5 accelerates through HV20 erodes the edge fast; the premium is a tape-dependent harvest, not a free carry.
Routing matters: IWM VRP at 5.58% prints materially over SPY's 2.45%, so single-index premium harvesting routes toward small-caps where the richness is cleaner and the index-level dealer vanna is less hostile.
What it means for your trading
Short-vol premium stays accessible with VRP at 2.45% vol points and realized still subdued, but any acceleration in HV5 collapses the edge - route harvesting toward IWM where VRP at 5.58% runs richer than SPY.
Skew Convexity
Quarter-delta skew prints 2.05% with smile ratio 1.13% - downside bid, but orderly. Put 17.63% carries a clean premium over ATM 16.83%, while call-side 15.58% sits flat - no upside conviction bid even with VIX ripping to 17.47.
The convexity read is Skew Steep but not panicked - tail hasn't repriced into jump territory, VVIX at 96.67 confirms the orderly bid. Naked long puts overpay for protection at this skew; put-spreads capture the directional move without funding the richened wing.
Pair the put-spread with the derived Iron Condor in 30-45 DTE to harvest the vol-rich belly while keeping tail exposure defined. Watch the call-side flatness for the first sign of upside conviction returning - a bid in 15.58% flips the convexity read before the gamma flip at 771.42 does.
What it means for your trading
Steep but orderly put skew (2.05%, smile 1.13%) favors put-spreads over naked long puts - the wing is richened without being panicked, and flat call-side 15.58% says no upside bid to fade yet.
Vol-of-Vol Structure
VVIX prints 96.67 against spot VIX at 17.47, putting the VVIX/VIX ratio at 5.53 and the derived level firmly Normal. Vol-of-vol is not confirming the VIX pop - the second derivative is calm while the first derivative rips, which is the signature of an orderly repricing, not a jump-regime bid.
With the signal color reading Green, defined-risk short-vol structures stay sized Standard Size. Market is not pricing bimodal tail risk into the vol surface itself, so the richness of front VIX is harvestable rather than a warning to flatten. Favor the derived Iron Condor in 30-45 DTE where VVIX hasn't infected the roll-down.
Trigger to half-size: VVIX breaking higher intraday while VIX holds. That sequence flips the ratio into jump-regime territory and invalidates the carry trade before the tape confirms it.
What it means for your trading
VVIX at 96.67 with the ratio at 5.53 keeps vol-of-vol Normal - size Standard Size on defined-risk short vol, only cut if VVIX accelerates independent of VIX.
Dispersion Spread
SPY ATM IV at 12.76% trades well under QQQ at 20.67%, with the tech premium widening into an idiosyncratic mega-cap drawdown. The spread confirms the volatility shock is tech-isolated, not a broad index repricing - correlation reads Moderate, which argues for selling SPY index vol rather than chasing single-name convexity in the complex driving the move.
IWM ATM IV sits at 18.35% with a VRP of 5.58% vol points - the cleanest premium harvest in the ETF triangle today. Small-cap richness over SPY's thinner VRP routes defined-risk short-vol structures toward IWM first, SPY second, QQQ last.
In a Moderate-correlation regime, single-name hedges fail to offset index exposure - the beta mapping breaks down right when traders need it. Prefer index-level expression on both the harvest and the hedge legs; let the dispersion between 20.67% and 12.76% work as a signal, not a trade.
What it means for your trading
Dispersion flags a tech-isolated shock with correlation Moderate - route the premium harvest toward IWM given VRP 5.58%, and keep single-name hedges off the book.
Liquidity & Microstructure
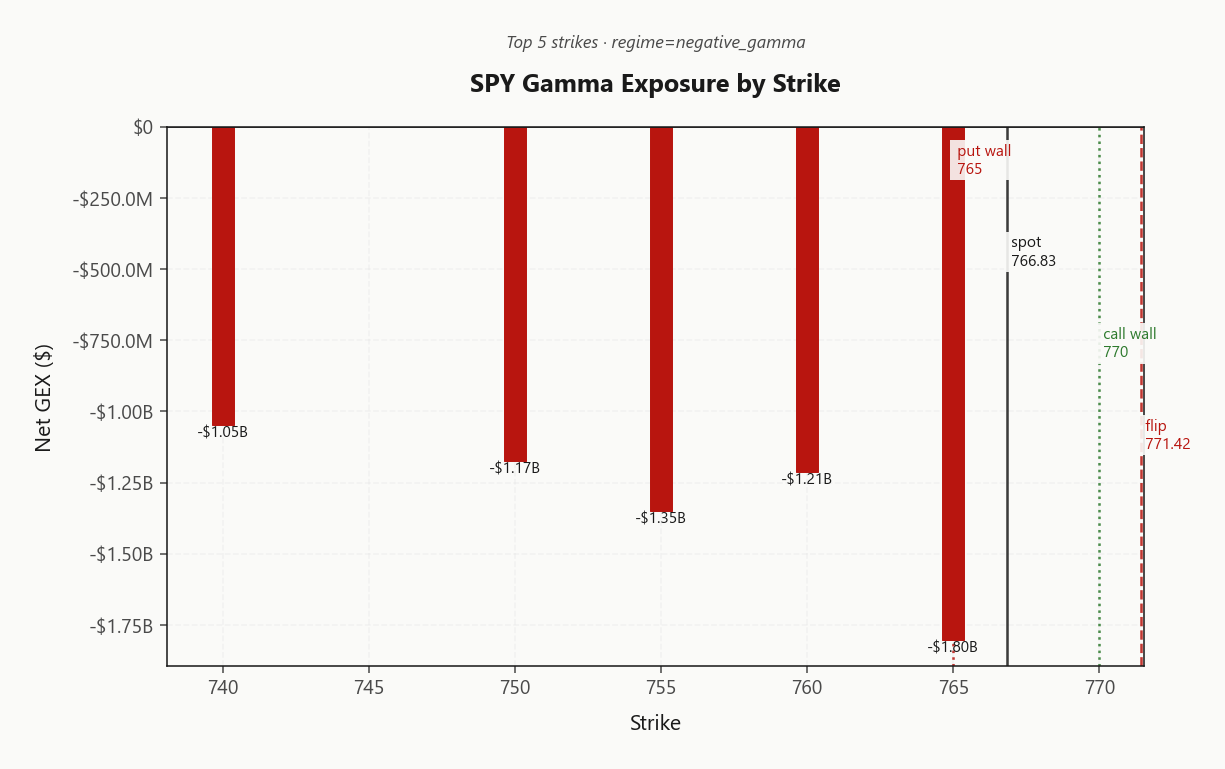
Order-book anchor sits at 500, a deep-ITM OI relic that no longer governs intraday hedging - the live map runs from the gamma flip at 771.42 down to spot 766.83, with the complex printing Negative Gamma. Below the switch, dealer flow amplifies rather than dampens; the top GEX strike at 765.00 prints -$1.8B and dominates every tick of intraday rebalancing.
The corridor is tight: call wall 770.00 caps any pop, put wall 765.00 is the next magnet lower and sits inside the top-strike cluster. Max pain at 766.00 is the first draw before dealers need to re-engage on a reclaim of the flip. Zero-DTE prints 3.8% of SPY GEX - meaningful but not dominant, so expect mean-reversion into the close only once price is back above 771.42; below it, the 0DTE book layers onto the hostile hedging flow rather than fading it.
What it means for your trading
Corridor defined by call wall 770.00 and put wall 765.00 with the top GEX strike at 765.00 dictating hedging velocity; reclaiming 771.42 is the switch from accelerant to dampener.
Trading readGEX concentration below spot through 765.00 with the call wall at 770.00 means dealers amplify on breakdowns and cap bounces - fade strength into the wall, respect the put-wall magnet.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX prints -$35.14B and that's the dominant risk in the book - vanna is hostile, so any further lift in implied vol forces dealers to sell delta into the move. The feedback loop is self-reinforcing below the flip: vol up begets more supply, which begets more vol. Net CHEX at $245.8K offers only a thin supportive bid into the bell, nowhere near enough to offset the vanna drag if VIX extends.
The charm pivot sits at 766, type Max Pain, with spot -0.1082378102% away and current bias reading Neutral. Neutral charm means time decay isn't picking a side yet - dealers aren't being handed a free hedge drift, so the tape has to resolve on gamma, not clock.
Reclaiming 771.42 is the structural switch from accelerant to dampener. Below it, every vol tick compounds; above it, dealers absorb. Trade the flip, not the headline.
What it means for your trading
Hostile vanna at -$35.14B is the lead risk - any VIX extension amplifies dealer selling until 771.42 is reclaimed. Charm pivot 766 prints Neutral, so direction resolves on gamma mechanics, not decay drift.
Cross-Asset Confirmation
MOVE prints 101.79 while VIX rips to 17.47 - the divergence is the story. Credit vol is subdued; this is an equity-isolated flight-to-safety, not a cross-asset shock. Treasuries bid, rates vol asleep, equity convexity doing the heavy lifting alone.
Fear & Greed reads Fear at 25 - already parked in fear territory before any capitulation print, which rules out an exhaustion-selling tell and sets up the contrarian defined-risk fade. SPY and QQQ regime read Aligned below the flip, so mega-cap short gamma is confirmed on both legs of the complex - no divergence to arbitrage, just magnitude.
IWM at 271.69 against QQQ at 720.19 is the day's secondary tell: small-cap resilience into a tech-led unwind argues this is a factor rotation inside equities, not a systemic de-risking. Keep the harvest routed where the premium is richest and the correlation isn't dragging the whole book.
What it means for your trading
MOVE at 101.79 vs VIX at 17.47 with Fear & Greed Fear confirms an equity-only shock, not a credit event - fade the vol pop with defined risk, route harvest toward the IWM/QQQ dispersion rather than cross-asset tail hedges.
Scenario EV
Scoring routes the book to Iron Condor at 48, decisively above the put-spread read at 37. The structure extracts the 2.45% VRP without leaning directional into a tape still parked below the 771.42 flip, and lets both wings respect the 770.00 / 765.00 corridor dealers are already defending.
The 30-45 DTE window is where this harvest actually lives. Front-week tenors sit on top of hostile vanna with net VEX printing -$35.14B; short premium in that bucket compounds against you on any further vol pop. The belly earns the richest Contango roll-down while sidestepping the gamma-flip whip governing near-dated hedging.
Keep sizing Standard Size - VVIX at 96.67 labels vol-of-vol Normal, ruling out jump-regime haircuts. If spot cracks 765.00 and directional conviction develops, rotate to the put-spread read at 37; absent that break, iron condor is the trade.
What it means for your trading
Iron condor scores 48 vs put-spread at 37 - harvest the belly in 30-45 DTE at Standard Size, keep the put-spread cocked for a 765.00 break.
Actionable Summary
Lead trade:Iron Condor in the 30-45 DTE window at Standard Size. That window sidesteps front-week hostile vanna while harvesting the richest VRP in the belly of the curve, with vol-of-vol labeled Normal giving room to work defined-risk short premium without half-sizing.
Hinge level: SPY at 766.83 sits below the gamma flip at 771.42 - reclaim flips dealers from accelerant to dampener. Charm pivot anchors 766 with bias Neutral. Corridor framed by call wall 770.00, put wall 765.00, max pain magnet 766.00.
Avoid: front-week naked vol short - net VEX -$35.14B means a further vol pop compounds dealer selling. Alternative routing: rotate harvest toward IWM, where VRP prints 5.58% versus SPY 2.45% - cleanest premium in the complex under the Elevated / Watchful regime.
Treasury yields falling as tech sells off is the classic flight-to-safety signature - bond bid confirms this is an equity-isolated event, not a credit shock, which supports mean-reversion over tail-chase.
Cramer calling this a 'fulcrum day' matches the structural read - SPY is sitting at the hinge of a gamma flip and dealers will decide the tape direction on where spot settles.
Huang telling CNBC Nvidia must work with Chinese AI firms on safety carries real headline risk for the AI capex trade that underpins the mega-cap complex's dealer positioning.
Oil shipping cost spikes feeding into pump and grocery prices keeps the inflation tail alive - matters for Fed path pricing and the duration risk under long-dated vol surfaces.
Hormuz disruption hitting harvests widens the Gulf shock from an energy story into a global supply chain narrative - slow burn risk for forward-vol pricing in the belly of the curve.
US considering heavy ordnance in Iran strike options is a tail-risk headline that would show up first in SKEW and the put-side convexity - watch tail-hedge demand in the session.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.47 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 771.42 against a spot of 766.83. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.76% with a volatility risk premium of 2.45%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.47. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime