Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 775.42 sits essentially on top of its gamma flip at 775.85 - net GEX -$3.59B, regime Negative Gamma, meaning dealers are short gamma and any directional push gets amplified rather than dampened. Call wall 780.00 caps upside, put wall 773.00 is the first support, max pain 767.00 is below spot - the magnet pulls lower if flip breaks. Dealer vanna -$121.44B and charm -$1.2M are both destabilizing: a vol pop sells deltas, time decay sells deltas, all pointing the same way. VIX 15.59 with term structure Contango and VVIX N/A at low regime says the carry trade is still open - VRP 0.79% active across the complex. Bottom line: fade strength into 780.00, respect 773.00 as the breakdown line, run iron condors at 30-45 DTE at standard size - the setup is edge-rich but the flip pin means defined-risk only.
SPY pinned at gamma flip 775.85 - destabilizing bias, VIX 15.59 in contango
SPY at 775.42 is sitting almost exactly on its gamma flip at 775.85, with dealers short gamma and charm pivot flashing destabilizing after a hot September CPI. QQQ echoes the regime below its own flip, while IWM's negative DEX and sensitive flip root argue for caution on small-cap directional bets. VIX in steep contango and VVIX at N/A still favor premium selling via iron condors at 30-45 DTE - but size standard, not aggressive, until spot clears flip.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
775.42
775.85
-0.06%
780
773
767
-$3.59B
Short gamma
QQQ
739
744.90
-0.79%
750
730
730
-$4.71B
Short gamma
IWM
273.94
285.67
-4.11%
280
270
283
-$6.46B
-
VIX
15.59
15.60
-0.03%
20
15.50
19
-$4.52M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.34
9.55
+0.79
2.23
2.31
1.27
QQQ
16.38
15.03
+1.35
2.68
1.48
1.02
IWM
16.13
11.08
+5.05
2.03
2.24
0.87
VIX
77.39
77.74
-0.35
-111.86
0.33
0.36
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.59
+2.10%
VVIX
88.16
+3.26%
SPX
7,777.22
-0.36%
SKEW index
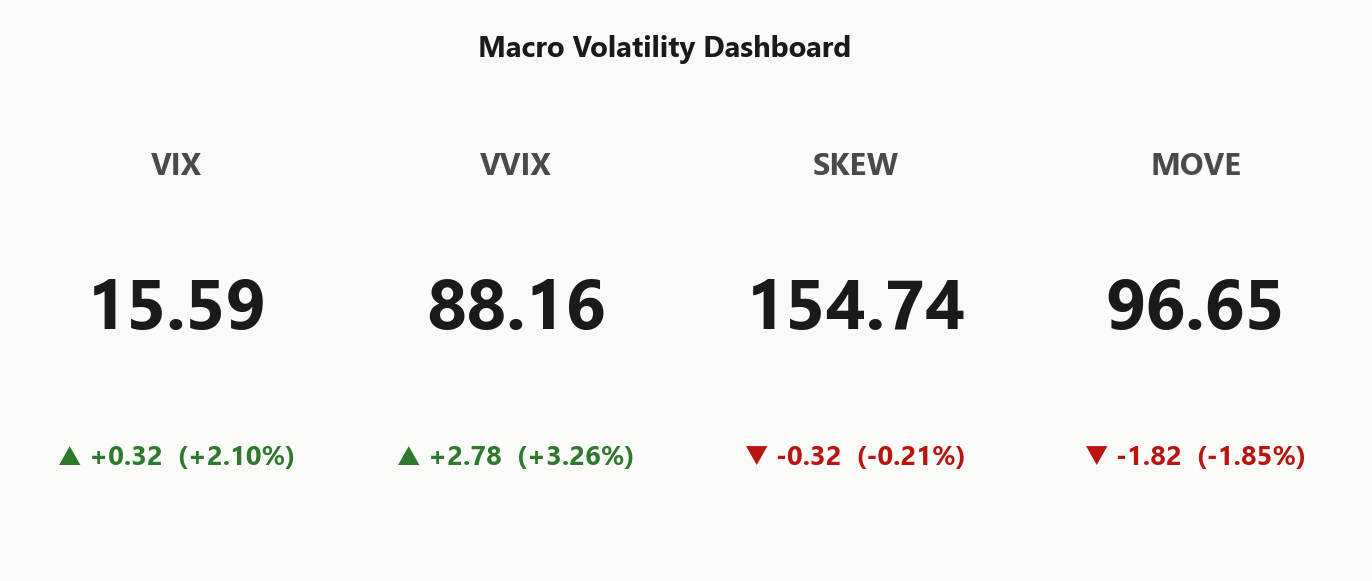
154.74
-0.21%
MOVE (bond vol)
96.65
-1.85%
VIX term (9d/30d/3m/6m)
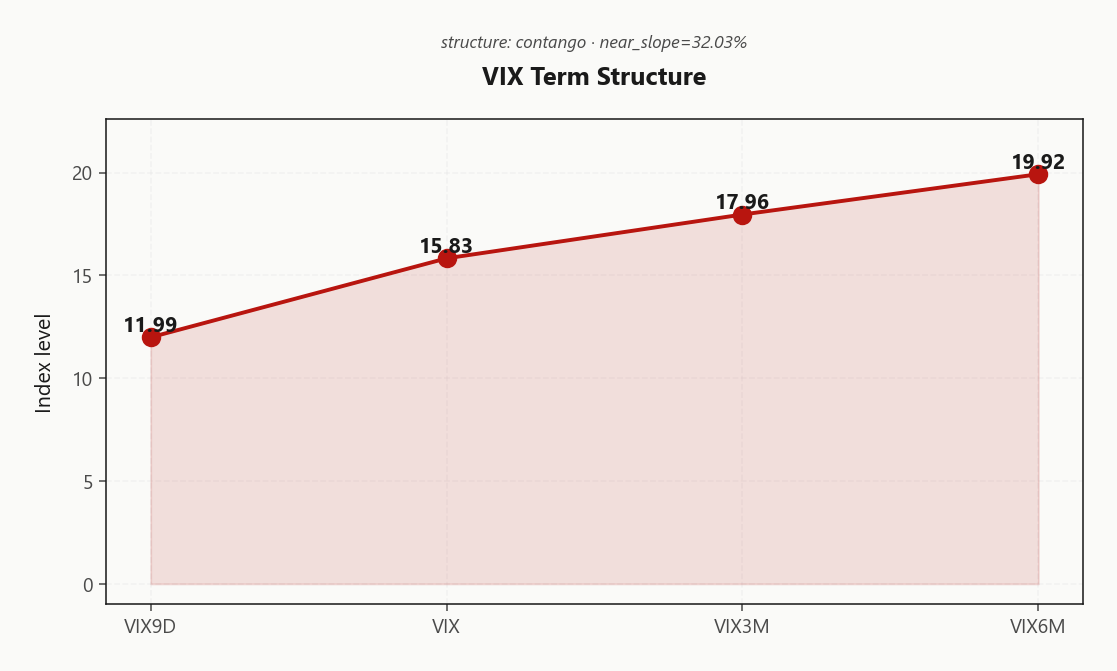
11.99 / 15.83 / 17.96 / 19.92
Steep contango
VVIX / VIX
5.65
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime reads Elevated - Elevated / Watchful - with VIX at 15.59. The transition matrix prints a to-panic probability of 0.05 over five sessions against a to-low probability of 0.45 over ten. Sticky-elevated, not escalating - the tape is nervous, the regime is not breaking.
Half-life of 15 sessions anchors roughly three trading weeks of persistence, long enough to collect carry through the 30-45 DTE window the scorer prefers. Low panic-escalation odds plus VVIX at N/A in the Low bucket keep short-vol structures standard-sized and defensible.
Tripwire is single-variable: a VIX break above the next step-up pivot flips the entire book - vanna goes from hostile to vicious, charm pivot at 775.847657922 loses its tether, and the carry trade closes. Until then, bias stays Destabilizing but tradable.
What it means for your trading
Regime is Elevated / Watchful at VIX 15.59 with a 15-session half-life - short-vol structures stay on, sized standard, with the VIX step-up as the single kill-switch.
Trading readVIX up, VVIX up by more percentage, SKEW flat, MOVE lower - vol markets are nervous about equity vol itself, not bonds. That specific divergence is a classic late-cycle equity-only wobble, not a credit event.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is Contango with 11.99 on the front, 15.83 at the spot node, and 17.96 and 19.92 stacked progressively higher. Near slope at 32.03% confirms no event premium is being bid into the front - the hot CPI shock is being priced as a transient repricing, not a regime break. The derived forward-vol state reads Steep Contango.
VIX9D printing well under VIX says next-week realized is expected to undershoot next-month implied - the textbook calendar setup. Forward 30-to-60 and 60-to-90 points carry higher still, so roll-down is paid for anyone short the belly against a cheap back-month long. Sellers of 30-45 DTE vol collect the richest decay before gamma risk accelerates.
Tactically: fade the belly, carry a cheap front-week tail against it, and let the curve pay for the position. The carry story stays open until the front-end slope flattens or inverts.
What it means for your trading
Steep contango with 11.99 well under 17.96 keeps the vol-seller's carry trade open at the 30-45 DTE belly, with cheap front-week optionality as the tail hedge.
Trading readSteep contango with VIX6M 19.92 well above spot VIX 15.83 says the market expects today's inflation shock to fade - carry trade stays open, event premium is in the deep back end only.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 10.34% sits well above realized - HV20 9.55 and the much softer HV5 6.12 confirm that recent tape has not kept pace with the implied repricing. VRP prints 0.79% with the IV/RV spread tagged Thin Premium - thin at the index level but unambiguously on the sell side of the complex.
IWM is where the harvest lives. IWM VRP at 5.05% dwarfs SPY's 0.79% and QQQ's 1.35%, with IWM ATM IV 16.13% running far richer than its realized footprint. Small-cap IV is paying up for a realized path that has not materialized - the asymmetric premium-seller candidate within the index book.
HV decelerating against a sticky IV repricing is the textbook VRP-active regime. Carry is paid across the complex; concentrate size in IWM, diversify through SPX, and keep structures defined-risk given the destabilizing charm backdrop.
What it means for your trading
VRP is active across the complex with HV running well below ATM IV at 10.34% - IWM VRP 5.05% is the standout harvest, with SPX as the diversifier.
Skew Convexity
SPY twenty-five-delta skew prints 2.23% with smile ratio 1.19% - a left-tail bid that is ordered, not panicked. Put wing at 14.17% trades meaningfully over ATM 13.42%, while the call wing at 11.94% sits below ATM - downside pays up, upside is flat. No conviction call-chase, no catastrophic hedging bid either.
A smile ratio above parity but holding this far from extremes reads as defensive book-building, not forced buying. The put wing is doing the work consistent with routine hedging flow against the gamma-flip proximity, not a crash premium. Dealers are compensated for the left tail; they are not being overrun by it.
Trade implication: with the put wing already paid, naked short puts give back edge the market is handing you. Prefer put spreads and the short wing of an iron condor at 30-45 DTE - sell the rich put, buy the richer put, pocket the skew differential as structural edge.
What it means for your trading
Skew is bid but orderly - downside at 14.17% versus flat upside at 11.94% says hedge the way the market has already paid: put spreads over naked puts, and lean on the condor's short put wing to monetize smile ratio 1.19%.
Vol-of-Vol Structure
VVIX at 88.16 against VIX 15.59 prints a ratio of 5.65 - squarely in the Low regime. The market is not bidding bimodal jump premium into the VIX itself; the second-order curve is quiet even as spot sits on the flip and charm flashes destabilizing.
That matters for sizing. Low vol-of-vol is the green light for Standard Size on short-vol structures - iron condors at 30-45 DTE do not need to be haircut here on fear of a VIX gap. Combined with steep contango and an active VRP, the carry window is open at normal risk units, not half.
The watch is asymmetric: a VVIX pop typically front-runs the spot VIX, so any lurch above the sub-ninety ceiling is the early-warning tell to defend wings before VIX itself repositions. Until then, treat the second-order curve as permission, not a hedge trigger.
What it means for your trading
VVIX at 88.16 keeps the vvix/vix ratio in the Low regime - short-vol structures size standard, with a VVIX break above the sub-ninety ceiling as the early-warning tripwire.
Dispersion Spread
IV dispersion across the complex is moderate - SPY ATM IV at 10.34% sits well under QQQ at 16.38% and IWM at 16.13%, with cross-strike dispersion of 82.63 against cross-expiry 3.16. Idiosyncratic risk is bid but not screaming, which is exactly the regime where the index vol harvest beats single-name premium selling on a risk-adjusted basis.
With cross-asset tone Aligned and all three indices sitting in a shared short-gamma backdrop, correlation is high enough that single-name shorts leak into index beta on any wobble. Prefer index iron condors at 30-45 DTE as the primary carry vehicle - the implied-correlation discount for selling the index wrapper is doing real work here.
IWM is the richest IV in the complex and the obvious single-ticker short-vol candidate if you want satellite exposure around the index core - small-cap VRP is the standout harvest, but keep it defined-risk given sensitive flip root.
What it means for your trading
Moderate dispersion with IWM carrying the richest ATM IV at 16.13% vs SPY 10.34% favors index iron condors as the core trade, with IWM as the single-ticker satellite for the fattest VRP.
Liquidity & Microstructure
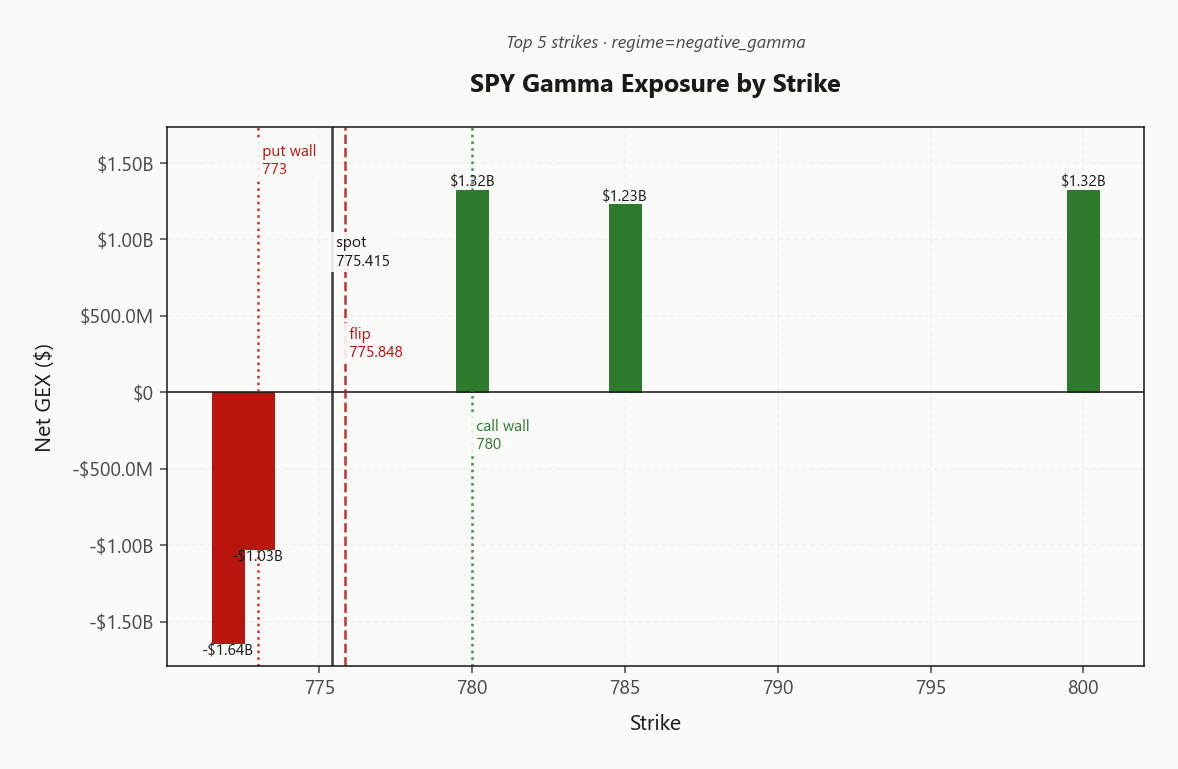
SPY's standing book is anchored at 500 by legacy OI, but the live GEX cluster has migrated to 772.00 with net GEX -$1.64B - the real battle is at the top of the stack, not where open interest looks fattest on the surface.
Gamma flip sits at 775.85, essentially on top of spot 775.42. Above it, dealer hedging dampens; below it, dealer selling amplifies. The call wall at 780.00 caps upside into any rally, while 773.00 is the first mean-reversion stop on a breakdown - the corridor between those two levels is where price action gets routed.
Zero-DTE share runs 30.4% of total GEX - enough to drive intraday pin pressure around key strikes without overriding the broader short-gamma regime. Expect ranges wider than a textbook pin day, with magnet pull toward max pain at 767.00 if flip breaks.
What it means for your trading
Flip at 775.85 is the single actionable level - reclaim stabilizes the tape, lose it and dealer selling amplifies into 773.00. Trade the corridor, respect the walls, keep structures defined-risk.
Trading readPositive GEX stacked at 780.00 and above caps upside into the wall, while negative concentration right at and below spot means any slip through flip gets amplified - fade strength into the wall, do not chase breakdowns from below the flip without defined risk.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX at -$121.44B and net CHEX at -$1.2M are both negative - this is the destabilizing flow signature where a vol pop sells deltas and time decay sells deltas, both pushing the tape the same way. Dealer vanna is hostile: any VIX uptick immediately amplifies downside via forced delta hedging rather than cushioning it. The charm pivot sits at 775.847657922 with current bias Destabilizing - the single most actionable flow signal on the board today.
Operationally, charm pressure builds into the close as dealers reprice their delta books, which means late-day strength gets faded by hedging flow rather than extended. Fade rallies into 780.00, respect 773.00 as the breakdown line, and flip the bias only on a clean reclaim of 775.847657922 - anything less is noise around the pin.
What it means for your trading
Vanna and charm both negative with spot pressed against the pivot at 775.847657922 means dealer hedging flow amplifies rather than dampens - fade late-day strength and keep structures defined-risk until the pivot reclaims.
Cross-Asset Confirmation
MOVE sitting at 96.65 and softening is the tell: rates vol is not confirming the equity-vol bid. This is positioning, not a credit shock. Fear & Greed printing Fear at 42 rounds out the contrarian setup - sentiment is washed enough to pay the short-vol seller, not yet extreme enough to force an upside hedge pivot.
QQQ at 739.00 and IWM at 273.94 both trade below their gamma flips, matching SPY's posture on 775.85. The complex is Aligned - one story, one book, one trigger. Cross-asset tone reads Unknown, which argues for index structures over single-name expression and against hedging as if credit were cracking.
Trade the alignment: harvest VRP via index iron condors, let the destabilizing charm print its own fade into the bell, and keep the MOVE tape on screen as the regime tripwire.
What it means for your trading
MOVE at 96.65 softening alongside a Fear F&G of 42 and all three indices below their flips confirms a single Unknown short-gamma regime - size the harvest in the index book, not in credit hedges.
Scenario EV
The scorer picks Iron Condor with a best score of 36 at 30-45 DTE, outpacing the put-spread alternative by a clean margin. VRP active across the complex, VVIX at N/A parked in low regime, and VIX term structure in Contango is the textbook iron condor setup - carry wins even against destabilizing charm.
The 30-45 DTE window is the sweet spot: far enough out to harvest theta before gamma risk accelerates into expiry, close enough to capture the roll-down carry priced into forward vol. IWM VRP at 5.05% is the richest premium in the complex, with SPX as the diversifier.
Sizing stays standard per VVIX guidance - do not scale up. Spot sitting on the gamma flip at 775.85 with net CHEX -$1.2M destabilizing means defined-risk only; keep wings tight until flip resolves.
What it means for your trading
Iron condor at 30-45 DTE beats put-spread on the scorer and fits the VRP-active, low-VVIX, steep-contango regime. Standard size, defined risk - flip proximity caps the aggression.
Actionable Summary
Trade:Iron Condor at 30-45 DTE on SPX/SPY at standard size, with IWM preferred as the richest VRP leg at 5.05%. Score margin of 36 over the put-spread alternative confirms the carry wins despite destabilizing charm - defined-risk only with spot pinned on the flip.
Watch: the single level that flips the regime is a clean reclaim of 775.847657922; current bias reads Destabilizing against regime label Elevated / Watchful. Below it, dealer short gamma amplifies any slip toward 773.00; above it, the cushion returns and the book stabilizes.
Avoid: naked short puts into hostile charm and upside chases into the 780.00 wall. Hedge: carry a small long-vol tail via cheap VIX9D optionality at 11.99 - steep contango makes the wing cheap insurance against a flip-break acceleration.
Hot September CPI with firmer core is the macro input that just repriced the entire front-end vol curve - this is why SPY opened on its flip, not above it.
Cramer's watch list is noise, but the embedded detail - hot CPI confirmed and strong Morgan Stanley equities trading - says institutional risk appetite is intact despite the inflation surprise.
Houthi strike on Aramco HQ with pledged escalation reinjects energy tail risk; oil-sensitive names and the broader risk-off impulse into the open deserve attention.
Extensive damage at Aramco HQ meaningfully raises the odds of a sustained oil premium - not a one-day news event, a positioning input for next-month vol.
Oil tanker-attack tactics shift signals a structurally higher energy-shock probability into year-end - bid for far-dated oil and energy-sector hedges.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.59 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 775.85 against a spot of 775.42. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.34% with a volatility risk premium of 0.79%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.59. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime