Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY trades 769.47 with net GEX at -$13.86B - dealers are short gamma and sitting below the 774.64 gamma flip, so any sustained push gets amplified rather than dampened. The level map is tight: call wall 770.00 is right overhead, put wall 765.00 sits just underneath, and max pain prints 767.00 - a compressed corridor where dealers have no cushion to work with. Dealer Greeks lean hostile: net VEX at -$63.2B means a vol spike forces more delta selling, while charm at $3.3M offers only mild stabilization into the close. Vol read is split: VIX popped to 16.52 on hot CPI but term structure stays in Contango (15.47%% near slope) and VVIX at 94.51 is still in the normal zone, so the forward curve says sellers still get paid even as spot is fragile. VRP at 1.39% is active and the recommended structure scores to Iron Condor at 30-45 DTE. Cross-asset is aligned negative-gamma across SPY and QQQ with IWM Unknown, MOVE at 96.65 is tame - this is an equity-vol event, not a credit shock. Bottom line: harvest premium with iron condors anchored around the wall complex, keep size standard per VVIX, and treat 774.64 as the regime line - a reclaim flips dealers back to stabilizing, a break opens the trap door to the put wall.
Hot September CPI pressured SPX down over 1% and dragged SPY under its gamma flip at 774.64, flipping dealers short gamma just as VIX popped 8.19%%. Term structure stays in steep contango and VVIX printed 94.51, so the forward curve says sellers still get paid - but intraday dealers now amplify every push toward the 765.00 put wall and the 770.00 call wall. Playbook: harvest the VRP in 30-45 DTE iron condors anchored around the wall complex, respect the flip as the regime line.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
769.47
774.64
-0.67%
770
765
767
-$13.86B
Short gamma
QQQ
730.01
740.35
-1.40%
760
730
730
-$8.85B
Short gamma
IWM
271.46
286.28
-5.18%
280
270
283
-$6.90B
-
VIX
16.53
17.17
-3.73%
20
16
19
-$50.89M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.49
10.10
+1.39
1.80
2.31
1.33
QQQ
18.68
16.37
+2.31
2.54
1.48
1.00
IWM
17.24
12.49
+4.75
2.50
2.24
1.92
VIX
78.89
80.24
-1.35
-94.55
0.33
0.24
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
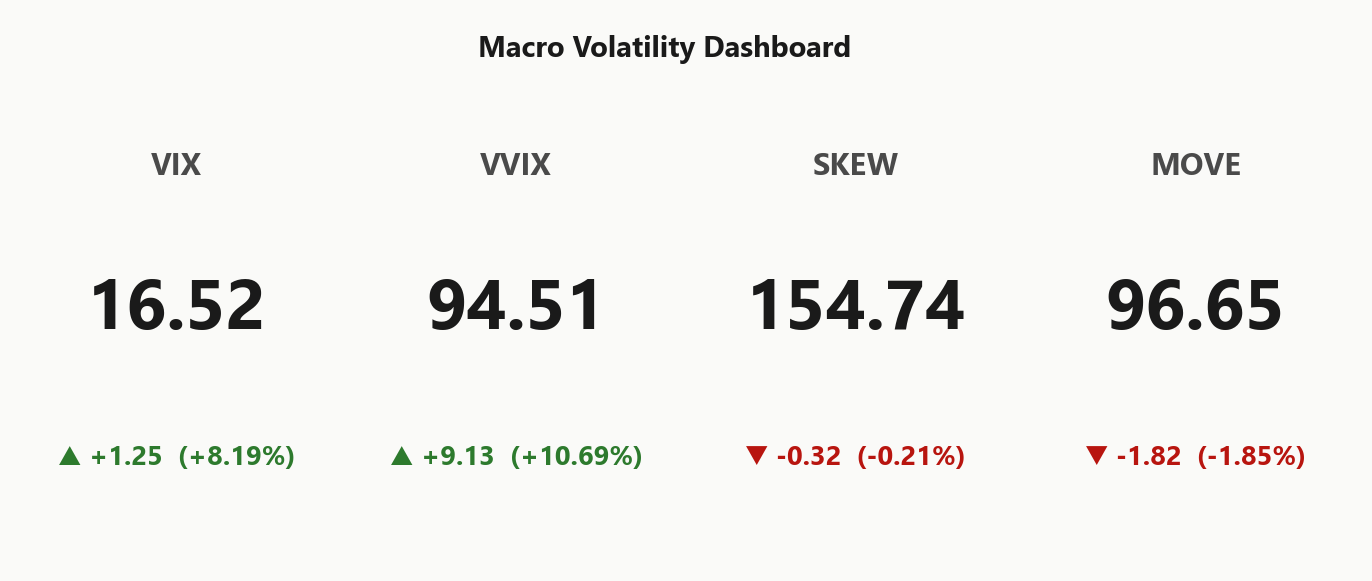
16.52
+8.19%
VVIX
94.51
+10.69%
SPX
7,720.18
-1.09%
SKEW index
154.74
-0.21%
MOVE (bond vol)
96.65
-1.85%
VIX term (9d/30d/3m/6m)
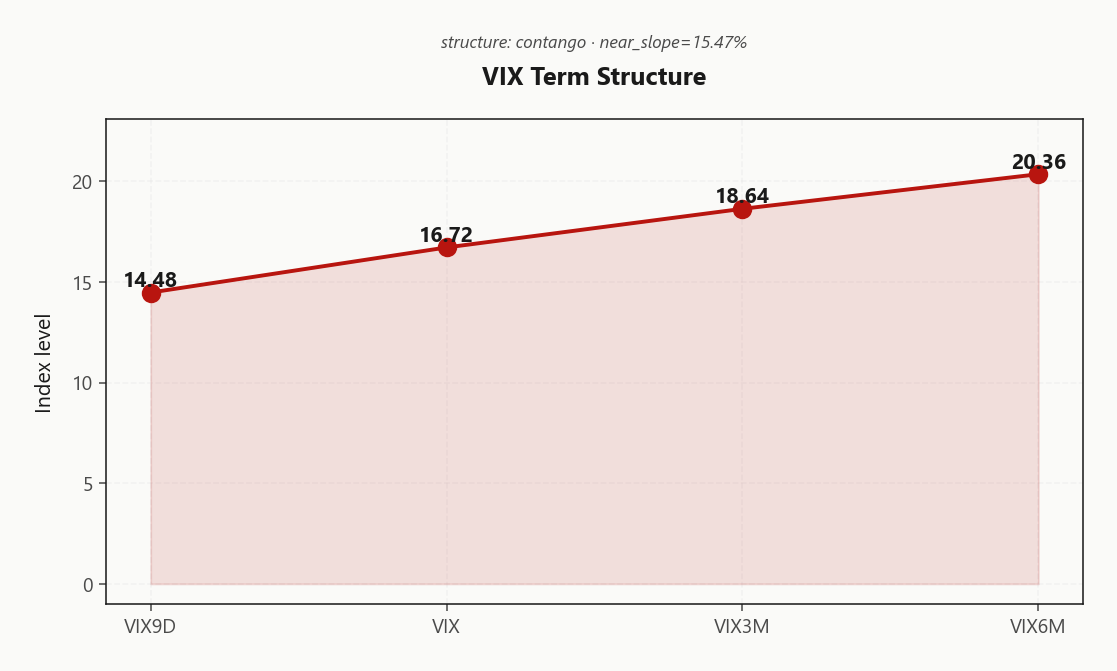
14.48 / 16.72 / 18.64 / 20.36
Steep contango
VVIX / VIX
5.72
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in a Elevated / Watchful regime with VIX at 16.52 - elevated enough to respect, not so stretched that the panic playbook kicks in. The transition matrix pegs the probability of a slide into panic within five sessions at 0.05, so tail risk is contained even as spot trades under the gamma flip.
Mean-reversion back to the low-vol regime inside ten sessions prints at 0.45 - a coin-flip minus, meaning the regime is sticky and this stays the operating backdrop for weeks, not days. Half-life clocks 15 sessions, which is the window every open structure should be built to live inside.
Posture: stay cautious, don't retreat. Standard size per VVIX in the normal band, 30-45 DTE short-premium structures favored, and the 774.64 flip is the regime line that would flip this read either direction.
What it means for your trading
Current regime is Elevated with a 15-session half-life - low near-term panic odds (0.05) paired with sticky mean-reversion (0.45) tells you to harvest premium at standard size, not retrench.
Trading readVIX up, VVIX up more in percent terms, SKEW roughly flat, MOVE actually down - macro vol signals confirm this is an equity-specific CPI reaction with hedging demand elevated but no systemic stress yet.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Front-week vol took the CPI hit cleanly - 14.48 VIX9D printed under 16.72 VIX while VIX3M held at 18.64, keeping the broader curve in Contango. The near slope at 15.47%% prints Steep contango - vol sellers favored - a tactical event-vol pop, not a systemic repricing of forward uncertainty.
The 30-60 and 60-90 forward segments sit well below the back month, so the carry trade stays intact for the structural seller. Edge concentrates in 30-45 DTE, where term vol remains rich to realized without carrying the blown-out 0-7 DTE tape that CPI just distorted. Shorter than that and you own the event noise; longer and you give up the richest roll-down.
VIX futures in Contango at a 11.48%% basis confirm the roll-down tailwind for calendars and short-vol structures. Combined with VRP at 1.39% and VVIX at 94.51 in the Normal band, the forward curve is still paying sellers to look past the near-dates.
What it means for your trading
Steep contango past the first week says this is CPI noise, not a regime shift - harvest term VRP in the 30-45 DTE sweet spot where carry is cleanest and the inverted front-week tape stays out of the structure.
Trading readFront curve inverted on the CPI event, back curve in clean contango - the vol carry trade is intact beyond the first week, and the signal is 'tactical event' not 'regime break'. Term sellers get paid to look past the near-dates.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
The volatility risk premium is active across the index complex even as spot cracks the flip. SPY ATM IV at 11.49% sits meaningfully over 20-day realized at 10.1, leaving a VRP of 1.39% - paid to be short even on a down tape. Short-window realized at 9.04 has not accelerated into the CPI flush, confirming the vol being bought is forward hedging demand, not catch-up to actual spot moves.
Across the complex, IWM carries the richest cushion with VRP at 4.75%, QQQ second at 2.31%, SPY third at 1.39%. The spread-engine assessment flags the regime as Thin Premium - options are rich to realized without being frothy, the exact backdrop short-vol structures feed on.
Routing read: harvest, don't chase. IWM is the fattest premium host, SPY the cleanest execution, QQQ sits in between. The absence of realized follow-through under the flip tells you dealers are amplifying noise, not trending volatility - iron condors anchored around the wall complex capture the full VRP without taking the hostile-vanna hit of naked structures.
What it means for your trading
VRP is cleanly active with IWM at 4.75% leading SPY at 1.39%, and realized at 9.04 is not catching up - this is a Thin Premium harvest regime, not a chase.
Skew Convexity
Front-week skew prints 1.8% with a smile ratio of 1.13% - an orderly downside bid, not a convex tail chase. Put 25d IV at 15.93% sits a notch above ATM at 15.25%, while the call wing fades to 14.13% - a flat-to-inverted upper wing that reads as zero upside conviction rather than panic hedging.
Cross-asset, the shape travels: IWM at 2.5% and QQQ at 2.54% track SPY's curvature with no divergence to lean on. Tail bid is uniform across the complex, which removes any single-index asymmetry for directional convexity trades.
Playbook: with the put wing respectfully bid but not stretched, put spreads price better than naked puts for defined-risk hedges - you're financing protection against the richer side. For premium sellers, the balanced wing richness is the exact backdrop the Iron Condor wants: both wings carry edge, neither screams.
What it means for your trading
Skew is steep enough to pay respect at 1.8% but ordered enough - smile ratio 1.13% - to favor spread structures over outright convexity. The flat call wing confirms the market has no appetite to pay up for upside, which cleanly supports the Iron Condor routing at 30-45 DTE.
Vol-of-Vol Structure
VVIX prints 94.51 (+10.69%%) against VIX at 16.52, pushing the ratio to 5.72 - squarely in Normal territory. The market is paying up for vol-of-vol as a hedge, not pricing the bimodal panic/crush tail. Standard sizing holds: the engine routes to Standard Size, no reason to trim iron condor notional yet.
The tell is that VVIX popped harder than VIX in percent terms. That's hedging demand bleeding into the second moment, not forced liquidation of vol inventory - a crush regime shows the opposite footprint, with VVIX lagging as dealers unwind convexity. Here, convexity is being bought, which keeps the short-premium carry trade intact even with spot pressed below the 774.64 flip.
Trigger to flip defensive: a sustained VVIX break into the elevated band paired with front-week skew steepening. Either alone is noise; together they signal the hedge bid turning into a convexity grab, which is when iron condors need to come down to half-size.
What it means for your trading
VVIX at 94.51 sits in Normal range despite the pop, so sizing stays at Standard Size; watch for VVIX pushing elevated alongside steepening skew as the paired trigger to defensively trim.
Dispersion Spread
Dispersion prints Moderate - single-name correlation isn't loose enough to crown idiosyncratic hedges, but it's tight enough that index-level short vol stays the cleaner carry. SPY ATM IV at 11.49% sits against QQQ 18.68% and IWM 17.24%, with IWM carrying the fattest premium of the complex and the richest harvest target on a vol-per-unit-realized basis.
IV dispersion field reads {"cross Expiry":2.79,"cross Strike":65.21} - cross-strike richness dominates cross-expiry, which maps directly onto the mover complex: AAPL, MSFT, META, NVDA, and GOOGL are doing the heavy lifting on single-name vol while the index itself trades in sympathy. That's a backdrop where index short premium still beats single-name on a risk-adjusted basis, because the charm complex supports index-level stabilization into the close, not scattered single-name tape.
Routing: SPY/SPX for the primary short-vol engine, IWM as the premium-rich satellite, single-name NVDA/TSLA/AMD left to the dispersion specialists until correlation re-tightens.
What it means for your trading
Dispersion at Moderate keeps index short-vol as the cleanest trade - SPY/SPX over single-name until correlation re-tightens, with IWM's 17.24% ATM IV marking the fattest premium harvest in the complex.
Liquidity & Microstructure
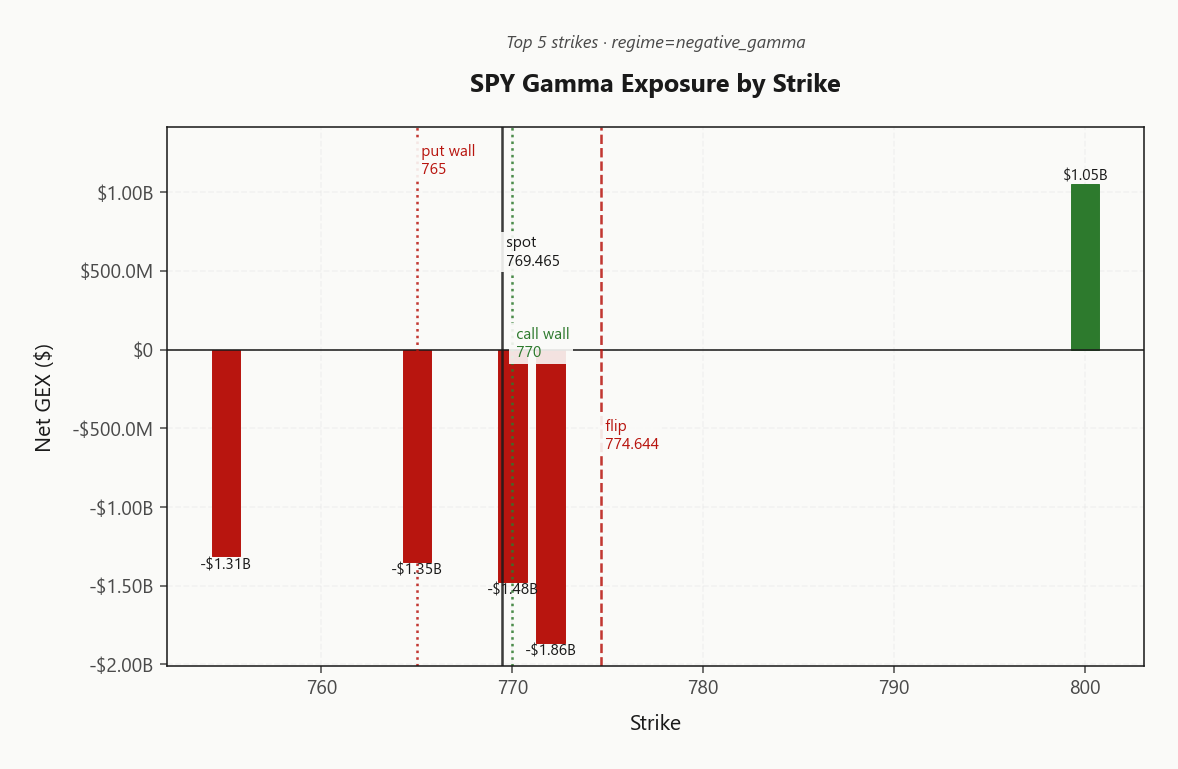
OI topology is textbook negative-gamma trap. The heaviest clusters sit at the 765.00 put wall / 770.00 call wall corridor straddling spot, and the gamma flip at 774.64 is the regime line - above it dealers stabilize, below it they amplify. Spot at 769.47 currently sits just under the flip, so every downside push gets more fuel from mechanical hedging.
The anchor is right at the tape: top strike 772.00 prints net GEX of -$1.86B, the single biggest negative-gamma magnet pressing on price. 0DTE contributes 23.2% of total gamma - meaningful amplification, but not the dominant driver. The real weight is the longer-dated OI stack, with the far-OTM 500 acting as a structural anchor rather than a tactical magnet.
Trade the amplification, don't fade it: a reclaim of 774.64 flips dealers back to stabilizing; a confirmed break makes 765.00 the next magnet.
What it means for your trading
The gamma flip at 774.64 is the only level that matters - spot sits just below it with the heaviest negative-gamma anchor at 772.00 doing the mechanical work. Treat the 765.00/770.00 corridor as a compressed trading range until the flip is reclaimed.
Trading readDeep negative-gamma cluster sits right under spot at the 765.00/770.00 corridor - every push lower feeds dealer selling until spot can reclaim the flip above. Trade the amplification, don't fade it.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer Greeks lean hostile. Net VEX prints -$63.2B - deeply negative vanna means any vol pop forces dealers shorter delta, converting a VIX spike into a spot flush rather than absorbing it. This is the vanna accelerant that defines the regime: the vol curve and the tape are mechanically linked on the way down.
The regime line is the 770 pivot (Call Wall), with current bias Neutral and spot sitting just 0.0695288285% away. One solid session either way flips the read: a reclaim turns dealers back to stabilizers, a confirmed break opens the trap door.
What it means for your trading
Hostile vanna at -$63.2B with only weak charm support at $3.3M means a vol spike compounds the drop - until spot reclaims the 770 pivot, treat naked short premium as a mistake and let defined-risk structures do the harvesting.
Cross-Asset Confirmation
Cross-asset signals confirm this as an equity-vol event, not a credit shock. MOVE prints 96.65 (-1.85%% d/d) - rates vol cooled while equity vol popped, the cleanest tell that CPI hit the SPX complex specifically rather than reverberating through fixed income. Fear & Greed at 34 / Fear says positioning was already defensive heading in - no capitulation signature, no margin-call fuel pile.
The index complex trades in sympathy, not divergence. QQQ at 730.01 and IWM at 271.46 track SPY under their respective flips with cross-asset tone Unknown and divergence direction Aligned. No single index is acting as the circuit-breaker and no leader is pulling the group out - the whole stack breaks or holds together.
The playbook distinction matters: credit shocks compound through sessions, CPI and geopolitical shocks mean-revert. That favors premium sellers over tail-chasers, and keeps the harvest regime intact as long as MOVE stays cooperative.
What it means for your trading
Rates vol down, equity vol up, aligned regime across SPY/QQQ with IWM in sympathy - this is a tactical CPI reaction, not a systemic break, so lean into VRP harvest rather than chase tails.
Scenario EV
The scoring engine routes to Iron Condor at 30-45 DTE with a best score of 40, edging the put spread by a clean margin and shutting out naked short premium entirely. The disqualifier for naked structures is the hostile vanna stack: net VEX at -$63.2B turns any vol pop into forced delta selling, exactly the convexity you do not want to be short of right now.
Iron condor wins over the put spread because the skew is ordered, not panicked: smile ratio at 1.13% says both wings carry respectable premium, so a defined-risk short-vol structure captures the full VRP instead of leaving the call side on the table. The 30-45 DTE sweet spot sidesteps the CPI-blown front-week inversion and parks the position inside the richest term-VRP band, with the Contango back-month shape adding roll-down tailwind.
Execution: anchor wings outside the 770.00 call wall and 765.00 put wall, and let the dealer complex do the heavy lifting on both sides. VVIX in the Normal band flags Standard Size; trim to half only if VVIX breaks into elevated.
What it means for your trading
Trade the regime, do not fight it: the stack says sell premium via Iron Condor at 30-45 DTE with wings parked outside the 770.00/765.00 corridor, Standard Size per VVIX, and treat 774.64 as the kill switch if spot keeps breaking lower.
Actionable Summary
Trade the tape, don't fight it. With SPY printing 769.47 under the 774.64 gamma flip and net GEX at -$13.86B, dealers amplify every push. The scoring engine routes to an Iron Condor at 30-45 DTE on SPY, wings anchored outside the 770.00 call wall and 765.00 put wall. VVIX sits in the Normal band at 94.51 - keep sizing standard, not defensive.
Route single-asset short premium through IWM for the fattest VRP in the complex at 4.75%, versus SPY at 1.39%. Avoid naked straddles and strangles - net VEX at -$63.2B is hostile vanna, meaning any vol pop deepens the delta hole. Defined-risk wings do the work the dealer complex won't.
Levels that matter. The 770 pivot is the regime line: a reclaim flips dealers back to stabilizing; a confirmed break opens the trap door to the 765.00 put wall. Watch VVIX for a jump out of Normal into elevated - that's the half-size trigger. Regime read is Elevated / Watchful.
What it means for your trading
Harvest the VRP via a Iron Condor at 30-45 DTE anchored to the SPY wall complex, lean IWM for the fattest premium, and use the 770 pivot as the regime line. Standard size holds while VVIX stays Normal; naked short vol is off the table while VEX is this hostile.
Hot September CPI with firmer core is the proximate catalyst for today's SPY flush under the gamma flip and the VIX pop - this is the macro print the entire session is trading around.
The CPI reaction and Morgan Stanley trading beat frame today's price action: hot inflation hits the vol complex while bank earnings keep single-name dispersion elevated - both tailwinds for premium harvest.
India's wholesale inflation surprise reinforces the global sticky-inflation theme the US CPI print just extended - background support for the elevated regime read, not a direct catalyst.
A container ship sinking near Hormuz after a projectile hit is an exact tail-risk headline - matters because the MOVE index did not react, confirming the market is pricing this as contained geopolitical noise rather than a systemic rates shock.
Houthi attack reportedly causing extensive damage to Saudi Aramco HQ keeps the Middle East risk premium live, but with no energy-market panic in the tape it reads as a slow-burn tail watch, not an imminent catalyst.
Houthi commitment to more attacks on Saudi airports and oil facilities compounds the geopolitical tail - the market has absorbed it so far, so the signal is more about residual risk if headlines escalate than today's direct action.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.53 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 774.64 against a spot of 769.47. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.49% with a volatility risk premium of 1.39%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.52. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime