Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed at 769.04, below the gamma flip at 774.65 - dealers short gamma, net GEX -$10.77B, moves get amplified not dampened. Call wall at 800.00, put wall at 765.00, max pain at 767.00 - spot pinned right at max pain into the close, but the amplification regime says tomorrow's open sets the tone. Dealer vanna is hostile here: a vol spike forces more delta selling, and net VEX at -$59.91B tells you the leverage is real. VIX at 16.89 with VVIX at 94.71 - both up double-digit percent on the session, but term structure stays Contango with front-month basis of 11.5%%. VRP at 1.37% says options are still richer than realized - carry trade intact, just not screaming. Bottom line: Iron Condor in the 30-45 DTE pocket, strikes outside the 765.00/800.00 corridor, standard size - not a day to press.
SPY settled below the gamma flip at 774.65 with dealers short across the index complex, converting any directional push into an accelerant. VIX bid alongside VVIX says the market is paying up for vol-of-vol even as the term structure stays in Contango. The 30-45 DTE window remains the carry sweet spot - but respect the walls at 765.00 and 800.00.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
769.04
774.65
-0.73%
800
765
767
-$10.77B
Short gamma
QQQ
727.88
739.55
-1.58%
760
725
730
-$7.42B
Short gamma
IWM
271.07
286.39
-5.35%
290
270
283
-$6.80B
-
VIX
16.85
17.16
-1.79%
20
16
19
-$36.47M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.66
10.29
+1.37
1.49
2.31
1.19
QQQ
19.25
17.02
+2.23
3.86
1.48
0.92
IWM
17.18
12.73
+4.45
2.46
2.24
1.85
VIX
78.79
85.64
-6.85
-79.51
0.33
0.30
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
16.89
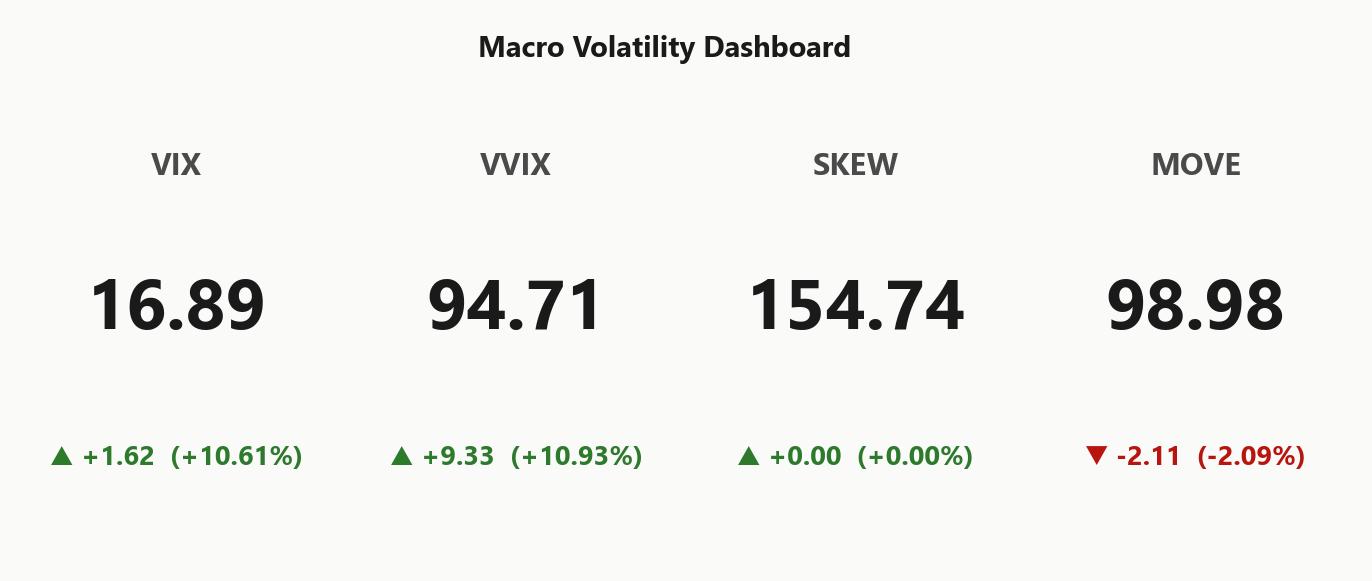
+10.61%
VVIX
94.71
+10.93%
SPX
7,718.94
-1.11%
SKEW index
154.74
0.00%
MOVE (bond vol)
98.98
-2.09%
VIX term (9d/30d/3m/6m)
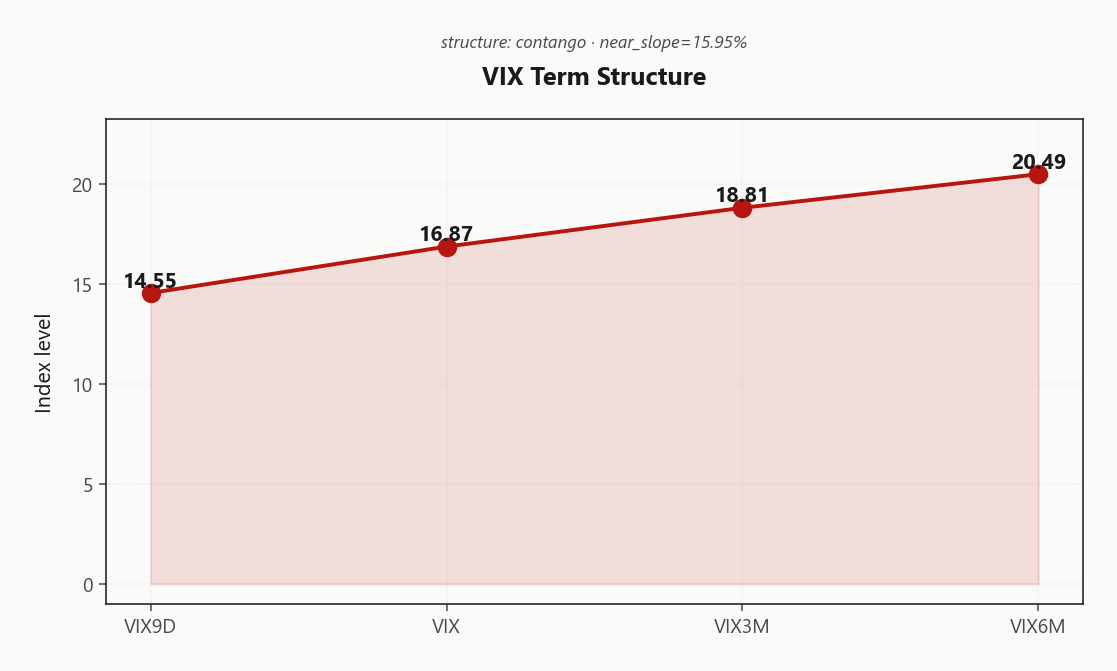
14.55 / 16.87 / 18.81 / 20.49
Steep contango
VVIX / VIX
5.61
Normal
Regime
Elevated / Watchful
Regime Assessment
Current state reads Elevated / Watchful - VIX at 16.89 sits in the uncomfortable middle: too bid to sell with both hands, too contained to buy tails outright. The transition math says what the tape won't: probability of rolling into panic over the next five sessions is 0.05, probability of melting back to low-vol over ten is 0.45. The base case is neither spike nor collapse - it's chop.
Half-life of 15 sessions is the number that matters. This regime is sticky. Plan a multi-day book, not a one-print reaction. The classifier labels the state Elevated, signal Elevated - carry is still paid at 30-45 DTE but conviction stays measured, and vol-of-vol at Normal argues the same.
Trade the regime, not the headline: Iron Condor as the vehicle, sizing Standard Size, cross-asset tone Aligned. Reclaim of the flip or a VVIX extension are the two signals that break the base case - until then, assume the chop persists.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - plan a multi-day short-vol book at 30-45 DTE, not a one-day reaction. Panic transition probability stays low at 0.05, but mean-reversion to calm isn't the base case either.
Trading readVIX up, VVIX up, SKEW flat, MOVE down - equity-local stress not confirmed by rates, which argues against a compounding credit event and supports the mean-reversion setup over 5-15 sessions.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure holds Contango with near-slope at 15.95% - the carry trade still gets paid despite today's spot VIX bid. VIX9D at 14.55 prints well below VIX at 16.87, VIX3M at 18.81, and VIX6M at 20.49 - a clean monotonic curve says the tape is pricing today as a transient shock, not a regime break.
Front-month basis at 11.5% leaves vol sellers' edge intact. Forward 30-60 implied at 19.7085184628 steps into 60-90 at 22.042325195 - a monotonic rise with no event-premium hump, so no discrete catalyst is being priced into the back. Regime reads Steep contango - vol sellers favored, signal Green.
The 30-45 DTE pocket is where the slope compensates best for gamma risk - short enough to harvest the roll, long enough to breathe past the dealer-amplified open. Favor the belly, not the wings.
What it means for your trading
Clean Contango survives today's spot bid - the market is paying for today, not for a regime shift, which keeps the 30-45 DTE carry trade live into tomorrow.
Trading readClean contango end-to-end with VIX9D cheapest and VIX6M richest - the market treats today as a shock, not a regime. Vol sellers' carry edge survives the session.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV prints 11.66% against HV20 at 10.29 and HV60 at 10.97 - options are still bid above what the tape has actually delivered, with VRP holding 1.37%. The premium is intact but compressed: carry is paid, just not fat enough to justify leaning in.
The realized structure tells the quieter story - HV20 at 10.29 sits below HV60 at 10.97, meaning the tape is still decelerating even as the dealer regime flipped to Negative Gamma. No confirmation yet of the amplified panic the gamma mechanics warn about. That gap is the trade and the risk in one measurement.
Watch tomorrow's cash open: if realized finally catches up to the implied bid, VRP compresses fast and the short-vol carry evaporates into the move. Short-vol structures still favored at 30-45 DTE, but reduce aggression - the premium is thinner than it looks.
What it means for your trading
Options still richer than realized at VRP 1.37%, but HV20 10.29 below HV60 10.97 means the tape hasn't yet validated the dealer-amplification warning - carry pays until realized catches up, which is the single risk that collapses the trade.
Skew Convexity
Put wing is bid without being broken: 16.07% on the quarter-delta put against 15.17% at the money and 14.58% on the quarter-delta call. That ladder - puts over ATM over calls - is the orderly protection bid, not the kinked panic buy you get when a tail is actually being chased.
Skew of 1.49% alongside a smile ratio of 1.1% keeps the surface on-trend rather than warped - ordered steepening. The call wing is flat: no one is paying up for upside convexity, which tells you the tape has no reclaim conviction into tomorrow's open. Section reads Yellow, labelled Skew Steep.
Structurally: pay for the convexity, don't buy the full tail. Put spreads capture the richer 16.07% leg against the cheaper body without overpaying for a crash that isn't being priced. Selling naked calls into unloved upside looks tempting but hostile vanna below the flip at 774.65 keeps that trade honest - stick with defined-risk.
What it means for your trading
Skew is steep but ordered - put bid at 16.07% over ATM 15.17% with smile ratio 1.1% says protection, not panic. Prefer put spreads over naked puts and skip the flat call wing.
Vol-of-Vol Structure
VVIX printed 94.71 against VIX at 16.89, pushing the VVIX/VIX ratio to 5.61 - a Normal reading. The tape is quietly bidding jump risk even while spot VIX stays contained, and that gap is the tell: dealers are paying for optionality on the vol surface itself, not just on direction.
With VVIX up 10.93%% against VIX up 10.61%%, convexity on vol is where the premium is flowing. Section signal reads Green, which keeps sizing at Standard Size - not a day to lean harder into short-vol structures with a jump-prone tape underneath.
Contango holds and the carry still clears, but tail hedges earn their keep here. A VVIX bid alongside Contango is the market admitting the next shock could be reflexive, and that's the risk short-vol books have to pay for.
What it means for your trading
VVIX/VIX at 5.61 (Normal) keeps sizing at Standard Size - carry still pays, but tail hedges remain cheap insurance into a jump-prone surface.
Dispersion Spread
Index ATM IV at 11.66% against QQQ at 19.25% and IWM at 17.18% - a meaningful spread with small-caps paying up most. The ordering is clean: 17.18% > 19.25% > 11.66%, and the small-cap premium is doing real work in a tape where mega-cap gamma pockets dampen the index while the broad complex sits in negative-gamma amplification.
IWM VRP at 4.45% is the richest in the complex - the carry trade pays most where single-name dispersion can't lean on mega-cap stabilization. Index-level iron condors preferred to single-name strangles: idiosyncratic names don't benefit from the dampening that keeps SPY corralled inside the 765.00/800.00 corridor, and the Moderate dispersion signal says the spread is wide enough to route but not so wide you can press.
What it means for your trading
Small-cap premium with IWM VRP at 4.45% routes the carry trade into IWM iron condors over single-name strangles; dispersion signal Yellow - index-level vol selling preferred in a negative-gamma regime.
Liquidity & Microstructure
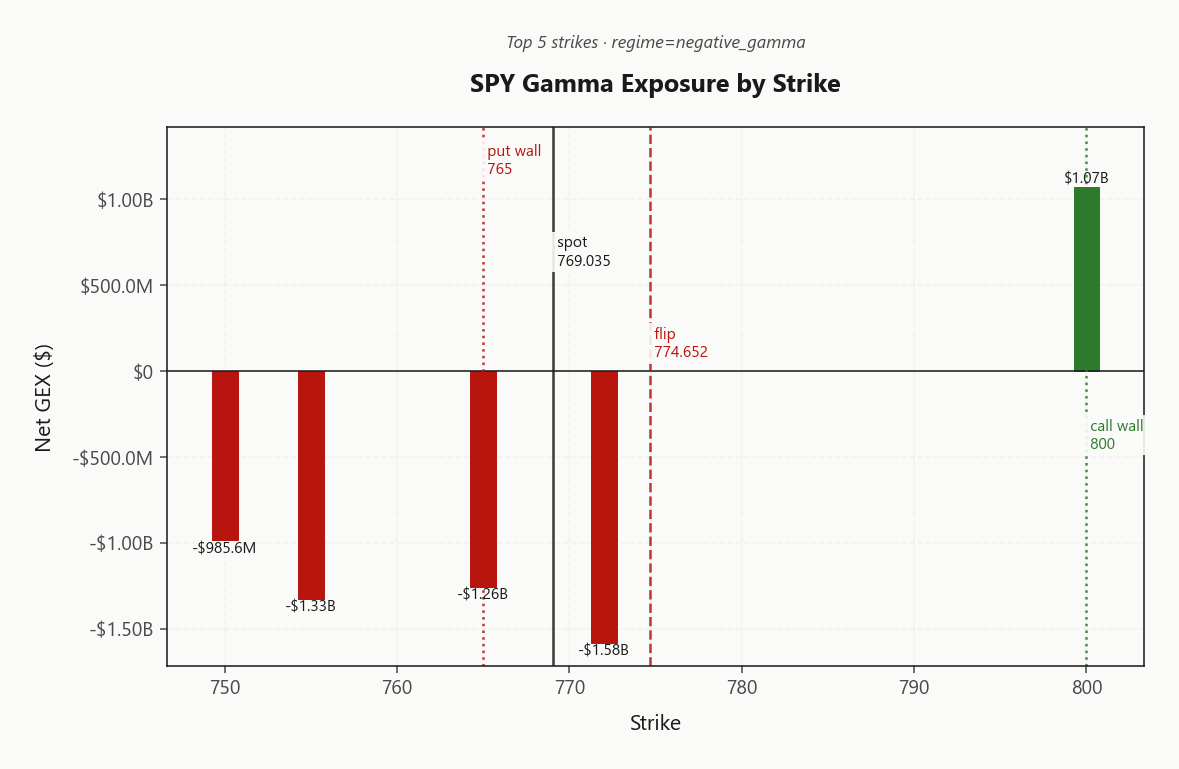
The structural anchor remains the deep OI cluster at 500, but that strike is noise for tomorrow's tape - the live corridor runs between the put wall at 765.00 and the call wall at 800.00, framed by the gamma flip at 774.65. Spot 769.04 sits below flip, which puts dealers squarely in the amplification regime: hedging flows accelerate directional moves rather than dampen them.
The single heaviest tape-pressure point is the 772.00 strike, carrying net GEX of -$1.58B against total OI of 95339 - that is where dealer delta re-hedging bites hardest on any push. Max pain at 767.00 is the overnight magnet, and spot pinned right there into the close is coincidence, not stability.
Trade the corridor, respect the walls, and treat a reclaim of 774.65 as the only clean regime-flip trigger.
What it means for your trading
SPY below the flip at 774.65 with the heaviest net GEX concentrated at 772.00 means dealer flow amplifies both directions inside the 765.00/800.00 corridor - fade the walls, don't chase breaks until flip reclaims.
Trading readNegative gamma stacked below spot with the call wall at 800.00 capping upside - dealers amplify in both directions until price reclaims the flip at 774.65. Trade the corridor, don't fight the mechanics.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer Greeks tell the hostile story the tape has been dancing around all session. Net VEX prints -$59.91B - a vanna configuration that accelerates on a vol spike rather than absorbs it. Any VVIX extension from here forces incremental delta selling through the dealer book, not buying. That is the mechanical reason the complex traded heavy into the bell despite spot pinning max pain.
Charm reinforces the pressure. Net CHEX at -$2.2M with the book's own read as 'Time decay pushing dealers to sell - pressure into close' explains the late-session fade - time decay was literally dragging dealers short through the close. Overnight that charm bleed resets, but the vanna leverage stays live into tomorrow's open print.
Pivot sits at 767 (Max Pain), spot drifting -0.2646173451% away - bias reads Neutral, signal Yellow. Trade the corridor, not the breakout; let dealers tip their hand on the reclaim of 774.65.
What it means for your trading
Hostile vanna with charm draining dealers short - any VVIX push from 94.71 compounds the selling, so size stays Standard Size and the pivot at 767 is the overnight magnet to respect.
Cross-Asset Confirmation
Rates aren't confirming the equity stress. MOVE printed 98.98, down-2.09%% on the session - a credit-event tape would have MOVE bid alongside VVIX, and it didn't happen. That asymmetry is the single most important cross-asset tell: today's dealer-amplification regime is equity-local, not a compounding macro break.
Across the index complex, SPY 769.04, QQQ 727.88, and IWM 271.07 all settled below their respective gamma flips - regime divergence reads Aligned with cross-asset tone Unknown. No index is leading the complex out; none is cracking harder than the others. Alignment under flip means the amplification mechanics are complex-wide, but the stress is contained to equities.
Fear & Greed at 32 (Fear) is the sentiment confirm - real, not extreme. Isolated-event bias holds: mean-reversion edge survives so long as credit stays quiet and MOVE doesn't catch up.
What it means for your trading
MOVE down while VVIX bid tells you this is an equity-mechanics event, not a credit break - fade the panic in 30-45 DTE if rates stay orderly, but the first MOVE spike invalidates the mean-reversion thesis.
Scenario EV
The scorecard lands on Iron Condor at 39, clearing the put-spread alternative at 26 - the vehicle wins because the richer small-cap VRP pays for the wider walls a two-sided structure demands below the flip. IWM VRP 4.45% against SPY VRP 1.37% is the routing tell: carry concentrates in the Russell, not the S&P, and the iron condor is the only structure that monetises the full premium stack rather than one wing of it.
DTE sweet spot sits at 30-45 - far enough out to let charm and vanna work for you rather than against, close enough to keep theta meaningful. Set the short strikes outside the SPY 765.00/800.00 corridor and, where you route the trade, outside the IWM 270.00/290.00 corridor. The walls are the dealer's line in the sand; the condor's job is to collect while price respects them.
Sizing stays Standard Size. VVIX bid at 94.71 plus hostile vanna at -$59.91B means a vol-of-vol expansion ruins an oversized short-premium book overnight. Collect the carry, respect the mechanics, don't press.
What it means for your trading
Route the Iron Condor in IWM at 30-45 DTE with strikes outside the 270.00/290.00 corridor - the richer VRP wins the scorecard, but Standard Size is non-negotiable while VVIX stays bid.
Actionable Summary
Bottom line: deploy Iron Condor in the 30-45 DTE pocket, strikes outside the 765.00/800.00 corridor, and route IWM for the richer 4.45% print. Score of 39 beats the put-spread alternative at 26 - the carry edge is in the condor, not the directional. Sizing stays Standard Size; VVIX at 94.71 says jump risk is bid, so this is not a day to press.
Avoid: naked short vol, chasing the breakdown below 774.65, and selling tails into hostile vanna - net VEX at -$59.91B turns any vol spike into forced dealer selling. Watch: a reclaim of 774.65 flips the amplification regime back to dampening and is tomorrow's lead trigger; 767 acts as the overnight magnet; if VVIX extends from 94.71, cut size further.
Regime:Elevated / Watchful with half-life of 15 sessions - sticky, plan multi-day, not one-and-done.
What it means for your trading
Carry trade stays in the 30-45 DTE condor with IWM routing; the actionable triggers are a 774.65 reclaim for regime flip and 94.71 extension for size cut.
AI infrastructure selloff is the sector story behind today's close - if NVDA/AVGO/AMD lead down tomorrow, QQQ gamma flip becomes the next line in the sand.
Houthi strikes on Saudi oil infrastructure keep the energy tail bid - relevant for cross-asset confirmation and the mean-reversion vs. compounding distinction.
CPI hot print + Morgan Stanley equities beat frames the day: macro stress with institutional flows still functional - supports the isolated-event thesis.
Aramco HQ attack extensive damage report - raises the probability that today's geopolitical premium sticks rather than fades overnight.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.85 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 774.65 against a spot of 769.04. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.66% with a volatility risk premium of 1.37%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.89. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime