Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY sits glued to its put wall at 777.00 with dealers long gamma into 780.00, while QQQ has slipped beneath its 746.74 flip into Negative Gamma territory - the first clean regime split of the week. Steep contango - vol sellers favored on the VIX curve plus Low VVIX (5.64x) argue for carry, but the QQQ dislocation says sell premium on SPY, not QQQ. Watch 777 - a break releases the pin and hands tape control to QQQ dealer selling.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
778.41
-
-
780
777
766
$5.14B
-
QQQ
743.16
746.74
-0.48%
750
740
730
-$2.89B
Short gamma
IWM
278.62
285.95
-2.56%
280
275
284
-$4.06B
-
VIX
15.18
15.17
+0.07%
20
15
19
$7.26M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.36
9.77
-0.41
1.82
2.31
0.95
QQQ
15.34
15.24
+0.10
1.97
1.49
0.82
IWM
15.82
11.42
+4.40
1.42
2.25
0.56
VIX
105.95
77.95
+28.00
-109.76
0.33
0.03
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
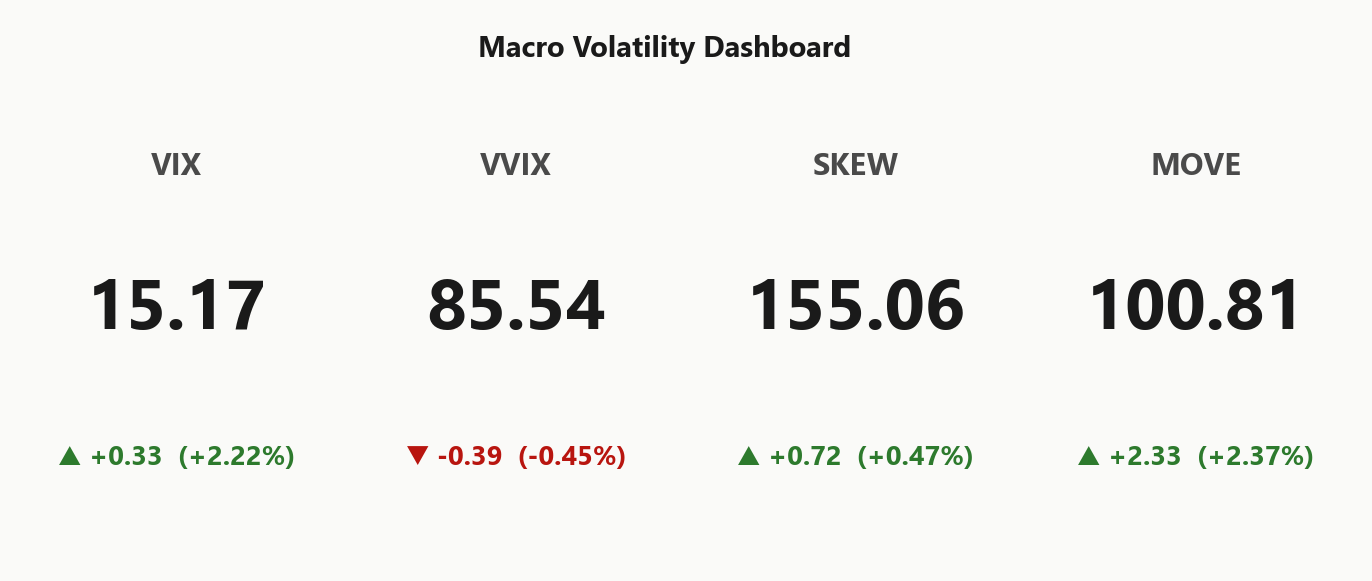
VIX
15.17
+2.22%
VVIX
85.54
-0.45%
SPX
7,811.01
+0.05%
SKEW index
155.06
+0.47%
MOVE (bond vol)
100.81
+2.37%
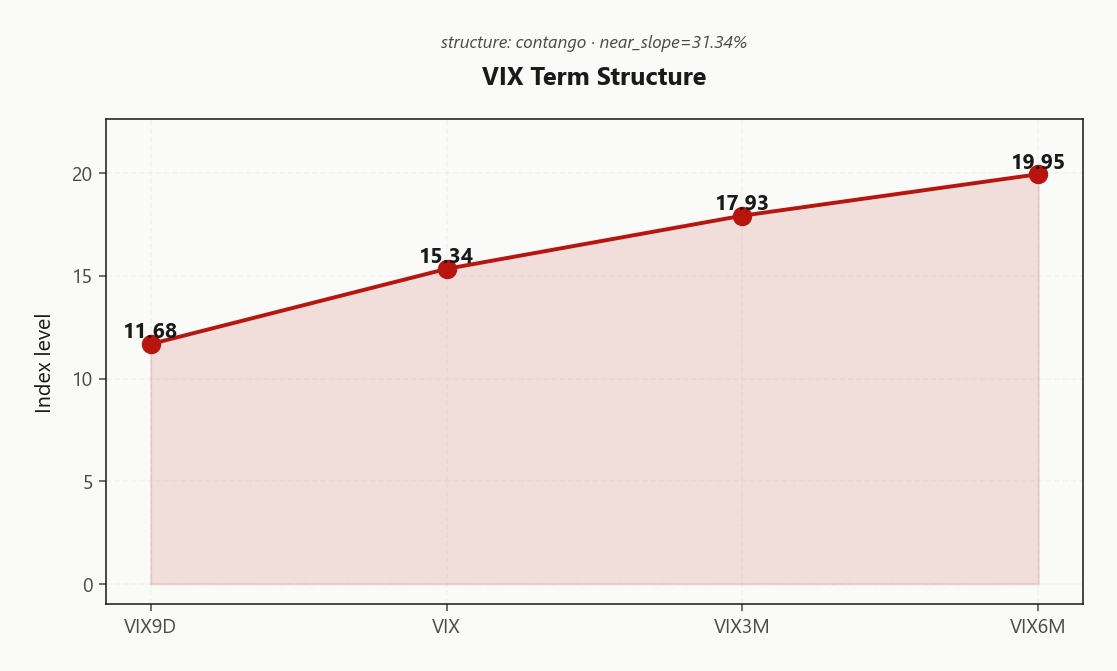
VIX term (9d/30d/3m/6m)
11.68 / 15.34 / 17.93 / 19.95
Steep contango
VVIX / VIX
5.64
Low
Regime
Elevated / Watchful
Regime Assessment
The tape is parked in Elevated territory - Elevated / Watchful with VIX printing 15.17. Not panic, not complacency, and crucially sticky: half-life clocks at 15 sessions, meaning the current vol surface is the one you trade against for the next two-plus weeks absent a shock.
Transition math backs the posture. Probability of a jump to panic over the next five sessions sits at 0.05 - effectively tail-only - while mean-reversion to a low-vol regime over ten sessions runs 0.45. The distribution is skewed toward decay, not acceleration, which is why Steep contango - vol sellers favored on the VIX curve and Low VVIX are consistent with the regime label rather than fighting it.
Operationally: carry is paid, sizing stays Standard Size, and the regime's slow decay argues against chasing hedges at these levels. The watch is the 777 pivot - a breach is the only clean path from watchful to panic inside the five-session window.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - trade the surface, don't fight it, until the 777 pivot breaks.
Trading readVIX elevated, VVIX low, SKEW high, MOVE creeping - classic ambient-tail-risk setup where the market expects slow drift with occasional shocks, not acute panic. Divergences aren't flashing yet.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve sits in Steep Contango with VIX9D at 11.68 trading well under spot VIX at 15.34 - near-dated contango is deepening, not flattening. The back end confirms: VIX3M 17.93 and VIX6M 19.95 hold persistent event premium, pricing the market's willingness to pay up for 30-to-90-day protection while shrugging off next-week risk.
Forward implieds carry the message cleanly: 30-to-60 at 19.0937044598 rolls into 60-to-90 at 21.7834822744, carry structure intact and term Contango across every tenor that matters. Signal Steep Contango - short premium carry is the structural tailwind, long vol fights the curve.
Edge sits in the 21-30 DTE belly where roll-down is steepest and event cover isn't yet being bid. Sell the belly, don't chase the back.
What it means for your trading
VIX curve in Steep Contango with VIX9D 11.68 under VIX 15.34 - short-premium carry is paid, and the 21-30 DTE belly is the vehicle. Signal Steep Contango.
Trading readDeep contango with VIX9D 11.68 well under VIX3M 17.93 - vol carry trade is paid, calendar structure favors selling the belly.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
The realized-vol tape splits the complex cleanly. SPY ATM IV at 9.36% trades under HV20 of 9.77, printing a VRP of -0.41% - options cheap to realized, no cushion for anyone short premium. QQQ sits near flat at 0.1% with HV60 at 17.83 above HV20 15.24: realized is decelerating but hasn't paid up yet.
IWM is the standout. VRP at 4.4% with HV20 11.42 well below ATM IV 15.82% - the richest premium in the complex and the only clean short-vol surface. Signal reads Vrp Active: carry is paid in small-caps, not large.
Trade the spread, not the index. Short premium routes to IWM; SPY is a trap on this VRP print and QQQ offers no edge until realized rolls down. The cross-asset VRP dispersion is the setup.
What it means for your trading
IWM carries the richest VRP in the complex at 4.4% while SPY VRP of -0.41% leaves short vol unfunded - route premium selling to IWM, avoid SPY.
Skew Convexity
SPY quarter-delta skew prints 1.82% with the smile ratio at 1.16% - downside is paying up, but the bid is orderly. Put-25d IV 13.25% trades above ATM 12.31% and the call wing at 11.43%, a clean ordered stack rather than a convex panic grab.
The SKEW print at 155.06 (0.47%% change) says the left tail is ambient, not hoarded - consistent with VVIX 85.54 sitting in Low regime and the Steep Contango VIX curve. No binary premium being paid; the wing is a slope trade, not a convexity trade.
Signal reads Skew Steep: finance downside via put spreads, not naked puts - the far strike is cheap enough to cheapen the hedge without surrendering the carry thesis in the 21-30 DTE belly.
What it means for your trading
Skew is steep but orderly - put bid without panic convexity, SKEW 155.06 confirms tail risk is ambient. Hedge via put spreads, not naked puts.
Vol-of-Vol Structure
VVIX prints 85.54 against VIX 15.17, dropping the ratio to 5.64x - squarely in Low territory. No jump premium is being bid, no binary is being hedged, and the second-order surface is quiet while the first-order tape works its range.
Vol-of-vol compression this clean removes the usual tax on short premium. VVIX moved -0.45% on the session with no reflex spike into the close - dealers aren't paying up for convexity, and the gamma-of-gamma surface stays flat. Sizing guidance reads Standard Size: no need to half-size, no need to layer tail hedges against the short-vol book.
Signal flags Low. Translate directly: full clip on IWM premium at 21-30 DTE, no VVIX-driven haircut, and the carry stays paid as long as this ratio holds.
What it means for your trading
VVIX at 85.54 with ratio 5.64x clears short-vol sizing to Standard Size - no jump premium, no reason to shrink the book.
Dispersion Spread
Dispersion is the trade. IWM ATM IV 15.82% prints flush with QQQ at 15.34% while SPY sits at 9.36% - small-caps paying full tech-grade premium on a book that doesn't carry tech-grade realized. IWM HV20 11.42 underwrites the richness; the premium is there to be harvested.
QQQ's elevated IV is earned - negative-gamma regime below flip at 746.74 keeps correlation bid and idiosyncratic risk live. Short premium there fights the dealer flow. SPY compressed at 9.36% offers no dispersion edge either way, with VRP -0.41% already negative - options are cheap to realized, no cushion to sell.
Signal reads Moderate: route index-premium capture to IWM, not SPY, and keep QQQ as the hedge leg, not the short-vol vehicle. The split regime makes the cross-asset VRP spread the cleanest expression on the board.
What it means for your trading
IWM pays tech-level IV on sub-tech realized while QQQ's premium is defended by Negative Gamma and SPY offers no edge - sell IWM, hedge via QQQ, leave SPY alone.
Liquidity & Microstructure
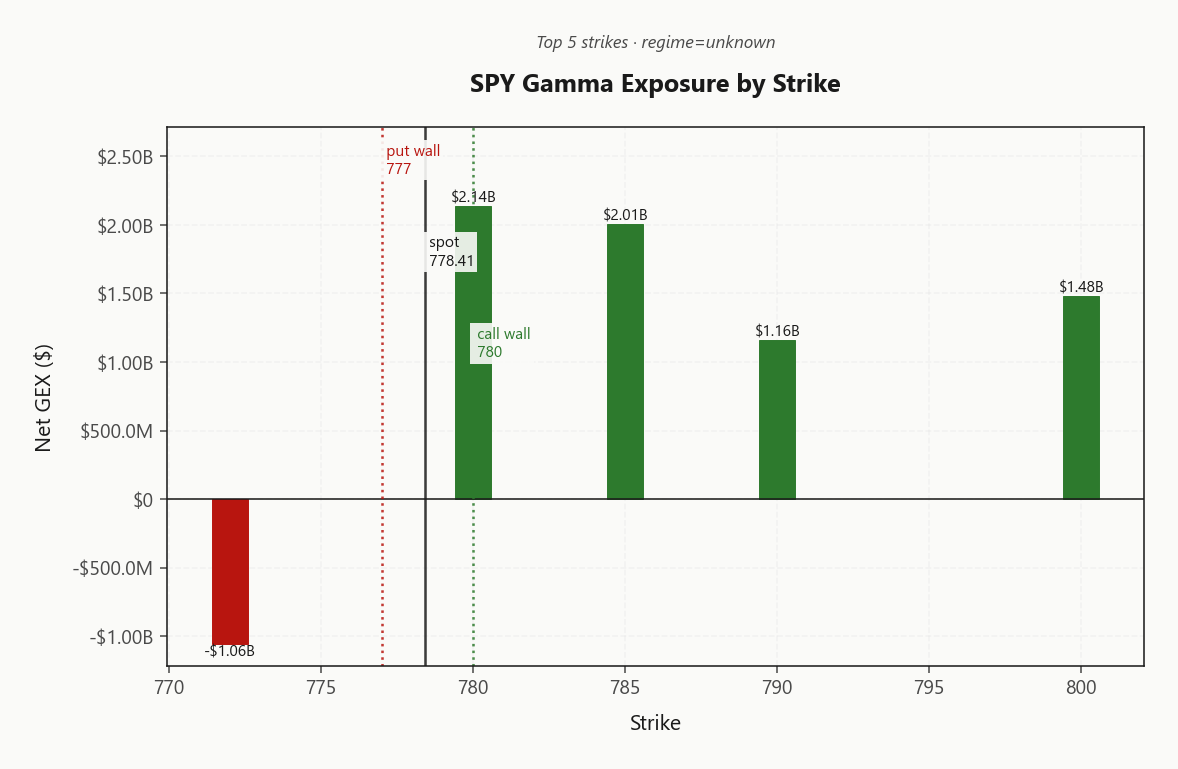
SPY's book anchors at 780.00, where $2.14B of dealer gamma pins the tape. Spot at 778.41 sits inside the operative corridor between the 777.00 put wall and 780.00 call wall - dealers dampen moves inside, amplify outside. Highest OI stack at 500 is longer-dated ballast, but the near-term flow is written at the walls.
Zero-DTE represents 44.5%% of total GEX - nearly half of today's gamma reprices by the bell. That composition is the intraday mean-reversion fuel: chop between walls dominates until charm pressure takes over into the pin. Signal reads Deep.
Playbook: fade the walls, work the chop. Short premium belongs in 21-30 DTE on IWM where VRP pays; SPY corridor trades mechanically until 777 breaks.
What it means for your trading
Dealer book is deep and pin-prone with spot wedged between 777.00 and 780.00; fade the walls into the 780.00 anchor while 44.5%% 0DTE share keeps intraday mean-reversion live.
Trading readSPY's gamma stack between 777.00 and 780.00 tells today's story: dealers dampen inside that corridor and amplify outside. The 780.00 anchor is where mean-reversion is strongest.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY net VEX at -$157.97B leaves dealers structurally hostile to any vol spike - a tick higher in IV flips the hedge from damping to selling, and CHEX at -$3.1M compounds the problem into the close as charm pressure drains delta from long positioning. The corridor holds for now, but the second-order Greeks are not confirming the first-order calm.
The tripwire is the charm pivot at 777, a Put Wall with current bias Neutral. Hold it and the pin anchors into settlement; lose it and SPY dealer flow releases while QQQ dealer selling takes the tape. Section signal: Neutral.
What it means for your trading
Vanna is hostile and charm skews negative into the close - the corridor is intact only while spot holds 777. Break the pivot and QQQ's Negative Gamma regime dictates the tape.
Cross-Asset Confirmation
Rates vol is creeping, not screaming: MOVE at 100.81 (2.37%% change) keeps the cross-asset tape honest without forcing a bid in equity convexity. Fear and Greed sits at 46 (Neutral) - no complacency to fade, no panic to buy. The macro backdrop is ambient, which is exactly the regime where structural dealer flow dominates headline flow.
Underneath, the index complex is not confirming itself. SPY at 778.41 holds its corridor, QQQ at 743.16 trades below flip in Negative Gamma, and IWM at 278.62 hangs in open air. SPY/QQQ regime divergence reads True - the lead fragility signal into the close.
Signal: Aligned. The macro gauges don't contradict the gamma book, but the intra-index split is the tell - tech leads any break, SPY lags, IWM is where premium gets paid.
What it means for your trading
MOVE at 100.81 and F&G 46 say macro is quiet, but SPY/QQQ regime divergence (True) is the fragility fingerprint - tape control sits with QQQ dealer flow, not the SPY corridor.
Scenario EV
Scenario EV routes to Unknown in 21-30 DTE - the belly where Steep Contango on the VIX curve pays carry without stretching into event-premium territory. VRP assessment prints Unknown, and with VVIX at 85.54 (Low regime, ratio 5.64x) there is no jump premium bid - sizing guidance stays Standard Size, not defensive.
Vehicle selection is unambiguous: IWM for VRP capture. IWM VRP 4.4% is the richest surface in the complex, ATM IV 15.82% on HV20 11.42 - options paying index-grade premium on half the realized. Avoid SPY short premium: VRP -0.41% means options are cheap to realized, so you bleed the carry fight. Hedge long tails with QQQ puts given Negative Gamma below 746.74.
Tripwire is the 777 charm pivot - a break releases the SPY pin and QQQ accelerates; standard-size until it holds, cut on break.
What it means for your trading
Sell IWM Unknown in 21-30 DTE at Standard Size; avoid SPY premium and hedge tails via QQQ puts, with 777 as the cut-level.
Actionable Summary
Bottom line: sell Unknown structures on IWM in 21-30 DTE - richest VRP in the complex at 4.4% against SPY's -0.41%, where options trade cheap to realized and short premium bleeds carry. VVIX at 85.54 (Low regime, 5.64x) supports Standard Size - no need to half-size.
Watch the charm pivot at 777 (Put Wall); spot sits -0.1811384746% away with Neutral bias - a break releases the SPY pin and hands tape control to QQQ dealer selling below the 746.74 flip. Hedge tails with QQQ puts: Negative Gamma territory offers no dealer cushion into a tech-led shock.
Regime read: Elevated / Watchful, half-life 15 sessions - sticky, slow decay. Route premium to IWM, respect the SPY corridor between 777.00 and 780.00, avoid shorting SPY vol.
What it means for your trading
IWM Unknown in 21-30 DTE is the trade; 777 is the tripwire that flips the regime from pinned to directional. SPY premium is a trap, QQQ puts are the hedge.
Paul Tudor Jones flagging buyback/M&A exhaustion as a 2027 risk sets the macro overhang context for why dealers aren't pricing a complacency regime despite low VIX
Chip rout plus Goldman/Wells earnings beats underscores the SPY/QQQ regime split - financial strength vs semi weakness drives the index divergence we're seeing in gamma
Iran reportedly fortifying nuclear sites ahead of potential midterm-era strikes - material for anyone sizing long tail hedges on QQQ or OTM puts on SPY
IMF flagging AI investment propping global growth while war/debt threaten outlook - exactly the bimodal macro setup that keeps VIX3M bid against spot VIX
Oil easing despite Saudi airport attacks shows the market is willing to shrug off geopolitical tape bombs - reinforces the vol-sellers-win regime
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.18 with a Contango term structure. The Fear & Greed index reads Neutral, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $5.14B. The gamma flip sits at N/A, with the call wall at 780.00 and the put wall at 777.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 778.41. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.36% with a volatility risk premium of -0.41%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.17. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime