Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 777.34 with net GEX $2.09B sits right on the charm pivot at put wall 777.00; call wall sits one dollar above at 780.00, so the tape is boxed in a dollar-wide pin zone. QQQ at 743.17 is negative gamma with net GEX -$3.32B below flip at 746.74, and IWM at 276.30 is deep negative at -$5.35B below flip 284.18 - both will trend if they break their respective put walls. Dealers in QQQ and IWM are short gamma with vanna hostile (Vol up = dealers sell delta - downside amplified if vol spikes), so a VIX spike from 15.45 would accelerate downside outside of SPY's pin. Term structure is Steep contango - vol sellers favored with VIX9D 12.16 well under VIX3M 18.03 - carry is intact for vol sellers. VRP read is clean: IWM VRP 5.4% is extremely rich vs HV20 11.16, SPY VRP 0.22% is tight. Bottom line: fade premium in IWM into 275.00 / 280.00, respect the SPY pin at 777.00, and avoid naked exposure in QQQ below 746.74 where dealer flow amplifies.
Index complex split: SPY pinned at put wall, QQQ/IWM negative gamma below flip at 15.45
SPY is pinned right at its put wall 777.00 with net GEX $2.09B straddling zero, while QQQ and IWM sit in negative gamma territory below their flips at 746.74 and 284.18. VIX term structure in steep contango at Steep contango - vol sellers favored and VVIX at 86.43 say vol sellers still have carry, but the regime divergence means index hedges are not interchangeable. Fear & Greed at 43 reads fear while contango persists - the market is nervous but not panicked.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
777.34
-
-
780
777
766
$2.09B
-
QQQ
743.17
746.74
-0.48%
750
740
730
-$3.32B
Short gamma
IWM
276.30
284.18
-2.78%
280
275
284
-$5.35B
Short gamma
VIX
15.45
15.57
-0.74%
20
15
19
-$26.61M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.80
9.58
+0.22
1.68
2.31
1.11
QQQ
15.92
15.15
+0.77
2.50
1.49
1.00
IWM
16.56
11.16
+5.40
0.51
2.25
1.05
VIX
108.17
78.08
+30.09
-102.59
0.33
0.24
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
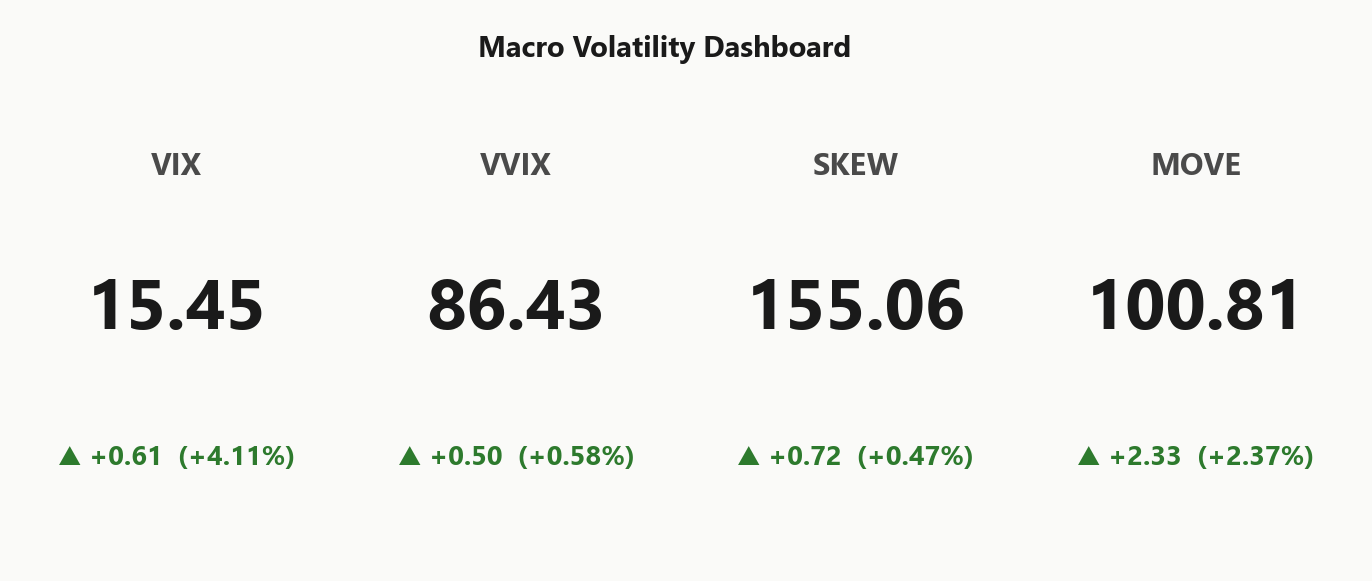
15.45
+4.11%
VVIX
86.43
+0.58%
SPX
7,800.41
-0.09%
SKEW index
155.06
+0.47%
MOVE (bond vol)
100.81
+2.37%
VIX term (9d/30d/3m/6m)
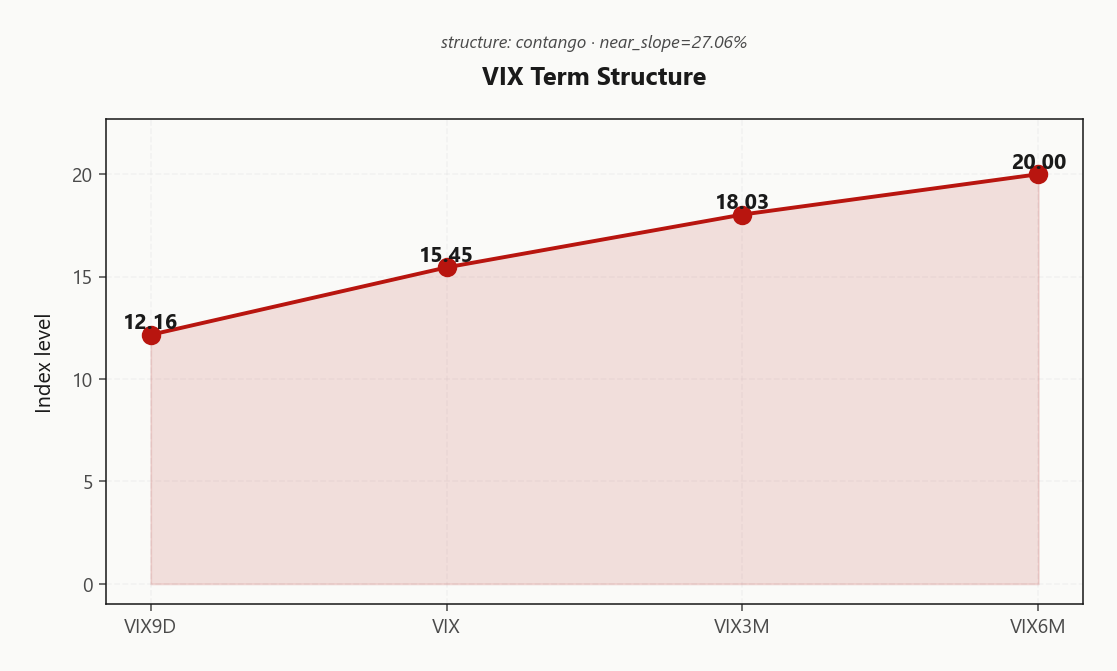
12.16 / 15.45 / 18.03 / 20.00
Steep contango
VVIX / VIX
5.59
Low
Regime
Elevated / Watchful
Regime Assessment
Regime stamps Elevated / Watchful with VIX at 15.45 - not panic, not complacency, the awkward middle where carry still pays but tail hedges earn their keep. Transition matrix puts probability of escalation to panic over five sessions at 0.05, so convex downside is priced reasonably rather than richly bid. Half-life clocks 15 sessions - this state is sticky, expect it to persist through the week rather than resolve overnight.
Mean-reversion to low regime over ten sessions sits at 0.45, a coin-flip-light that argues against aggressive vol-selling sizing even with contango at Steep contango - vol sellers favored. The fingerprint distinguishing elevated from low is MOVE at 100.81 up 2.37%% - bond vol leads, equity vol follows, and until MOVE recompresses the regime stays watchful.
Trade the regime, not the forecast: standard-size short vol with contango carry, keep tail hedges on at these prices, and watch MOVE as the leading tell for a regime step-up.
What it means for your trading
Elevated/Watchful regime with low near-term panic probability and sticky half-life - persist through the week, carry the contango, keep tails on because MOVE elevation says the fingerprint of risk has not faded.
Trading readVIX 15.45 up 4.11%% while VVIX 86.43 is contained and MOVE 100.81 elevated - bonds are leading equity in pricing risk, a divergence worth tracking.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is in Contango with VIX9D at 12.16 sitting well under spot VIX 15.45 and the belly at 18.03. Near slope at 27.06%% is paying vol sellers to be short the front, and the front-month futures basis at 16.7%% confirms the carry trade is live.
Best structural edge is the 21-30 DTE window - far enough to monetize the roll-down from VIX3M 18.03 toward VIX9D 12.16, close enough to avoid the VIX6M 20.00 anchor pulling against the trade.
What it means for your trading
Textbook Contango with VIX9D 12.16 well under VIX3M 18.03 hands vol sellers paid carry in the 21-30 DTE belly. Collapse risk if realized breaks higher - the Steep Contango regime is the whole trade.
Trading readSpot-to-front-month basis 16.7%% in contango - carry trade is live and paid, but a VIX spike would collapse the slope quickly.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
The VRP tape is bifurcated and the routing writes itself. SPY ATM IV sits at 9.8% against RV20 of 9.58 and RV5 of 6.17, leaving VRP compressed at 0.22% - the Thin Premium read. SPX options are near fair; naked short vol here pays for the ticket and little else.
IWM is the other side of the ledger. ATM IV at 16.56% against HV20 of just 11.16 prints a VRP of 5.4% - small caps are paying up for protection the tape has refused to deliver. QQQ threads the middle with VRP 0.77%, a modest premium that doesn't justify naked exposure given the negative-gamma backdrop below flip at 746.74.
Routing is clean: sell IWM premium into the walls at 275.00/280.00, avoid SPY naked short vol where edge is thin, and respect QQQ's regime rather than reach for the middling carry.
What it means for your trading
IWM VRP at 5.4% versus HV20 11.16 is the asymmetric vol-sell of the complex; SPY's 0.22% offers no edge for naked structures.
Skew Convexity
The 25-delta skew sits orderly across the complex rather than panic-steep. SPY prints a quarter-delta skew of 1.68% with the put wing at 13.69% against ATM 12.93% and the call wing at 12.01% - a modest downside premium, not a convex bid.
QQQ skew at 2.5% echoes the same posture, while IWM runs nearly flat at 0.51% despite sitting in negative-gamma territory below flip 284.18. That is the curious disconnect: the symbol with the most hostile dealer book is paying the least for crash protection.
Smile ratios cluster near 1.14%, so wings are priced ordered. Preference: defined-risk put spreads over naked puts - long gamma on the tail is cheap in relative terms but the convex payoff is not being subsidized.
What it means for your trading
Skew is orderly, not panic-bid, with IWM flat at 0.51% under a negative-gamma regime - a mispricing worth owning via put spreads rather than naked downside.
Vol-of-Vol Structure
VVIX at 86.43 against VIX 15.45 prints a ratio of 5.59 - squarely in the Low regime. The jump component of vol is not being bid: the market is pricing a continuation of the current distribution, not a bimodal tail. No premium is going into convex vol-of-vol structures, and that is the single clearest tell that the next week does not carry an event-shaped risk premium in options.
Translation to sizing: Standard Size on short-vol expressions. With VVIX contained, the gamma on short-premium books stays well-behaved - a VIX tick higher does not compound into a VVIX blow-off, which is the usual landmine for condor and strangle sellers. The carry is paid cleanly here, not stolen back by vega-of-vol.
The watch item is second-derivative: VVIX re-accelerating off this base - even with VIX quiet - is the leading tell for a regime break. Front-run that by trimming short-vol exposure if VVIX pushes materially off 86.43 while the ratio climbs; do not wait for VIX to confirm.
What it means for your trading
VVIX at 86.43 and a ratio of 5.59 keep the tape in a Low vol-of-vol regime, which supports Standard Size on short-premium structures. Any upward kink in VVIX from here - independent of VIX - is the earliest signal the regime is breaking.
Dispersion Spread
Dispersion is running moderate with the complex bifurcated at the single-name level. Top absolute GEX changes concentrate in mega-cap tech - MSFT, META, AAPL, NVDA - all building positive dealer gamma while the small-cap tape lags. Index-level vol is being driven by a narrow cohort, which means SPY/QQQ realized will under-deliver vs single-name realized if the mega-caps keep carrying the tape.
The cross-sectional vol stack confirms the dispersion: SPY ATM IV 9.8% sits well under QQQ 15.92% and IWM 16.56%, with IWM paying up despite small caps delivering nothing on realized. Cross-expiry dispersion at 3.19 and cross-strike at 82.36 frame the surface - small-cap premium is richly priced relative to large-cap, while mega-cap single-name gamma builds mask fragility underneath.
Routing: short dispersion by selling IWM or QQQ premium against the rich implied, and lean long mega-cap single names selectively where dealer long-gamma builds support drift. Avoid naked index hedges - they will under-perform if the mega-cap cohort continues to dominate the tape.
What it means for your trading
Mega-cap tech is carrying index gamma while small caps lag - sell IWM/QQQ premium at 16.56%/15.92% and lean long selective mega-cap names where dealer positioning supports drift. Index hedges under-perform in this regime.
Liquidity & Microstructure
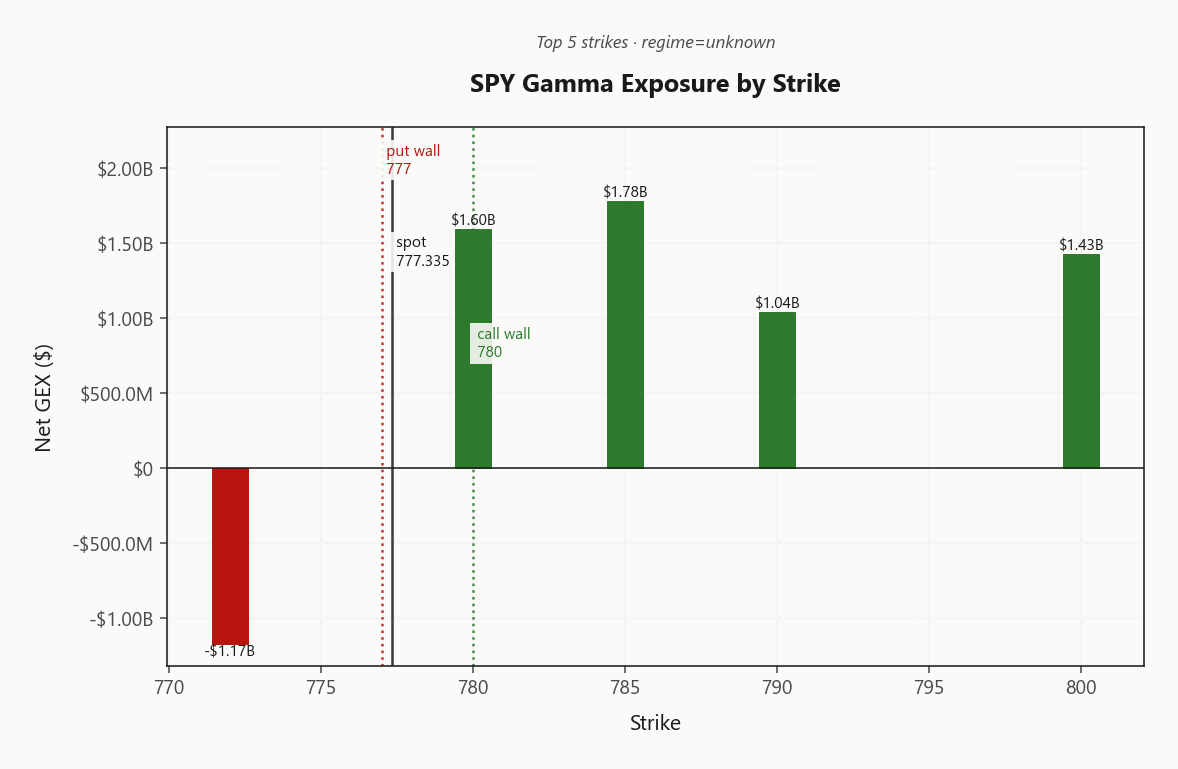
SPY's open interest stacks a near-spot magnet at 785.00 carrying $1.78B of positive GEX, with the deep legacy anchor sitting way below at 500. Spot pins on the put wall at 777.00 with the call wall one dollar above at 780.00 - a one-dollar pin band where dealer buying on dips meets selling into strength.
0DTE delivers 45.5% of total SPY GEX, reinforcing the intraday pin and compressing realized within the walls. Breaks of either edge are the day's structural tripwires.
Outside SPY, the microstructure flips hostile: QQQ sits below gamma flip at 746.74, where dealer flow amplifies directional moves, and IWM's flip at 284.18 is the small-cap trigger. Index hedges are not interchangeable - the pin lives in SPY, the convexity lives below the flips.
What it means for your trading
SPY is boxed in a one-dollar pin band between 777.00 and 780.00 with 0DTE flow reinforcing the magnet at 785.00; QQQ below 746.74 and IWM below 284.18 remain the fragile legs where dealer flow accelerates breaks.
Trading readSPY's gamma stacks concentrate at and above spot with the magnet at 785.00 - dealer buying dampens on dips into 777.00 and sells into 780.00, creating today's one-dollar pin band.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY sits on a knife-edge with the charm pivot anchored at 777 and current bias reading Neutral. Net VEX at -$140.41B is a major vol-up accelerant - any uptick from 15.45 drags dealer delta hedges lower across the complex, and the one-dollar pin band between 777.00 and 780.00 is the only thing keeping the tape coherent.
QQQ and IWM carry the fragility. Net VEX at -$67.11B and -$13.3B leaves vanna hostile into any vol expansion, while charm remains supportive into the close - a textbook mixed-signature where the pin holds in quiet tape but unwinds instantly on a MOVE-led spike. Net CHEX at -$940.8K reinforces the drift neutrality.
The tripwire is binary: a break above 780.00 flips drift positive as dealers chase; a break below 777.00 opens short-gamma selling in QQQ and IWM below their flips. Trade the pivot, not the pin.
What it means for your trading
Charm pivot at 777 is the EOD tripwire with bias Neutral - vanna hostile across QQQ/IWM means a vol spike unwinds the SPY pin asymmetrically. Respect the band, size for the break.
Cross-Asset Confirmation
MOVE at 100.81 is quietly bid (2.37%% on the session) while equity vol stays contained - bond vol is pricing more tail than SPX is, and that divergence is the day's clearest cross-asset tell. Fear & Greed prints 43 (Fear): sentiment is nervous but not panicked, which lines up with contango holding and VVIX in the low regime.
Index regimes have split. SPY pins at the put wall while QQQ at 743.17 and IWM at 276.30 sit below their flips in negative_gamma - True. Index hedges are not interchangeable today; a SPY collar does not cover QQQ or IWM downside convexity.
The geopolitical stack - Iran nuclear fortification, Yemen oil flow risk, Hezbollah posture - justifies the MOVE bid even as equity vol sellers stay paid by Steep contango - vol sellers favored. Route symbol-specific: respect SPY pin, hedge QQQ/IWM separately below their flips.
What it means for your trading
Bond vol is leading equity vol higher while SPY pins and QQQ/IWM trade negative-gamma below flip - the regime split at True forces symbol-specific hedging, not index-wide proxies. With Fear & Greed at Fear and MOVE at 100.81, treat the small-cap and QQQ books as the fragile legs.
Scenario EV
The scorer returns Unknown - a true in-between. SPY pins at 777.00 with net GEX $2.09B straddling zero, while QQQ sits below flip at 746.74 and IWM runs deep negative at -$5.35B. No single structure dominates when the complex is bifurcated like this.
Default route: monetize the dislocation, not the direction. IWM VRP at 5.4% against HV20 11.16 is the richest premium in the book - iron condor at put wall 275.00 / call wall 280.00 in the 21-30 DTE window captures carry without naked vol. SPY offers thin edge (0.22%) and QQQ sits mid-range at 0.77%.
Sizing: Standard Size. VVIX at 86.43 is Low, so jump risk is not bimodally priced - but half-size any leg requiring MOVE at 100.81 to mean-revert.
What it means for your trading
Scorer label Unknown is the honest read of a split regime; the manual pick is IWM iron condor at the walls, 21-30 DTE, sized Standard Size.
Actionable Summary
Three directives for the tape: sell IWM premium at walls, respect the SPY pin at 777.00, and avoid naked QQQ below 746.74. IWM's rich VRP (5.4%) against HV20 at 11.16 funds an iron condor at 275.00/280.00 in the 21-30 DTE window - same regime, three different premium levels, and IWM is the one paying.
SPY sits locked between 777.00 and 780.00 with the charm pivot at 777 acting as the daily tripwire - fade intraday thrusts both ways while the pin holds; a clean break starts the EOD drift. QQQ's negative gamma below flip means dealer flow amplifies any chase, so keep exposure defined-risk.
Regime reads Elevated / Watchful with MOVE at 100.81 elevated against a contained VIX - half-size any structure that needs MOVE to mean-revert, because the bond tail bid is live.
What it means for your trading
Sell IWM premium at the walls, respect the SPY pin at 777.00, and keep QQQ exposure defined-risk below 746.74 - the charm pivot at 777 is the single level that flips the day's bias. Regime stays Elevated / Watchful, so size accordingly.
Iran-Russia hybrid-campaign escalation in Britain adds to the Mideast/Russia geopolitical tail stack - explains why MOVE is elevated at 100.81 while equity VIX stays contained.
Paul Tudor Jones calling 2027 challenging as buyback/M&A tailwind reverses - a long-horizon warning that reinforces why the market is reluctant to compress VIX below 15.45 even in contango.
Iran reportedly fortifying nuclear sites ahead of possible US strikes after midterms - the clearest driver of the MOVE-vs-VIX divergence and justification for tail hedges at these levels.
Saudi/OPEC+ output surge despite Iran war disruption - oil supply surprise capping energy inflation adds a disinflationary offset but the Mideast geopolitical risk still weighs.
UnitedHealth lifts profit outlook as it manages medical costs - healthcare margin resilience is one of the few idiosyncratic positives against the chip-rout narrative.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.45 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $2.09B. The gamma flip sits at N/A, with the call wall at 780.00 and the put wall at 777.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 777.34. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.8% with a volatility risk premium of 0.22%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.45. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime