Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY trades 778.13 with net GEX $2.25B and gamma regime undetermined, pinned between put wall 772.00 and call wall 785.00. QQQ at 743.82 has flipped NEGATIVE gamma - spot sits below the 747.08 flip, meaning dealer hedging now amplifies moves rather than dampening them. IWM at 276.82 remains in short-gamma territory with net GEX -$5.12B, confirming small-caps still carry the stress. Dealers face net short vanna across the complex (-$153.88B on SPY), so a VIX pop would accelerate selling. VIX term in steep contango - vix9d 11.99, vix3m 17.92, near-slope 27.52%% - short-dated vol sellers still paid. VVIX at 86.10 is subdued, so vol-of-vol is NOT flashing panic. IWM VRP at 5.2% is the rich spot of the complex; SPY VRP at 0.02% is marginal. Bottom line: fade strength into SPY 785.00, respect QQQ gamma flip at 747.08 as the trend-amplification tripwire, sell IWM premium at 21-30 DTE.
QQQ negative gamma vs SPY stable; VIX 15.31 with steep contango - mean-reversion edge intact
SPY holds near 785.00 with gamma regime unresolved but dealer flow pinned to the wall complex, while QQQ has flipped into short-gamma territory with spot under 747.08 - the divergence is today's lead story. VIX term structure stays in steep contango at 27.52%% near-slope with VVIX quiet at 86.10, so the vol-selling carry remains intact. IWM's 5.2% VRP points to the richest short-premium edge in the complex.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
778.13
-
-
785
772
766
$2.25B
-
QQQ
743.82
747.08
-0.44%
750
740
730
-$1.64B
Short gamma
IWM
276.82
284.66
-2.75%
280
275
284
-$5.12B
-
VIX
15.27
15.25
+0.10%
20
15
19
$15.41M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.56
9.54
+0.02
1.02
2.31
1.10
QQQ
15.76
15.03
+0.73
2.11
1.49
1.02
IWM
16.28
11.08
+5.20
-0.10
2.25
1.03
VIX
117.69
77.97
+39.72
-116.72
0.33
0.29
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
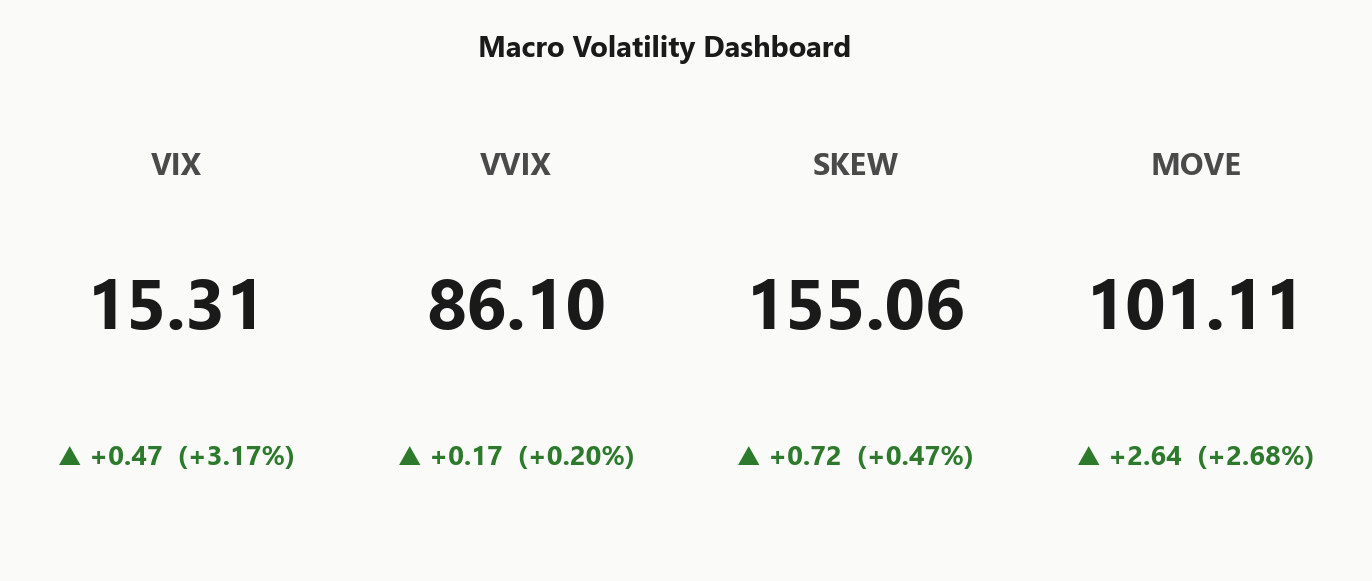
15.31
+3.17%
VVIX
86.10
+0.20%
SPX
7,805.45
-0.02%
SKEW index
155.06
+0.47%
MOVE (bond vol)
101.11
+2.68%
VIX term (9d/30d/3m/6m)
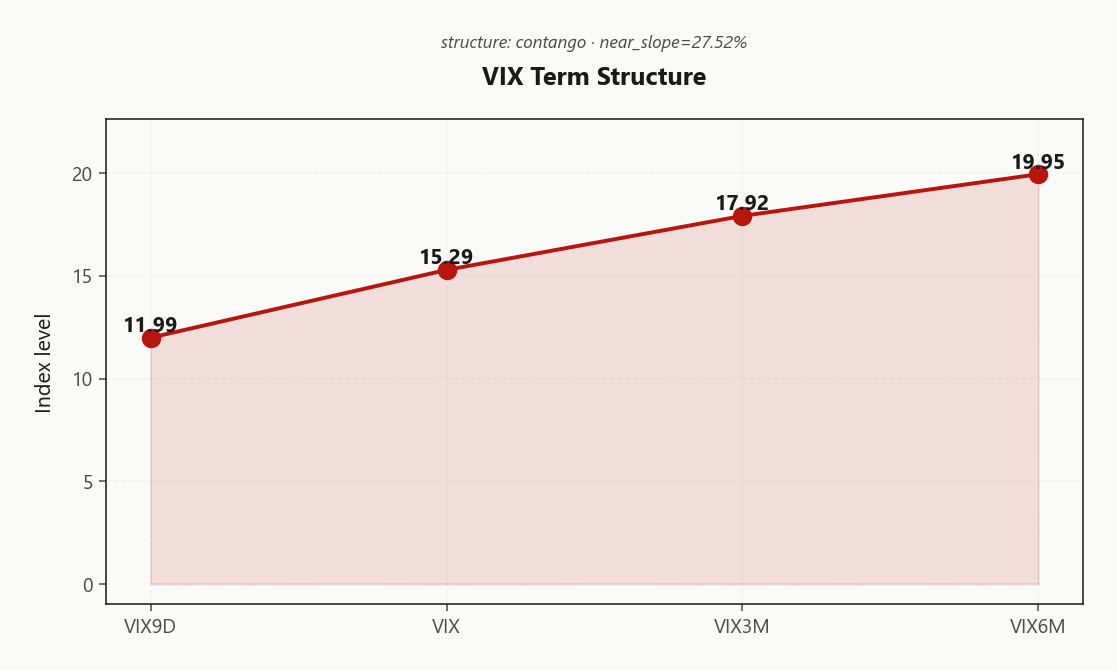
11.99 / 15.29 / 17.92 / 19.95
Steep contango
VVIX / VIX
5.62
Low
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX at 15.31 - the complex is parked between the low-vol carry zone and anything resembling panic, and the half-life of 15 sessions says this state is sticky, not transitional. Transition probabilities confirm the posture: to-panic sits at 0.05 over five sessions while to-low prints 0.45 over ten - low left-tail, modest mean-reversion, baseline short-vol carry still functional.
With the regime labeled Elevated and VVIX subdued at 86.10, there is no bimodal jump pricing demanding sizing reduction. VIX term structure in Contango with near-slope 27.52% keeps the belly paid; a half-life measured in weeks argues for 21-30 DTE expression, not weeklies.
Cross-asset tell: SPY/QQQ regime divergence at True with QQQ now sub-flip at 747.08 is the fragility inside an otherwise stable tape. Respect the tripwire; the regime is sticky but not immune.
What it means for your trading
Elevated/Watchful at VIX 15.31 with a 15-session half-life - favor three-week horizon short-vol structures, respect the QQQ gamma flip as the single tripwire that converts this sticky regime into a transition event.
Trading readVIX up 3.17%% with VVIX quiet and MOVE +2.68%% - rates vol confirming equity vol tick, not diverging. Fear & Greed neutral at 45 = no sentiment capitulation yet.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure sits in Contango with near-slope at 27.52%%, and the shape is clean across the curve: 11.99 on vix9d anchors well below spot vix at 15.29, which in turn trades under 17.92 on the three-month. No event premium is being bid into the belly - the carry stack is intact and short-dated vol sellers remain paid.
Forward 30-to-60 vol marks 19.099674081, confirming the belly is pricing continuation of the current regime rather than a priced catalyst. The forward geometry is Steep Contango and the system flags it Steep contango - vol sellers favored - the cleanest short-vol carry window of the complex.
Route trades to the 21-30 DTE belly where roll-down is steepest and vol-of-vol stays subdued at 86.10. Pair the carry with 5.2% IWM VRP as the richest premium carrier; avoid pushing size into QQQ while spot sits below the 747.08 flip.
What it means for your trading
Steep Contango with vix9d at 11.99 under vix3m at 17.92 keeps the short-vol carry trade open - sell 21-30 DTE premium, bias IWM where VRP is richest.
The volatility risk premium stack is split three ways across the index complex, and the dispersion matters more than any absolute level today. SPY VRP sits at 0.02% with ATM IV at 9.56% barely clearing HV20 at 9.54 - there is effectively no short-vol edge in large-cap index premium at these levels. QQQ VRP at 0.73% offers modest carry but comes with the negative-gamma overhang, making the premium less compensated than the headline implies.
IWM VRP at 5.2% is the structural outlier and the only clean short-premium carrier in the complex. The richness is magnified by the HV60 picture: SPY realized at 10.83, QQQ at 17.85, and IWM at 13.35 - small-cap 60-day realized actually sits below SPY, meaning IWM option buyers are paying up for volatility the underlying has not been delivering.
The routing is unambiguous: sell IWM premium at the 21-30 DTE belly where VRP is richest and realized has lagged. Skip SPY vol selling - the premium is not there. Treat QQQ carry as compromised by the flipped gamma regime.
What it means for your trading
IWM is the only index with a genuine VRP edge - 5.2% premium against sub-SPY realized at 13.35 makes short-vol structures there the cleanest trade in the book. SPY's 0.02% VRP is too thin to pay and QQQ's carry is contaminated by negative gamma.
Skew Convexity
Skew is the tell today. QQQ prints a quarter-delta skew of 2.11% with smile ratio 1.11% - put IV at 21.88% against ATM 20.81% and calls at 19.77%. That is an aggressive panic bid on downside convexity, consistent with the QQQ gamma flip at 747.08 and spot now below it.
IWM is the mirror image: quarter-delta skew at -0.1% with smile ratio 1% prints near-flat with a slight call lean - downside hedging already in, the panic trade exhausted weeks ago. SPY sits ordered at 1.02% with smile ratio 1.09%, put IV 12.89% over ATM 12.33% - no panic, no exhaustion.
Trade: on QQQ downside, use put spreads, not naked puts - the convexity premium is bid up and selling the far wing finances the near leg. IWM naked puts cheaper on a skew-adjusted basis but the regime stays short-gamma.
What it means for your trading
QQQ quarter-delta skew at 2.11% with smile ratio 1.11% is the convexity panic bid; IWM -0.1% shows the hedging already exhausted. Finance QQQ downside with spreads, not naked puts.
Vol-of-Vol Structure
Vol-of-vol is quiet. VVIX at 86.10 against VIX 15.31 prints a ratio of 5.62 - nowhere near the jump-risk zone where bimodal pricing starts leaking into VIX options. Flagged Low, signal Green. The tape is paying for drift, not for discontinuities.
Translation for the carry book: no tail premium is being charged on top of the headline VIX print, so short-vol structures don't need to be haircut for a convexity bid that isn't there. Guidance clears at Standard Size - iron condors and premium-sellers go on at full notional, no vol-of-vol tax on the Kelly.
Keep the caveat live: VVIX this subdued while QQQ dealers sit short gamma below 747.08 and net VEX stays hostile at -$153.88B means the market is cheap to a jump, not immune. Size standard, but respect the pivot at 772 as the trigger that would re-rate vol-of-vol in one session.
What it means for your trading
VVIX/VIX at 5.62 is a Green light for short-vol carry at Standard Size. No jump premium being bid means the tail is cheap, not absent - don't confuse low vol-of-vol with structural safety while dealer VEX stays hostile.
Dispersion Spread
Index vol is fanning out across the complex: 16.28% IWM ATM IV sits well north of 9.56% on SPY, with 15.76% QQQ wedged in the middle. Cross-strike dispersion at 35.22 and cross-expiry at 3.28 frame a moderate-correlation, idiosyncratic-stress regime - large-cap stability intact, small-cap name-level risk bid up, with mega-cap tech now joining the stress list as QQQ sits below the 747.08 flip.
The textbook dispersion trade - long single-name vol, short index - is paid here, but the setup is compromised. QQQ's negative-gamma regime means the short-index leg carries trend-amplification tail risk, not the usual mean-reversion damping. Index hedges will not cover a single-name blowout either, so naked short-index premium against a diversified long book is mispriced on the hedge side.
Cleaner expression: route short-vol at the index level through SPY where dispersion is contained and gamma is stable, avoid QQQ as the short-vol vehicle while short-gamma persists, and keep single-name premium selling on a short leash until correlation re-tightens.
What it means for your trading
IWM ATM IV at 16.28% vs SPY at 9.56% flags idiosyncratic small-cap stress inside a stable index tape - prefer SPY as the short-vol vehicle and treat the classic dispersion pair as impaired while QQQ runs short-gamma.
Liquidity & Microstructure
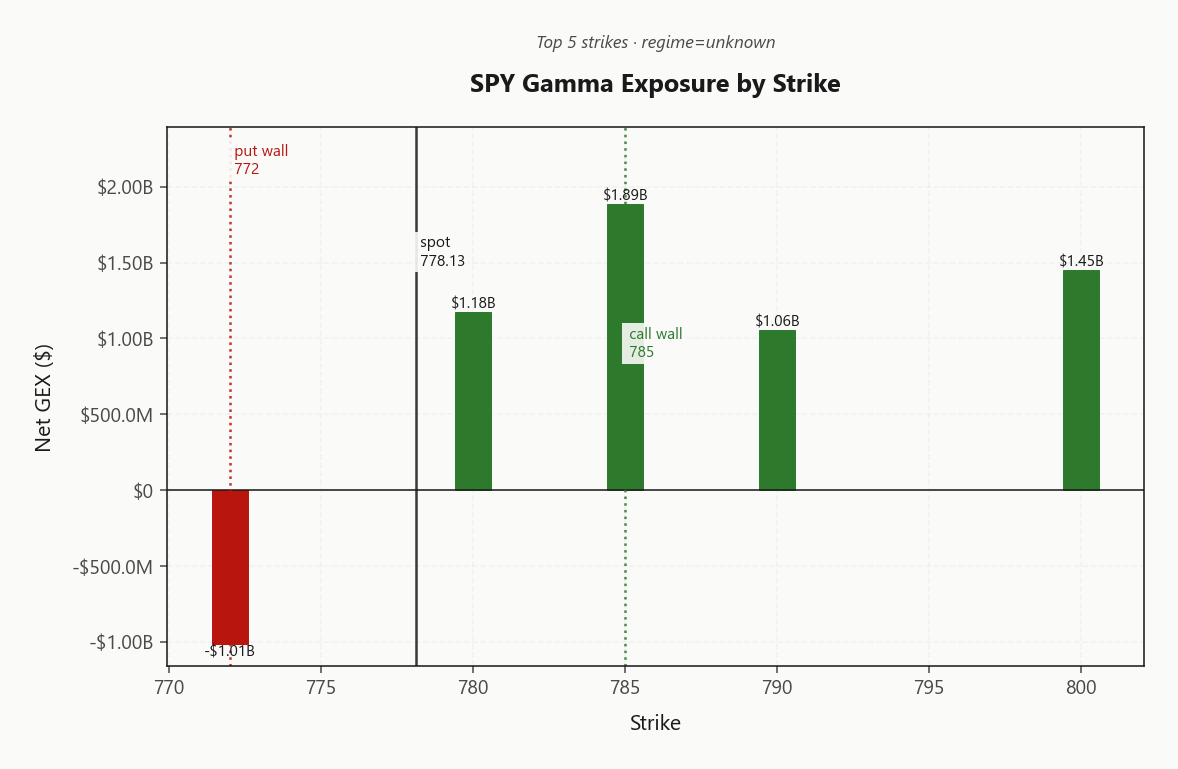
SPY's book anchors at the 500 LEAPS magnet, but the live battle sits between the 772.00 put wall and the 785.00 call wall - with the top-strike gamma pocket at 785.00 carrying $1.89B in dealer long gamma, that ceiling is the structural drag on any push higher.
QQQ is the regime story: spot has slipped under the 747.08 flip, so dealer hedging now sells into weakness rather than cushioning it. IWM's book is dense across the 275.00 - 280.00 corridor, with the heaviest concentration at 275.00 carrying -$765.6M - pure put-side short gamma, the amplifier if small-caps crack.
OI-weighted DTE prints 101.7 on SPY, 118.8 on QQQ, 123.8 on IWM - the book is longer-dated than headline flow suggests, so wall gravity should hold absent a catalyst that forces re-hedging.
What it means for your trading
The 785.00 call wall caps upside while the 747.08 flip is the trend-amplification tripwire; respect both and lean on IWM's dense put corridor as the premium-selling venue.
Trading readSPY gamma concentrated at the 785.00 wall caps upside, while QQQ shows negative dealer gamma below its flip at 747.08 - expect dampening on SPY rallies and amplification on QQQ selloffs through the day.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna exposure sits deeply negative across the mega-cap complex - SPY at -$153.88B and QQQ at -$73.58B. Translation: any VIX pop forces mechanical dealer selling of delta, and with QQQ already short-gamma below the 747.08 flip, vanna and gamma are aligned bearish on an IV spike. There is no stabilizing counterbalance in the mega-cap book today.
Trade implication: respect the hostile vanna setup as a size-reducer on any naked short-vol lean in SPY/QQQ, and lean into IWM where the charm support meets the richest VRP in the complex.
What it means for your trading
Hostile vanna across SPY/QQQ (-$153.88B) means a VIX pop mechanically forces dealer delta-selling, with no gamma counterbalance now that QQQ has flipped short. Watch the 772 pivot - a break shifts bias from Neutral to directional, and IWM charm support becomes the only reliable mean-reversion anchor into the close.
Cross-Asset Confirmation
MOVE at 101.11 is grinding higher at +2.68%% while Fear & Greed holds Neutral at 45 - rates vol is leaking in from the Saudi/Yemen tape, but equity sentiment refuses to capitulate. The cross-asset tell is clean: geopolitical premium is being priced through rates and oil, not through credit or sentiment, which keeps the shock isolated rather than systemic.
Under the hood, the SPY/QQQ regime split is confirmed at True - tech leadership is cracking while large-cap breadth stays bid. QQQ at 743.82 is doing the heavy lifting on the downside, with mega-cap gamma deteriorating faster than IWM at 276.82 - an inversion of the usual stress hierarchy where small-caps lead the fragility.
Read the tape as rates-vol creep plus tech-led fragility, not a credit event. Fade panic hedges priced through MOVE; respect that the fault line today is QQQ, not IWM.
What it means for your trading
Geopolitical tail is live in rates vol (101.11) but absent in sentiment (Neutral at 45) - isolated equity/rates vol, not a credit shock. SPY/QQQ divergence means tech is cracking faster than small-caps today, flipping the usual fragility stack.
Scenario EV
The scorer prints Unknown on structure and Unknown on VRP - framing hostile, no auto-signal to lean on. Manual override: default to an IWM iron condor at the 275.00/280.00 wall complex, sized at the 21-30 DTE belly where the term-structure carry sits cleanest.
VRP distribution is the whole trade. IWM at 5.2% is the richest premium in the complex and the only name paying enough to warrant a defined-risk short-vol structure; SPY at 0.02% is too thin to carry, and QQQ at 0.73% sits inside a negative_gamma regime with spot below 747.08 - dealer flow amplifies rather than dampens.
AVOID QQQ naked short vol while the short-gamma regime is active; any VIX pop forces mechanical delta selling against -$73.58B. Keep the IWM wing short, defined, and inside the walls - not the trade to press size on with the scorer unresolved.
What it means for your trading
Scorer unresolved at Unknown; manual read is IWM iron condor at 275.00/280.00 on 21-30 DTE where VRP at 5.2% is the only premium worth paying - avoid QQQ short vol until spot reclaims 747.08.
Actionable Summary
Bottom line: sell N/A iron condor at 275.00/280.00 on the near-dated belly - the 5.2% VRP is the richest short-premium carry in the complex while 0.02% on SPY is too thin to pay and QQQ's flipped-gamma regime makes naked short vol a trap. Respect 747.08 as the tripwire: spot already sits below it, so any extension lower runs with dealer flow, not against it.
Fade strength into SPY 785.00 - the wall is the drag and net VEX at -$153.88B means any vol pop mechanically forces dealer selling into the complex. On QQQ downside, prefer defined-risk put spreads over naked puts; smile ratio 1.11% is overpaying for convexity you don't need to own outright.
Size standard - VVIX at 86.10 is not flashing jump risk, regime reads Elevated / Watchful, and the charm pivot at 772 is the SPY-side tell to re-check through the close.
What it means for your trading
Trade the richest VRP (IWM iron condor at the walls), fade SPY into 785.00, and avoid naked QQQ short vol while spot sits below 747.08 - size standard with VVIX quiet at 86.10.
Loud booms near Saudi Aramco HQ compound the geopolitical tail - oil supply premium feeds MOVE and rates vol, which indirectly validates the elevated VIX regime without triggering equity capitulation.
Saudi strikes Yemen as Houthis vow retaliation - classic geopolitical shock pattern that drives MOVE higher but typically mean-reverts within weeks unless credit spreads join the move.
Airport attacks disrupting aviation and airspace put a floor under energy and defense names and introduce supply-chain tail risk - relevant for whether QQQ's negative-gamma regime extends on broader risk-off.
Trump accusing Houthis of oil-price manipulation ahead of midterms politicizes the energy complex and raises the probability of US policy response - binary catalyst for crude vol.
Paul Tudor Jones warning 2027 could be challenging as buybacks and M&A tailwinds fade - directional macro view that argues against adding structural long-equity carry at current valuations.
Jim Cramer flagging the chip stock rout as 'knowing no end' aligns with the QQQ gamma flip and NVDA's position on the top-mover list - semiconductor weakness is the single-sector lead on tech underperformance.
Citi beating on investment banking and wealth - bank earnings tracking in-line with the elevated/watchful regime; no credit crack signal from the big banks keeps the geopolitical shock contained to equities/rates vol.
Wells Fargo beats profit but misses on NII and revenue - mixed bank print consistent with yield curve dynamics; worth watching for whether rates vol compounds into credit.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.27 with a Contango term structure. The Fear & Greed index reads Neutral, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $2.25B. The gamma flip sits at N/A, with the call wall at 785.00 and the put wall at 772.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 778.13. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.56% with a volatility risk premium of 0.02%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.31. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime