Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 774.71 is sitting right on top of its gamma flip at 774.82 - net GEX -$1.67B puts dealers in a short-gamma regime where moves get amplified rather than dampened. Key levels: call wall 785.00, put wall 770.00, max pain 765.00 - a push either side of the flip flips dealer hedging direction. QQQ echoes the setup below 754.20 with net GEX -$724.2M; IWM is the fragile outlier with net GEX -$5.12B and spot below the sensitive flip. Dealer vanna -$142.82B and 0DTE GEX concentration at 149.4%% mean a vol spike accelerates downside - charm bias is destabilizing per Destabilizing. Vol read: VIX 15.81 up 5.33%%, VVIX 87.13, term structure contango 31.5%%, VRP 0.63% - vol sellers still get paid but premiums are thin at the ATM. Bottom line: iron condor 30-45 DTE is the scored structure - fade walls, respect the flip, half-size until spot gets a clear side.
SPY sits virtually atop its gamma flip at 774.82 with dealers short gamma, meaning any directional push gets amplified in the direction of the move. QQQ mirrors the same destabilizing posture below 754.20, while IWM remains the fragile tail with net GEX at -$5.12B. VIX contango at 31.5%% and VVIX at 87.13 still favor vol sellers - but keep structures defined given the pivot proximity.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
774.71
774.82
-0.01%
785
770
765
-$1.67B
Short gamma
QQQ
753.03
754.20
-0.16%
760
750
725
-$724.18M
Short gamma
IWM
278.55
289.16
-3.67%
285
275
285
-$5.12B
-
VIX
15.80
15.71
+0.56%
20
15
19
$6.26M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.06
10.43
+0.63
2.22
2.19
2.00
QQQ
15.87
15.12
+0.75
3.49
1.41
1.53
IWM
17.57
11.81
+5.76
2.43
2.39
2.82
VIX
80.81
98.17
-17.36
-124.13
0.32
0.11
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.81
+5.33%
VVIX
87.13
+5.50%
SPX
7,775.12
-0.56%
SKEW index
141.21
-1.28%
MOVE (bond vol)
106.54
-6.21%
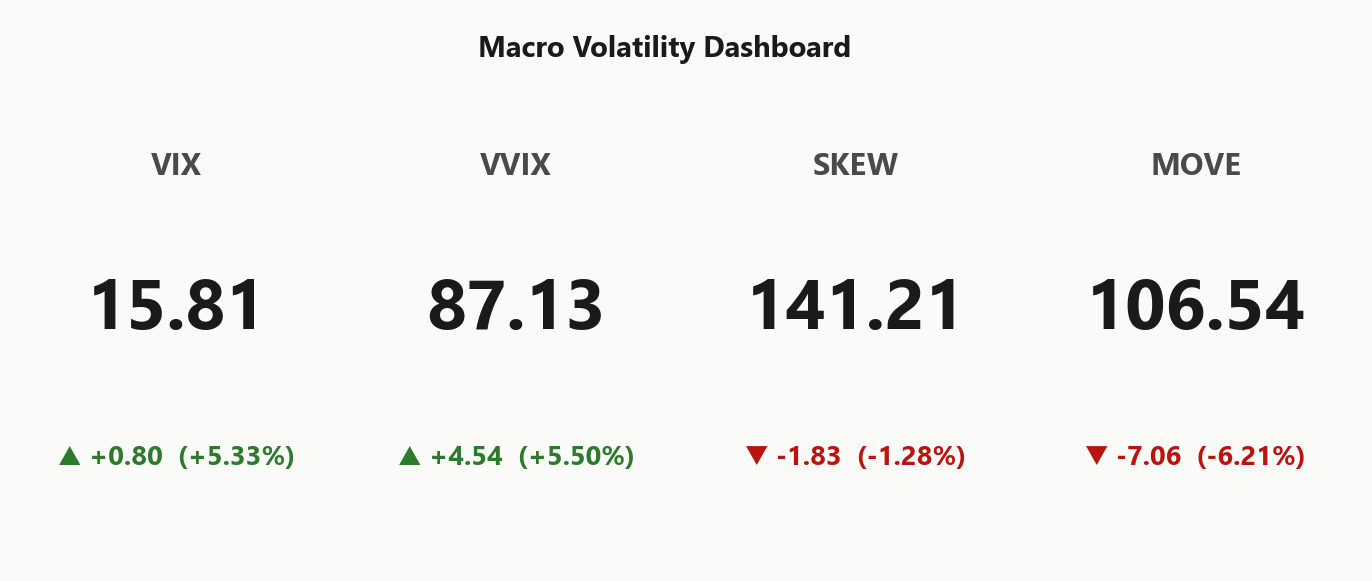
VIX term (9d/30d/3m/6m)
12.03 / 15.82 / 17.64 / 19.84
Steep contango
VVIX / VIX
5.51
Low
Regime
Elevated / Watchful
Regime Assessment
The tape sits in an Elevated regime - Elevated / Watchful - with VIX anchored at 15.81. This is not panic and it is not complacency; it is the band where positioning sets the price, not sentiment. Half-life sits at roughly 15 sessions, which means the regime has staying power - fading it on a single-session wobble is a losing trade.
The transition map is asymmetric. Probability of rolling to panic over the next five sessions prints at 0.05, while probability of drifting back to a low-vol regime over ten sessions sits at 0.45 - mean reversion is the base case, but the left tail is live given destabilizing charm and spot pinned at the flip. Trade the carry, respect the trapdoor.
What it means for your trading
Regime is Elevated / Watchful with VIX at 15.81 and a 15-session half-life - stick with the carry structure, but keep risk defined because transition odds down (0.05) sit asymmetric to drift back to low (0.45).
Trading readVIX up, VVIX up, MOVE down, F&G neutral - the macro picture is NOT confirming equity stress. This is an isolated equity-gamma event, not a systemic risk-off signal.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
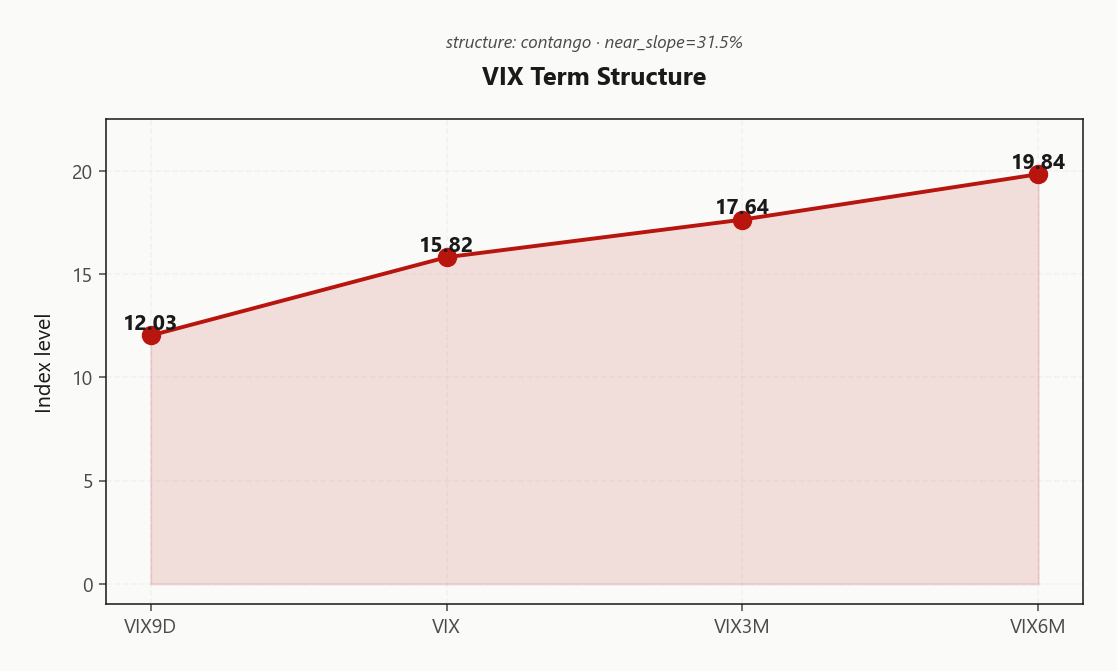
The VIX complex is in Steep Contango - VIX9D at 12.03, spot VIX 15.82, VIX3M 17.64, VIX6M 19.84. Monotonic bid up the curve, structure confirmed Contango. The near slope at 31.5%% is telling: event premium is being parked in the belly, not the front - Fed minutes and the geopolitical tape are priced into the 30-60 bucket, not the next two weeks.
Forward 30-60 vol resolves to 18.4829164365 against 60-90 at 21.8192942141 - a clean carry window where theta decay outruns the implied path. Signal reads Steep contango - vol sellers favored: sellers get paid, and the richest edge sits where the slope is steepest, not at the ATM front.
Trade geometry: 30-45 DTE is the sweet spot. Sell the belly where event premium is overstated, keep wings defined given Destabilizing charm bias and spot pinned at 774.8229350273. Fade front-month richness via calendars only if VVIX breaks higher.
What it means for your trading
Steep contango at 31.5%% near slope with forward 30-60 at 18.4829164365 defines the carry window - sell the belly, not the front, at 30-45 DTE.
Trading readMonotonic contango with near slope 31.5%% says the market expects today's wobble to fade - vol-of-time carry trade is intact, the belly is where the real event risk sits.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM implied sits at 11.06% against HV20 10.43 and HV60 11.05 - the spread is tight but positive, and VRP at 0.63% confirms sellers still get paid without stepping onto a premium cliff. This is carry territory, not a vol-selling bonanza.
The richer harvest sits in small-caps: IWM VRP at 5.76% dwarfs the SPY read, consistent with the small-cap stress bleeding into options pricing. QQQ ATM IV 15.87% against HV20 15.12 preserves the index carry window - mega-cap theta is intact but thin.
With VVIX in the Low regime and term structure in Contango, the realized/implied gap favors defined-risk short vol over naked. The IWM premium is tempting but regime-ambiguous; SPY iron condor remains the cleaner carry.
What it means for your trading
Options are mildly rich to recent realized across the complex with VRP at 0.63% - enough edge to sell, not enough to size up. Harvest IWM richness only via defined wings; take the cleaner SPY carry at the belly.
Skew Convexity
The 13.89% put versus 12.59% ATM versus 11.67% call quarter-delta profile prints a skew of 2.22% with a smile ratio of 1.19% - downside is bid, upside is flat, and the left tail is ordered rather than panicked. Protection pays a premium, but no one is reaching for it.
QQQ steepens the picture: its quarter-delta skew at 3.49% says tech downside is being bid more aggressively than the index composite, consistent with the negative-gamma backdrop and the destabilizing charm pivot at 774.8229350273. Call wings stay cheap - no chase into 785.00.
Structure read: with the tail paying but ordered, put spreads dominate naked puts on a risk-adjusted basis, and selling the far call wing into a flat upside skew finances the hedge cleanly. Favor defined-risk condors around 785.00 / 770.00; avoid monetizing the body where the premium thins out fastest.
What it means for your trading
Skew at 2.22% with smile ratio 1.19% says the market is paying for protection in an orderly fashion - put spreads over naked puts, condors over strangles, and respect the 774.8229350273 pivot while QQQ's steeper tail does the leading.
Vol-of-Vol Structure
VVIX at 87.13 against VIX 15.81 plants vol-of-vol squarely in the Low regime - jump risk is not being bimodally priced, and the ratio at 5.51 reads ordered rather than binary. Translation: dealers are not paying up for convexity on convexity, which keeps the short-vol carry trade mechanically viable.
Sizing guidance resolves to Standard Size - no haircut required to run the scored iron condor at full clip. But the second derivative deserves respect: VVIX is up 5.5% on the session, and with spot pinned at 774.82 and net vanna at -$142.82B, any sustained VVIX breakout flips the compounding math against sellers quickly.
Trade the regime you have, not the one you fear - but keep the VVIX tape in the top-right corner of the screen.
What it means for your trading
VVIX regime scores Low with sizing cleared to Standard Size, so short-vol structures run at normal weight. Monitor the VVIX change of 5.5% - a sustained rise is the first signal to half-size.
Dispersion Spread
Index vol is sitting compressed against single-name realized - SPY ATM at 11.06% prints flat to 15.87% on QQQ, with the cross-strike dispersion read running 64.27 against cross-expiry 3.14. The index tape is pricing a Moderate correlation regime - hedges wrapped at the index level are structurally cheap to idiosyncratic exposure, which means basket shorts underperform name-level strangles for anyone fading single-stock richness.
IWM is the carve-out: ATM IV at 17.57% sits well above the mega-cap pair on small-cap positioning stress, consistent with the fragile regime read and the unresolved flip root. That premium is real, but it is paid for a reason - the regime label is Unknown and the carry comes with directional ambiguity, not a clean vol-of-time harvest.
Trade construction follows: with cross-asset tone Aligned across the mega-cap book, SPY iron condors clear single-name strangles on risk-adjusted carry. Fade index-level richness, respect the walls, leave idiosyncratic premium for dispersion specialists running correlation books with the mandate for it.
What it means for your trading
Dispersion sits Moderate with index IV compressed against elevated small-cap vol - SPY iron condors are the preferred vehicle over single-name strangles while IWM's richer VRP sits behind an unresolved regime.
Liquidity & Microstructure
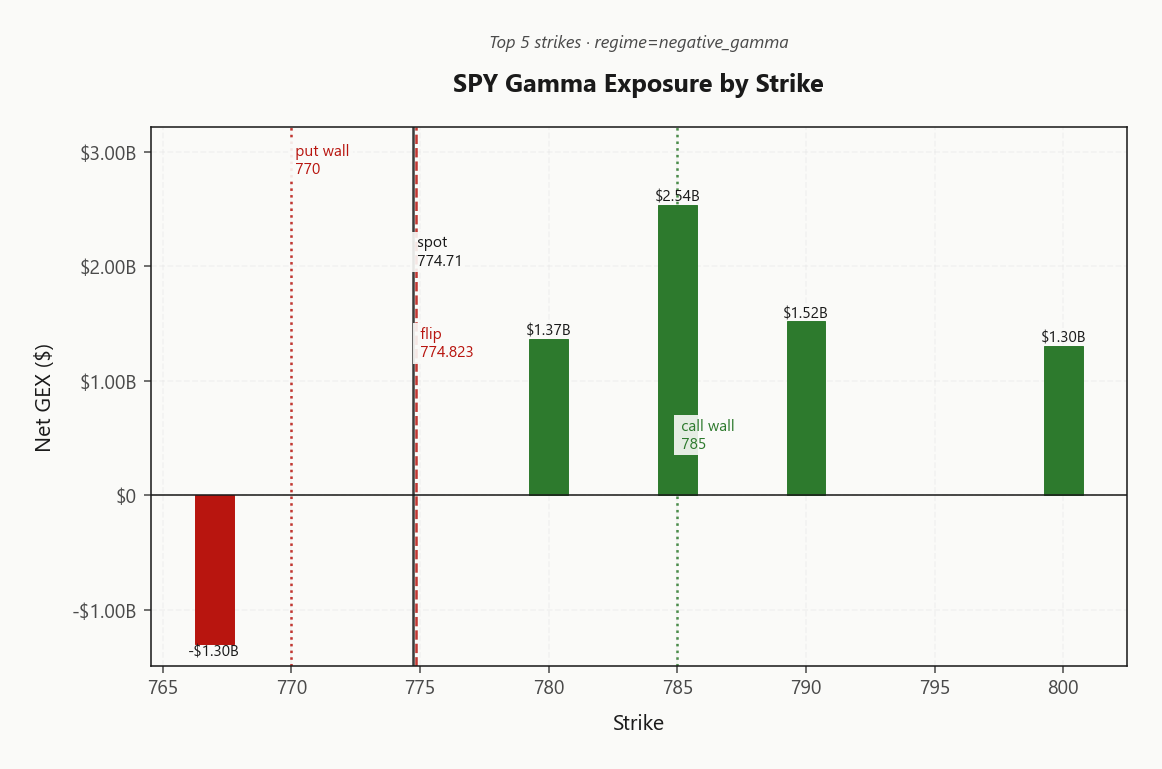
SPY's book is anchored by the 785.00 call wall, carrying $2.54B of net GEX at the pole - this is the gravitational ceiling, not a soft resistance line. The 500 OI anchor is far-dated clutter, irrelevant to today's tape. What matters is spot 774.71 sitting virtually atop the gamma flip at 774.82, where dealer hedging bias inverts.
Below the flip, dealers are short gamma - supply hits on down-moves, bids thin on up-moves. The 770.00 put wall is the trapdoor: a close beneath it accelerates the sell program rather than cushions it. Pushes into 785.00 get faded, breaks under 770.00 compound.
Compounding the fragility, 0DTE carries 149.4% of total gamma - intraday is a whip tape, not a trend tape. Trade levels, not direction, until spot picks a side of the flip.
What it means for your trading
Spot pinned at the flip with the call wall at 785.00 and the trapdoor at 770.00 - fade walls, respect the pivot, scalp 0DTE off levels rather than positioning for direction.
Trading readDealers are short gamma around spot with the gravitational pull sitting at the call wall 785.00 - pushes toward 785.00 get sold, breaks below put wall 770.00 accelerate. The flip at 774.82 is the regime switch - above it, moves dampen; below, they amplify.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits deeply negative at -$142.82B - a vol-up tick is not a hedge event, it's a selling event. Any lift in 15.81 forces dealers shorter delta into the move, compounding downside rather than cushioning it. With VVIX ticking at 87.13, the second derivative is the tell to watch, not the first.
Net charm at $67.1K is thin on this side of the flip - the usual theta-into-pin drift is not operative here. Charm pivot anchors at 774.8229350273, with spot pressed to within 0.0145777165 of that line. On this side, time decay accelerates rather than stabilizes the hedge flow.
Bias reads Destabilizing: treat the pivot as an accelerant, not a magnet. Keep structures defined, fade walls, size standard but respect that vanna and charm are pulling the same direction.
What it means for your trading
Vanna -$142.82B and charm $67.1K are both pulling destabilizing - a vol spike compounds dealer selling, and theta offers no pin support with spot glued to the 774.8229350273 pivot.
Cross-Asset Confirmation
Rates vol is easing while equity gamma destabilizes - MOVE at 106.54 down -6.21% says the Treasury complex isn't confirming the equity wobble. That matters: cross-asset tone reads Unknown, Fear & Greed sits Neutral at 47 - no credit stress, no rates panic, no sentiment capitulation feeding the gamma pin.
QQQ at 753.03 and IWM at 278.55 are Aligned with SPY's regime per Aligned - the destabilization is isolated to equity dealer books, not propagating across the macro picture. Classic equity-only gamma event: amplifying mechanics without the systemic bid for protection that would compound a selloff.
Mean reversion odds favored over cascade. Keep structures defined around the flip, but don't fade a macro shock that isn't actually in the tape.
What it means for your trading
Rates vol easing, sentiment Neutral, and Aligned cross-asset positioning mean this is an isolated equity-gamma event - mean reversion edge, not compounding risk-off.
Scenario EV
Scenario EV lands on Iron Condor at score 38, with the put spread trailing at 25 - the carry structure wins cleanly. VRP positive at 0.63%, VVIX anchored Low at 87.13, VIX term structure in Steep Contango with near slope 31.5%%. Three independent carry signals pointing the same direction.
Optimal window is 30-45 DTE - far enough from gamma whip, close enough to harvest the belly premium where event risk is actually priced. Build the condor around call wall 785.00 and put wall 770.00, respecting the flip at 774.8229350273 as the pivot that invalidates the thesis.
Sizing stays Standard Size while VVIX holds the low regime - but today's 5.5%% uptick is the tripwire. Break higher and the second derivative demands half-size; charm bias at Destabilizing leaves no cushion for sloppy wings.
What it means for your trading
Iron condor 30-45 DTE is the scored structure - fade walls, respect the flip at 774.8229350273, size standard until VVIX breaks the Low regime.
Actionable Summary
Bottom line: deploy Iron Condor structures in the 30-45 DTE window, bracketed by the 785.00 call wall and 770.00 put wall. Fade pushes into 785.00 on the upside - the gamma pole does the heavy lifting. Regime reads Elevated / Watchful, so size standard but keep the VVIX second derivative on screen given today's 5.5% tick.
Avoid naked short gamma while spot sits on the flip at 774.8229350273 - charm bias reads Destabilizing and net vanna at -$142.82B turns any vol spike into dealer supply. Skip chasing IWM short vol into an unresolved regime, even with VRP at 5.76%.
Watch the break of 774.82 either side - that's the hedging-direction switch, not a technical level.
What it means for your trading
Carry structure of the day is Iron Condor at 30-45 DTE, fading walls and respecting the flip at 774.8229350273. Standard size holds while VVIX stays contained; a clean break of 774.82 is the trigger to half-size or step aside.
Google data-center halt in Finland is incremental AI-infrastructure friction - matters for mega-cap capex narratives (GOOGL, MSFT, META) that have supported QQQ's bid.
Shell flagging record refining margins on Mideast conflict premium signals persistent energy inflation risk - supportive of energy sector, headwind for the disinflation trade and Fed-cut tape.
India's first rate hike in nearly four years joins a global tightening wave - tilts the macro liquidity story firmer and complicates EM-sensitive risk assets and the broader DM easing narrative.
Fed minutes awaited for rate-cut signal clarity - this is the next scheduled vol catalyst and explains why the belly of the VIX curve is bid relative to the front.
Oil higher on supply threats reinforces the inflation-stickiness side of today's rate-sensitive trade - energy strength is quietly offsetting the dovish Fed narrative.
Vance tying war termination to Iran enrichment cuts is a direct geopolitical headline risk - binary outcome keeps the belly VIX bid, consistent with today's contango structure.
Trump saying nobody knows who runs Iran heightens negotiating uncertainty - tail risk headline that supports keeping defined-risk structures over naked short vol.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.80 with a Contango term structure. The Fear & Greed index reads Neutral, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 774.82 against a spot of 774.71. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.06% with a volatility risk premium of 0.63%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.81. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime