Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 778.61 sits in Positive Gamma with net GEX $12.7B - dealers long gamma, moves dampened into the open. Call wall 785.00 caps, put wall 770.00 supports, and gamma flip at 775.18 is only -0.439294347% below spot - a thin cushion, not a deep one. Dealer vanna net -$202.94B means a vol spike turns dealers into sellers; charm net -$5.3M adds late-session pressure. VIX 15.40 with term structure in Contango and VVIX 84.65 - carry is there, vol-of-vol is Low, VRP -0.71% says SPY options cheap to recent realized. IWM diverges hard: Negative Gamma below flip 283.83, positive VRP 3.33% - short-vol fuel on the small-cap side. MOVE at 110.66 ticking up warns of a rates undertone despite equity calm. Bottom line: Iron Condor on SPY/QQQ at 30-45 DTE, fade strength into 785.00, respect 775.18 as the hinge - breach flips the whole tape negative-gamma.
SPY 778.61 sits above gamma flip 775.18 with dealers long gamma and a call wall at 785.00 capping upside into 700-heavy OI. The small-cap tape diverges: IWM at 283.65 is below flip 283.83 with Negative Gamma exposure and a positive VRP of 3.33% - the lead story is the index-vs-smallcap bifurcation. Steep contango (Contango) and Low VVIX say vol sellers are still paid, but Elevated / Watchful regime demands sizing discipline.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
778.61
775.18
+0.44%
785
770
763
$12.70B
Long gamma
QQQ
760.47
753.81
+0.88%
775
749
730
$6.70B
Long gamma
IWM
283.65
283.83
-0.07%
285
280
285
-$2.89B
Short gamma
VIX
15.40
15.61
-1.36%
20
15
19
-$27.39M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.80
10.51
-0.71
1.46
2.16
0.84
QQQ
14.67
15.16
-0.49
2.11
1.46
1.08
IWM
15.03
11.70
+3.33
1.63
2.47
1.99
VIX
81.98
97.43
-15.45
-120.40
0.33
1.89
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
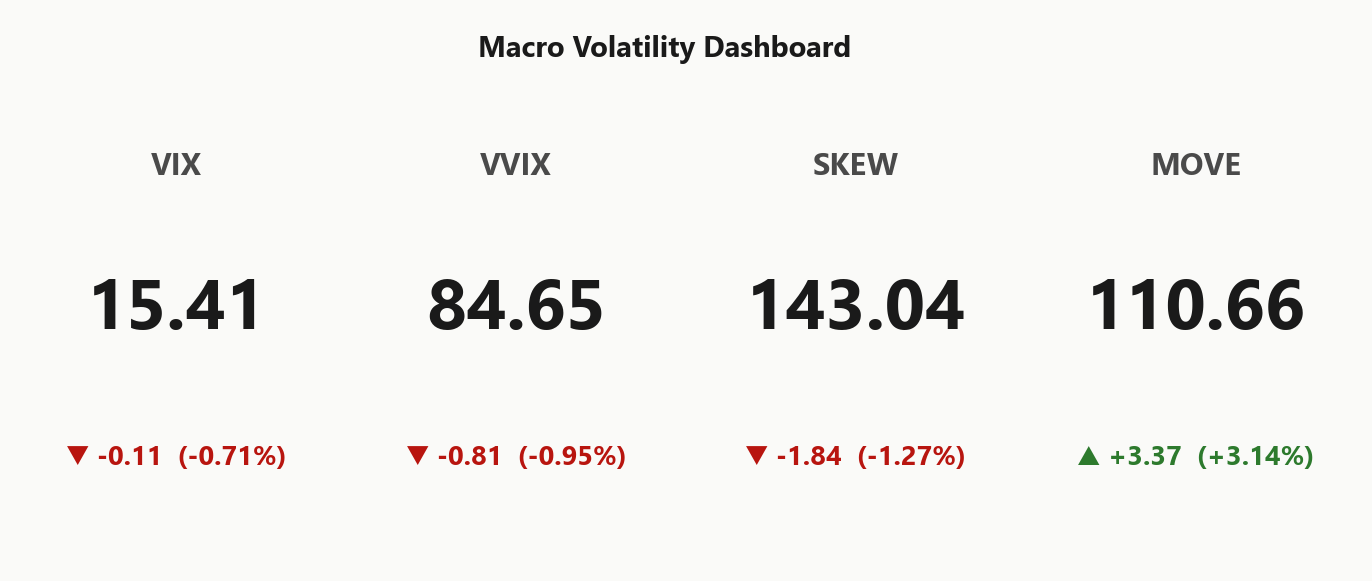
VIX
15.41
-0.71%
VVIX
84.65
-0.95%
SPX
7,814.80
+0.53%
SKEW index
143.04
-1.27%
MOVE (bond vol)
110.66
+3.14%
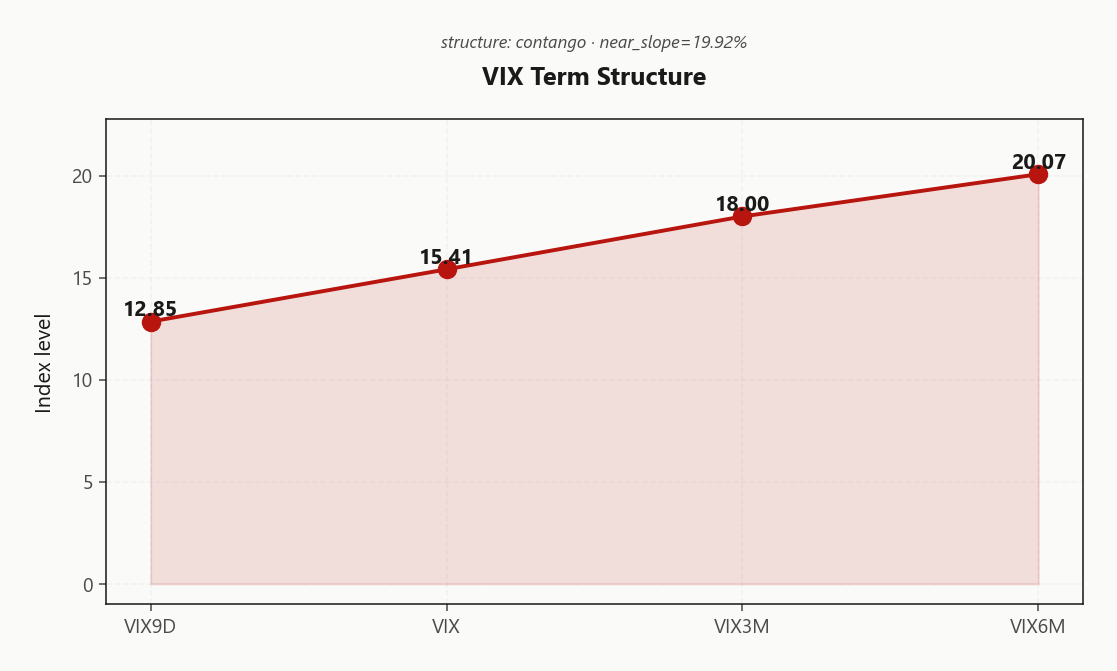
VIX term (9d/30d/3m/6m)
12.85 / 15.41 / 18.00 / 20.07
Steep contango
VVIX / VIX
5.49
Low
Regime
Elevated / Watchful
Regime Assessment
The tape sits in Elevated regime, labeled Elevated / Watchful, with VIX anchored at 15.41. The transition matrix is telling: probability of escalating to panic over the next 5 sessions is 0.05, while probability of drifting into a low regime over 10 sessions sits at 0.45. This is watchful, not panicked - the setup rewards carry with discipline, not conviction maximization.
Half-life of 15 sessions means this regime dominates the next two trading weeks. The low near-term panic probability underwrites a vol-selling bias, but the elevated label - not low - says standard size, not hero size. Sticky elevated with a slow drift lower is the base case; aggressive short-gamma into a regime that resolves gradually is exactly how carry trades blow up on the one session that doesn't fit the mean.
Trade the regime you have: short premium at 30-45 DTE on index names, defined-risk hedges on small-cap exposure, and respect 775.1846322494 as the hinge that re-rates the whole book.
What it means for your trading
Elevated-but-watchful regime with half-life of 15 sessions and only 0.05 probability of near-term escalation supports vol-selling carry at standard size. Don't press the trade - the slow drift lower is the base case, not a conviction setup.
Trading readVIX down, VVIX down, SKEW 143.04 softening, MOVE up 3.14%% - equity-vol cluster confirms calm but MOVE's divergence is the one quiet warning worth tracking.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
The kink matters more than the slope. Forward 30 - 60 vol clears at 19.1641840421 while 60 - 90 jumps to 21.9456100394 - the back-end bid says the market is paying up for later-quarter event premium, not current realized. Translation: the belly of the curve is where carry concentrates, the back is where hedgers are already parked.
Trade the geometry, don't fight it. Favor front-month short premium at 30 - 45 DTE, harvest the roll-down into the Steep Contango regime, and roll before the back-end steepens further. Watch for compression at the 2 - 3 month tenor - that is where calendars start to look rich and where sellers should trim size.
What it means for your trading
Steep Contango with near-slope 19.92%% and a 19.1641840421 → 21.9456100394 kink pays sellers in the 30 - 45 DTE window. Roll aggressively before back-end premium drifts higher.
Trading readSteep contango with near-slope 19.92%% says the market is not pricing imminent stress - vol carry is paying, roll aggressively.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 9.8% prints under HV20 10.51 and HV60 11.13, leaving the index at a negative VRP of -0.71%. That inversion says the tape has been more active than options are pricing - a setup where long-gamma scalping bias works and naked short-vol does not.
QQQ echoes the pattern with VRP -0.49%, confirming mega-cap tech options are undercompensated for realized. The clean dislocation sits on IWM: VRP flips to 3.33% positive - the only genuine short-vol fuel in the complex and the single credible premium-harvest tape today.
Trade geometry follows: run defined-risk short-vol on IWM where carry is real, and favor long-gamma scalps or spread structures on SPY/QQQ rather than naked strangles. The index VRP will not reward sellers until realized compresses - until then, the premium lives in small-caps.
What it means for your trading
SPY and QQQ sit at negative VRP (-0.71% / -0.49%) - options cheap to recent realized, long-gamma biases favored. IWM's positive VRP 3.33% is the only clean short-vol fit in the complex.
Skew Convexity
SPY 25-delta skew prints 1.46% with a smile ratio of 1.13% - an ordered downside bid, not a panic bid. Put 25d IV at 12.39% sits above ATM 11.27%, while call 25d holds 10.93% - a quiet downside premium with no upside conviction being paid for.
The smile ratio argues against naked long puts: the wing isn't blown out, so spread the hedge rather than owning raw convexity. Flat call skew means upside participation is cheap but unloved - covered-call income remains well-compensated against the 785.00 magnet, and risk-reversals favor sellers of the put wing against the call wing.
The real fear premium lives on the small-cap side: IWM 25d skew at 1.63% prices downside richer where regime is Negative Gamma below flip 283.83. Harvest IWM put skew via spreads, not nakeds; keep SPY hedges defined-risk until the smile convexes.
What it means for your trading
SPY skew is a polite put bid with flat calls - spread hedges, don't own raw tails; IWM 25d skew 1.63% is where the genuine fear premium sits and where defined-risk short-put-wing structures earn the best carry.
Vol-of-Vol Structure
VVIX at 84.65 sits well under any stress threshold, and the VVIX/VIX ratio prints 5.49 against VIX 15.41 - a Low jump-risk read with signal Green. Tails are not being bid; the options market is not pricing a bimodal crush-or-spike outcome, and the convexity surface is behaving.
That matters because it unlocks real carry. With vol-of-vol compressed, short-premium structures do not need defensive sizing - the regime justifies Standard Size, not the reflexive half-clip that a benign tape often invites. The pairing of a Steep contango - vol sellers favored term structure with a quiet VVIX is the cleanest short-vol backdrop the complex offers.
Caveat: a quiet VVIX is a conditional green light, not a standing one. A gap higher in VVIX against negative dealer vanna -$202.94B would convert the cushion into an accelerant quickly - size standard, but keep a defined-risk hedge paired with the carry.
What it means for your trading
VVIX 84.65 and a ratio of 5.49 flag Low jump risk - run Standard Size on short-vol, do not over-fit the calm.
Dispersion Spread
Index vol is suppressed while the complex underneath isn't: SPY ATM IV at 9.8% sits well below QQQ at 14.67% and IWM at 15.03%. That gap is a dispersion signature - correlation is dropping, idiosyncratic risk is where the vol actually lives, and the index tape is being held in by basket-level dampening even as single-name realized runs hot.
The trade implication is directional: sell index premium systematically, own single-name premium selectively. SPY/SPX short-vol harvests the correlation collapse, and the Iron Condor at 30-45 DTE fits the geometry - bounded by 785.00 and 770.00, cushioned by Positive Gamma dealers above 775.18.
Caveat: moderate correlation at elevated single-name vol means an index hedge won't fully offset a basket drawdown. If IWM leads lower from Negative Gamma, SPY puts underperform the mark-to-market pain in the components. Hedge the basket, don't hedge the index - or carry the put spread as insurance, not as an offset.
What it means for your trading
Dispersion favors selling index vol while leaving single-name premium alone - the index-vs-component IV gap between 9.8% and 15.03% is the cleanest edge on the sheet, but moderate correlation means SPY hedges won't neutralize single-name drawdowns if 775.18 breaks.
Liquidity & Microstructure
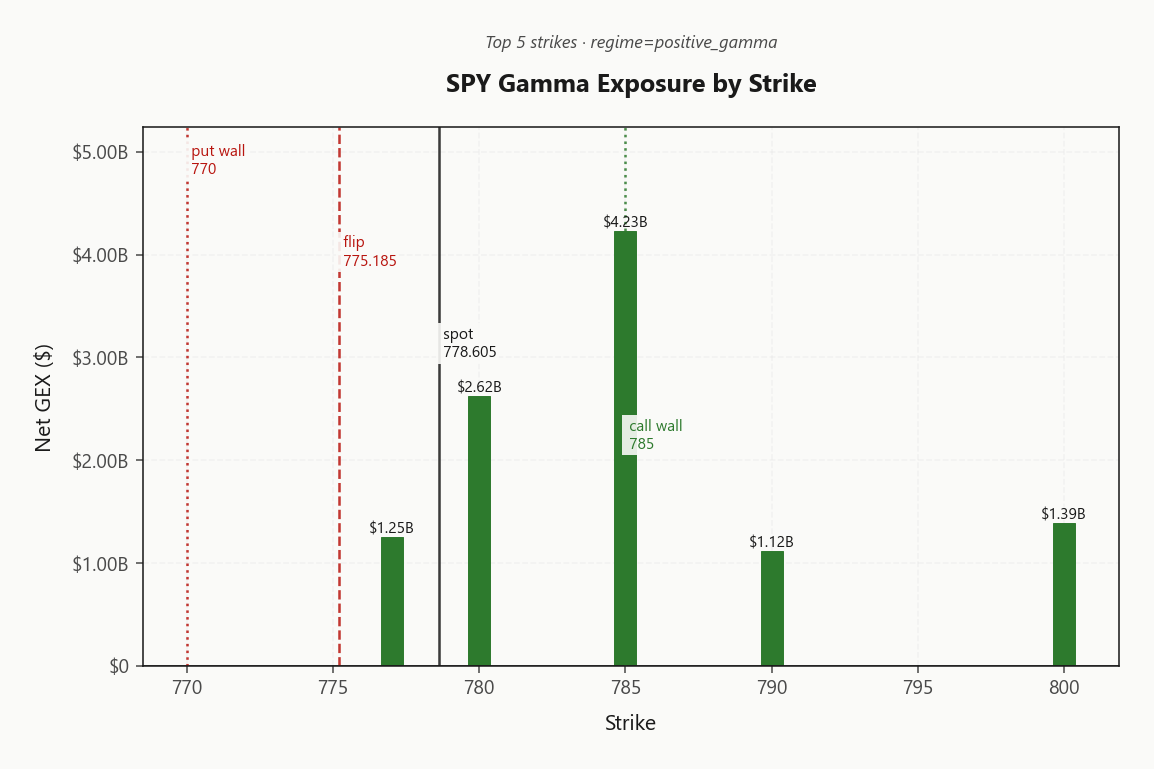
The deepest open interest sits at 700, but that strike is a longer-dated anchor rather than today's magnet. The live battleground runs the 785.00-to-770.00 band, with top-strike net GEX at $4.23B acting as the upside magnet into the close.
Call wall 785.00 caps rallies; put wall 770.00 absorbs the first wave of selling. Below the put wall, gamma flip at 775.18 is the regime hinge - only -0.439294347% under spot, so dealer buying supports dips today but the cushion is thin. A clean breach of flip reverses dealer flow from mean-reverting to trend-amplifying.
Trade the band, respect the hinge: fade strength into 785.00, lean on 770.00 for first-touch support, cut if flip breaks.
What it means for your trading
The 785.00-770.00 band defines today's microstructure; 775.18 is the single level that flips the regime from dampening to amplifying.
Trading readDeep positive gamma from 770.00 through 785.00 says dealers dampen inside the range - fade spikes toward the call wall, buy drops toward the put wall, and treat 775.18 as the regime hinge.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna sits -$202.94B - the vol-up arrow points to dealer selling, converting a VIX pop at 15.41 into a mechanical delta-shed rather than a cushion. Net charm at -$5.3M adds a modest late-session drift lower, consistent with option decay pulling dealer hedges in a bearish direction into the bell.
The hinge is the gamma flip at 775.1846322494, with spot only -0.439294347% away. Above it, dealer bias reads Supportive - buy weakness, fade strength. Below it, the vanna and charm vectors stop dampening and start amplifying; the whole book flips trend-following.
Trade implication: the carry works while spot holds the pivot, but the cushion is thin, not deep. A VVIX reflex alongside a flip breach is the scenario where -$202.94B stops being a label and starts being a liquidation.
What it means for your trading
Dealer greeks are conditionally supportive - gamma dampens, but vanna and charm are primed to accelerate on a vol pop or a close below 775.1846322494. Trade the pivot, not the regime.
Cross-Asset Confirmation
MOVE prints 110.66, up 3.14%%, while equity vol stays pinned - bond vol is quietly bidding and that is the one divergence worth tracking today. This is a rates-undertone warning, not an equity shock: the SPX complex trades like dealers are still long gamma, but the fixed-income tape is pricing something the equity tape is not.
Sentiment confirms the split. Fear & Greed sits at 44 (Fear) - cautious, not panicked - with QQQ firm at 760.47 and IWM soft at 283.65. Mega-cap gamma anchors the index while small-caps carry the stress, so the cross-asset read is isolated fragility rather than systemic risk-off.
Cross-asset tone resolves Unknown with regime divergence Aligned - SPY and QQQ share positive-gamma posture, IWM is the lone outlier below flip. Trade the index carry, hedge the rates tell, respect that MOVE leads when it diverges this cleanly.
What it means for your trading
Rates vol is the only genuine warning on an otherwise calm equity tape; small-cap weakness is isolated, not systemic, so lean into index short-vol while carrying a MOVE-aware hedge.
Scenario EV
Scoring the full structure set at 30-45 DTE, the Iron Condor wins at 50 - bounded range between call wall 785.00 and put wall 770.00, steep Contango paying the roll, and Low VVIX at 84.65 that keeps tails cheap enough to short both wings.
Directional spreads lag - the put spread prints 36, well behind the condor, because dealers long gamma above flip 775.18 suppress the drift that would pay a one-sided structure. VRP read is Unknown with signal Yellow, so the condor collects the term premium without leaning on a VRP conviction that isn't there.
Hedge posture: carry the put spread as the pre-wired contingency - if SPY breaches 775.18 and the regime flips negative-gamma, the 36-ranked structure becomes the lead trade, not the condor.
What it means for your trading
Top-ranked structure is Iron Condor at 30-45 DTE scoring 50; keep a 36-score put spread on the shelf as the regime-break hedge if 775.18 gives way.
Actionable Summary
BLUF:Iron Condor at 30-45 DTE on SPY/QQQ, bracketed by call wall 785.00 and put wall 770.00. The hinge is 775.1846322494 - above it, dealer bias stays Supportive; a breach flips the entire tape into trend-following. Avoid naked short vol on IWM: Negative Gamma below flip 283.83 is where the regime amplifies moves rather than dampening them.
Watch SPY 775.1846322494 as the regime switch and MOVE 110.66 as the rates tell - bond vol ticking up is the one quiet divergence against equity-vol calm. Carry a defined-risk put spread if VVIX 84.65 jumps or spot breaches flip; the condor pays sideways, the spread pays the tail.
Microsoft AI-pivot upgrade cycle matters because MSFT is the second-largest GEX mover today - a continued re-rating reinforces the QQQ positive-gamma cushion.
NVDA buyback detail matters because reduced free float mechanically compresses realized vol and widens negative VRP - a direct input to the carry trade.
M&A activity plus Microsoft/Wells Fargo upgrades signals corporate risk appetite is intact, which supports the steep-contango regime and short-vol bias.
Oil and bond markets flagged as the week's drivers aligns with MOVE ticking higher - the real tail risk is rates-led, not equity-vol-led.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.40 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 775.18 against a spot of 778.61. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.8% with a volatility risk premium of -0.71%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.41. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime