Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 779.41 with net GEX $10.82B positive - dealers long gamma, moves dampened. Call wall 785.00 is the ceiling, put wall 770.00 the floor, gamma flip at 776.40 sitting just below spot - thin cushion but constructive. Dealers short vanna (net VEX -$198.19B negative) means a vol spike turns them into sellers; charm -$1.5M slightly negative, modestly supportive into expiry. VIX 15.13 with VIX9D 12.04 and VIX3M 17.65 = steep contango, near slope 24.92%%, VRP running negative at -1.22%. QQQ aligned positive gamma at 760.00; IWM diverges at 281.25 with net GEX -$4.07B negative - amplifier regime there. Bottom line: iron condor 30-45 DTE on SPY/QQQ, standard size, avoid IWM short premium until it reclaims 292.58.
SPY and QQQ sit comfortably above gamma flip with dealers long gamma - moves get dampened, mean reversion dominates. IWM remains the fragile outlier, spot 281.25 below flip at 292.58 with net GEX -$4.07B negative. VIX 15.13 in steep contango, VVIX 82.64 low - the carry trade is on.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
779.41
776.40
+0.39%
785
770
763
$10.82B
Long gamma
QQQ
760
751.21
+1.17%
760
700
730
$6.68B
Long gamma
IWM
281.25
292.58
-3.87%
285
280
285
-$4.07B
-
VIX
15.01
15.01
0.00%
20
15
19
-$7.12M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.22
10.44
-1.22
0.69
2.16
0.96
QQQ
14.13
15.12
-0.99
1.69
1.46
1.11
IWM
15.11
11.81
+3.30
1.02
2.47
1.08
VIX
79.18
97.97
-18.79
-124.02
0.33
0.20
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
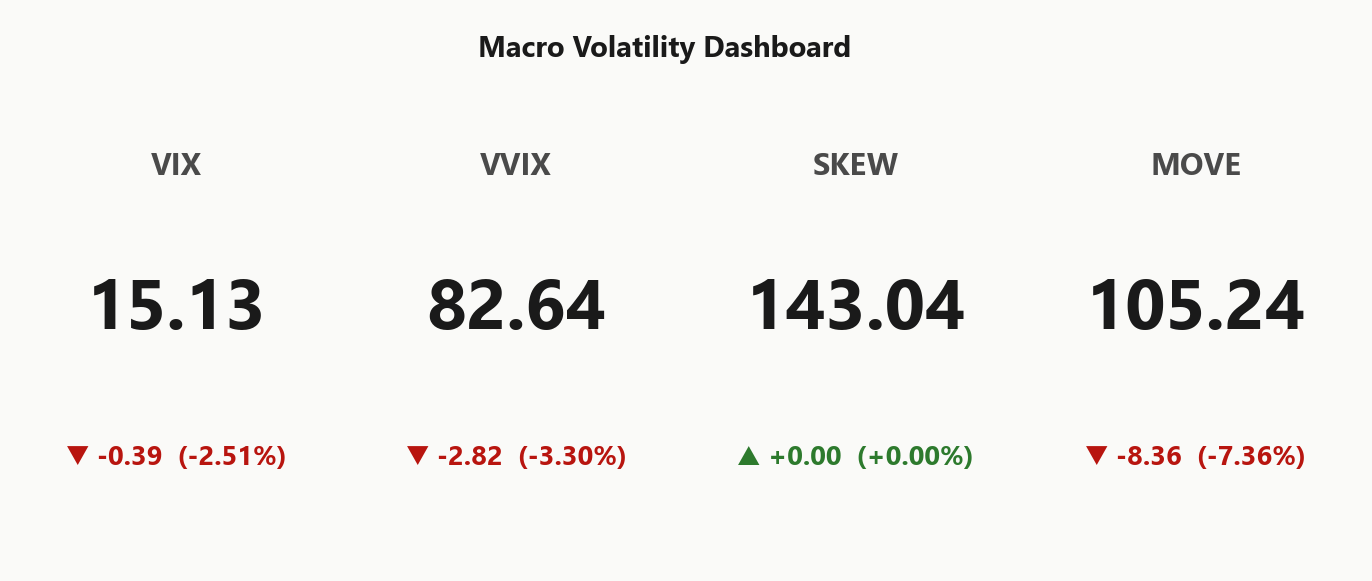
VIX
15.13
-2.51%
VVIX
82.64
-3.30%
SPX
7,818.93
+0.58%
SKEW index
143.04
0.00%
MOVE (bond vol)
105.24
-7.36%
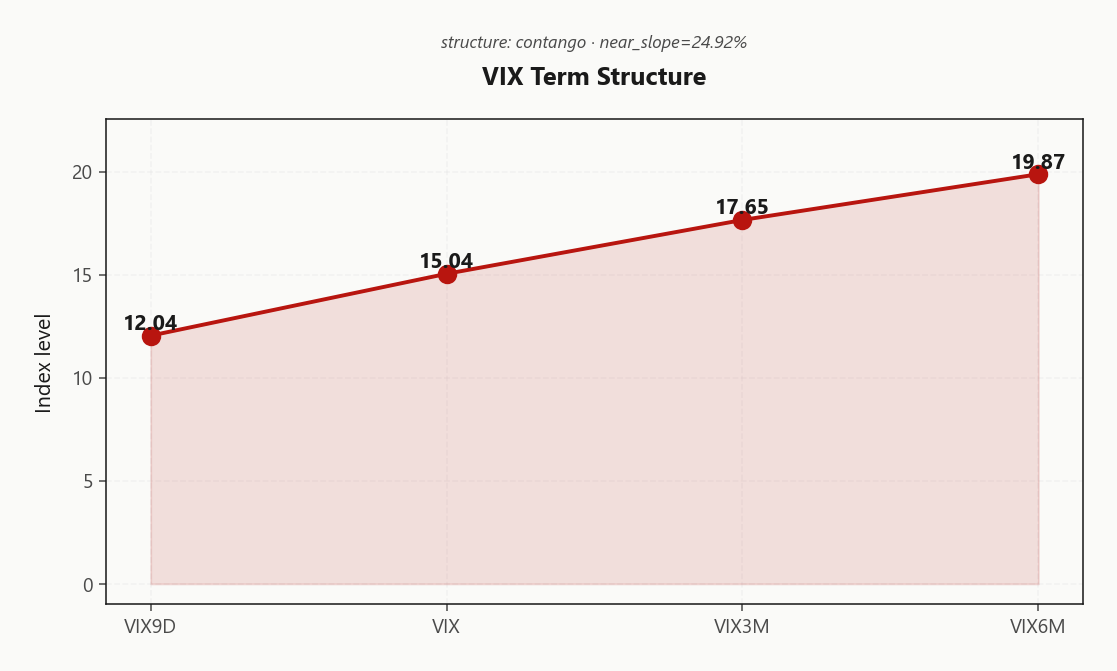
VIX term (9d/30d/3m/6m)
12.04 / 15.04 / 17.65 / 19.87
Steep contango
VVIX / VIX
5.46
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime reads Elevated / Watchful with VIX at 15.13 - not stress, not sleep. The transition matrix gives panic a probability of 0.05 over the next five sessions and drift-to-low at 0.45 over ten; the modal path is persistence, not escalation.
Half-life sits at 15 sessions, which is the operative constraint: carry works here, but the regime is sticky-not-permanent. Short-vol structures earn the roll inside that window; past it, the base rate for mean-reversion to a different state climbs sharply. Elevated-watchful means dealer gamma cushion is doing its job, VIX contango is paying the roll, and tail convexity remains cheap enough to layer on - not fade.
Transition probability toward panic is low, so standard sizing is justified on the recommended structures. The playbook: harvest the carry, respect the half-life clock, keep a cheap VIX call spread on as insurance against the vanna-flip scenario that would convert dealers from dampener to amplifier.
What it means for your trading
Regime is Elevated / Watchful at VIX 15.13 - carry trades sized standard, with a hard clock at the 15-session half-life beyond which the base case for regime persistence degrades.
Trading readVIX down, VVIX down, MOVE down -7.36%% - vol complexes confirming each other lower, no divergence signaling hidden stress; the quiet is coherent.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve sits in Contango from front to back, with VIX9D at 12.04 trading below spot VIX at 15.04 - no event premium being bid into the next two weeks. VIX3M at 17.65 and VIX6M at 19.87 climb linearly with near slope 24.92%%, a clean carry curve without stress stacking in the back.
Forward vol tells the same story more precisely: the 30-60 forward prints 18.8197489356 against 60-90 at 21.8657563327, so the term rolls richer further out and front-dated calendars finance themselves. Regime reads Steep Contango - the structural carry environment where vol sellers get paid for the roll rather than fighting mean reversion.
Edge concentrates in the 30-45 DTE window where the term kink is widest and vanna hasn't yet flipped against short-premium structures. Front-end 0-7 DTE remains too binary to short naked; back-end past 60 DTE gives up the richest roll-down. Sell the belly, not the wings of the curve.
What it means for your trading
Steep contango with VIX9D under spot VIX and a linear climb through VIX6M is a textbook carry setup - short premium in 30-45 DTE captures the richest term kink without stepping into front-end binary risk.
Trading readSteep contango from VIX9D 12.04 to VIX6M 19.87 - carry trade in force, no near-term event premium bid, calendar sellers favored.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV at 9.22% is printing well below realized across the tape - RV5 at 6.3 and RV20 at 10.44 frame a Negative Spread stack where implieds compressed faster than the underlying tape delivered. Options are cheap to recent realized, but that cheapness is doing work: the short-vol book is already positioned, and new sellers are stepping into a crowded trade at marked-down premiums.
VRP at -1.22% confirms the setup - premium sellers are being paid below fair in the near-dated book. Favor longer-dated structures where VRP recovers and the roll compensates; front-end sales demand smaller clips and tighter risk than usual. The IV < RV20 < RV60 ladder says this is a steady low-vol tape, not a vol-crush opportunity.
IWM is the one book where VRP still pays - 3.3% prints positive, the only index premium left on the table. But with spot below gamma flip, the dealer-amplifier risk negates the carry edge. Take the paid-for premium on SPY/QQQ at 30-45 DTE where structure, not yield, defines the trade.
What it means for your trading
IV at 9.22% below both RV5 and RV20 with VRP -1.22% means the short-vol crowd is already paid-in - size modestly below standard and push DTE out to where the roll compensates. IWM VRP 3.3% looks tempting but gamma-flip fragility kills the edge.
Skew Convexity
Quarter-delta skew prints 0.69% with the smile ratio at 1.07% - an ordered put bid rather than a convexity grab. Put 9.99% trades a measured premium to ATM at 9.52%, while the call wing at 9.3% sits suppressed - the crowd isn't paying up for upside, consistent with the positive-gamma complex capping range.
QQQ's smile at 1.13% runs steeper than SPY - tech's left wing is more defensively bid, mirroring the mega-cap gamma stack carrying index stability. IWM's convexity reads differently with smile at 1.06%, consistent with its sub-flip fragility rather than a shared index tape.
Trade implication: left tail isn't cheap enough to buy naked - fund protection through put spreads where the far wing finances the near strike. On the upside, sell call verticals into strength rather than chase; flat call skew means the market pays you to lean against breakouts, not with them.
What it means for your trading
Skew at 0.69% and smile ratio 1.07% describe an ordered defensive bid, not a convexity panic - put spreads fund cleaner than naked wings, and suppressed call skew rewards selling verticals into strength.
Vol-of-Vol Structure
VVIX at 82.64 against spot VIX 15.13 prints a ratio of 5.46 - firmly in the low band. The market is pricing out convexity, not stacking it. With VVIX off -3.3% on the session, the second-derivative bid has drained: no binary jump, no bimodal distribution, no premium being paid for the gap-risk tail that would otherwise punish naked short-vol structures.
This is the clean carry regime. Vol-of-vol in a Low state means the hidden gamma convexity that normally lurks behind cheap VIX prints is absent - dealer vanna books can digest a modest realized bump without a reflexive IV repricing. Sizing guidance reads Standard Size; full-size short premium is green-lit at the index level.
Translation: stop under-sizing the condor. The vol surface is giving you permission to run the book at standard notional into 30-45 DTE. The caveat lives one level up - if VVIX reclaims its higher band, the vanna cushion inverts and this entire posture flips. For now, carry works and the convexity tax is not being charged.
What it means for your trading
Vol-of-vol at Low with VVIX/VIX ratio 5.46 confirms no tail bid priced in - short-premium structures run at Standard Size without stepping over hidden gamma convexity.
Dispersion Spread
Index IV has compressed into the close with SPY ATM IV at 9.22% while QQQ carries a premium at 14.13% - tech is paying up where single-name convexity in NVDA, MSFT, and META keeps the component wing bid. Cross-expiry dispersion reads 3.53 against cross-strike at 35.4, flagging a moderate correlation regime rather than a pure index short-vol setup.
Dispersion signal yellow: correlation is not loose enough for a clean constituent-vs-index trade, and not tight enough to let index hedges absorb a single-name shock. Mega-cap GEX dominance from the MSFT/NVDA/META stack is what's anchoring the positive-gamma complex - if that leadership cracks on a single name, the index cushion thins faster than skew implies.
Preferred expression: sell SPY/QQQ premium at the 30-45 DTE sweet spot where the carry works cleanest, and keep single-name exposure flat or long gamma. Short-gamma on the mega-cap wing is the trap here - index-level is the cleaner vehicle while cross-asset tone stays Aligned.
What it means for your trading
Moderate dispersion with QQQ ATM IV at 14.13% premium to SPY 9.22% argues for index-level short premium over single-name short gamma. Correlation is high enough to make component shorts fragile and low enough that index hedges won't fully offset a mega-cap shock.
Liquidity & Microstructure
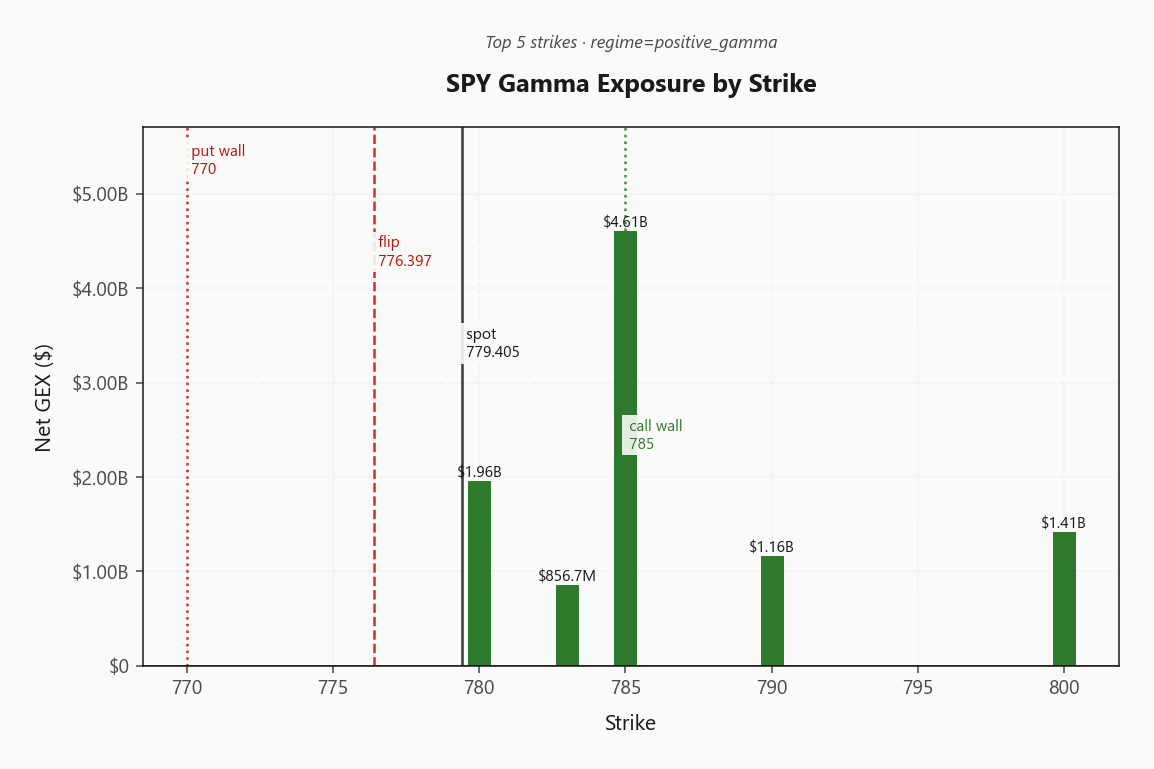
SPY's book is bracketed by the call wall at 785.00 as the ceiling and the put wall at 770.00 as the floor, with the gamma flip sitting at 776.40 - directly beneath spot at 779.41. The cushion is thin: spot rides only -0.3859627289% above the flip. The top strike at 785.00 dominates the stack with net GEX of $4.61B, concentrating dealer long-gamma right at the ceiling.
The highest OI strike sits at 700 - a longer-dated magnet, not today's pin. The actionable level remains the gamma flip: a close through it inverts dealer flow from dampener to amplifier, and the supportive charm bias flips with it.
QQQ carries a wider buffer, with its flip at 751.21 against spot 760.00 - the sturdier short-vol vehicle until SPY earns back distance from its own pivot.
What it means for your trading
SPY's positive-gamma cushion is intact but thin - the flip at 776.40 is the regime switch, and QQQ offers more buffer for premium sales until SPY rebuilds distance.
Trading readMassive dealer long-gamma stacks at 785.00 and 785.00 dampen upside while the put wall at 770.00 absorbs downside - expect tight ranges and intraday fades until spot approaches either wall.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX sits -$198.19B deeply negative - dealers are short vanna, which flips them into delta sellers the moment implied vol repr ices higher. That is the fragility beneath today's calm tape: positive gamma dampens spot moves, but a VIX break above the mid-teens inverts the dealer response fast and turns the cushion into an accelerant.
Charm reads -$1.5M, slightly negative and modestly supportive into the close - flow is helping dealers hold the range rather than fighting it. Current bias is Supportive, pivot type Gamma Flip with the regime switch sitting at 776.3967871927. Cross that level and the sign of dealer response inverts; respect it, and the carry trade keeps paying.
Trade implication: the vanna book is the hidden tail, not the gamma book. Short-premium structures work while VIX holds 15.13, but overlay cheap VVIX convexity - vol-of-vol at 82.64 makes the hedge economic rather than aspirational.
What it means for your trading
Dealers long gamma but short vanna - the tape is supportive at Supportive bias while spot holds above 776.3967871927, but a VIX break higher inverts the regime and turns dealers into sellers. Carry the trade, hedge the vanna.
Cross-Asset Confirmation
MOVE at 105.24 is unwinding hard, down -7.36%% - rates vol is no longer the marginal driver of equity vol. That matters: when MOVE leads lower and VIX follows, the quiet is coherent rather than complacent. Fear & Greed at 48 prints Neutral, offering no sentiment extreme to fade in either direction.
The index complex is Aligned at the top: QQQ at 760.00 sits in positive_gamma alongside SPY, with dealers long gamma dampening intraday impulses. IWM at 281.25 is the divergence - spot below its gamma flip, net GEX negative, dealer flow in amplifier mode. Cross-asset tone reads Unknown, which fits the picture: small-cap fragility isolated, not systemic.
This is not a credit shock setup. MOVE collapse plus neutral sentiment plus aligned mega-cap gamma says carry the index book, keep IWM short-premium exposure flat, and let the small-cap wing stay the designated break candidate.
What it means for your trading
Mega-cap gamma aligned and rates vol unwinding - the quiet is confirmed across asset classes, with IWM the isolated fragility rather than a leading indicator of broader stress.
Scenario EV
Scenario EV ranks Iron Condor top of the book at score 46, with the put spread trailing at 31. The setup is textbook range-bound carry: SPY positive-gamma cushion holds spot above the flip at 776.40, VIX term structure sits in Contango, and VVIX at 82.64 keeps vol-of-vol signal Low - no hidden convexity to step over.
Optimal expression: iron condor on SPY wings 770.00P / 785.00C at 30-45 DTE, where the term kink is widest and vanna hasn't flipped. QQQ aligned at 760.00 stacks the same trade. Sizing per vol-of-vol guidance: Standard Size. The lower put-spread score reflects SPY's negative VRP at -1.22% - directional premium sales get paid less than fair.
Avoid IWM short premium outright: spot 281.25 below gamma flip 292.58 with net GEX -$4.07B means dealer flow amplifies rather than dampens - asymmetric downside against the carry.
What it means for your trading
Iron condor 770.00/785.00 on SPY at 30-45 DTE, standard size - the positive-gamma, steep-contango, low-VVIX trifecta pays carry cleanly. Skip IWM; its sub-flip regime inverts the dealer response.
Actionable Summary
Trade:Iron Condor on SPY and QQQ at 30-45 DTE, standard size. SPY 770.00P / 785.00C captures the dealer long-gamma cushion while VIX 15.13 in Contango pays the carry. QQQ aligned positive-gamma at 760.00 offers the sturdier short-vol vehicle given its wider buffer above gamma flip 751.21.
Watch: SPY gamma flip at 776.3967871927 - spot sits only -0.3859627289% above, a thin cushion. A close below flips dealer flow from dampener to amplifier and inverts the regime. Net VEX -$198.19B negative means a VIX break higher turns dealers into delta sellers fast; vanna is the fragility, not gamma.
Avoid: IWM short premium while spot 281.25 sits below its flip at 292.58 - asymmetric downside with dealer amplification. Hedge: modest VIX call spread; VVIX 82.64 prices convexity cheaply. Regime Elevated / Watchful, size standard, don't marry the carry past 15 sessions.
What it means for your trading
Positive-gamma complex plus steep contango green-lights Iron Condor at 30-45 DTE, but the SPY gamma flip at 776.3967871927 is the regime switch - defend it, and skip IWM short premium entirely while it trades below 292.58.
S&P at record highs while market is oversold maps directly onto today's positive-gamma-plus-neutral-sentiment setup - explains why mean reversion dominates
Oil slip on Mideast supply reassurance cross-checks the geopolitical narrative - if oil AND MOVE both fall, equity vol stays suppressed
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.01 with a Contango term structure. The Fear & Greed index reads Neutral, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 776.40 against a spot of 779.41. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.22% with a volatility risk premium of -1.22%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.13. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime