Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY sits at 770.61 with net GEX $1.53B - dealers long gamma, moves dampened, mean-reversion favored intraday. Call wall at 785.00 caps upside, put wall at 767.00 is the first line of support, max pain 760.00; charm pivot sits at 767 with bias Neutral. QQQ confirms with flip at 748.28 and spot comfortably above - tech is the stable leg. IWM diverges hard with net GEX -$4B: dealers short gamma, moves amplified, VRP rich at 4.67%. VIX 15.89 in steep contango (slope 32.84%%), VVIX 88.87 subdued - carry is on and vol-of-vol is not fighting the short-vol trade. MOVE at 113.52 jumped, flagging bond-market unease that could spill into equities if it extends. Bottom line: fade SPY strength into 785.00, respect IWM downside against the amplified-dealer regime, and route short-vol premium sales to IWM over SPY where it pays.
SPY positive gamma intact at $1.53B with VIX 15.89; IWM negative gamma lead divergence
SPY and QQQ hold positive gamma with dealers long into the open, while IWM remains firmly below its flip with net GEX -$4B - the day's divergence trade. VIX 15.89 with steep contango and VVIX 88.87 keeps vol sellers in control, but IWM's rich VRP at 4.67% says the premium is not in the index you'd default-sell.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
770.61
-
-
785
767
760
$1.53B
-
QQQ
752.73
748.28
+0.60%
760
740
720
$5.26B
Long gamma
IWM
280.51
291.35
-3.72%
285
280
285
-$4.00B
-
VIX
15.89
16.11
-1.38%
20
15
19
-$24.03M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.50
10.32
+0.18
1.99
2.06
0.47
QQQ
15.55
14.98
+0.57
2.96
1.38
0.94
IWM
16.07
11.40
+4.67
2.03
2.45
1.62
VIX
77.08
99.53
-22.45
-122.05
0.32
0.16
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
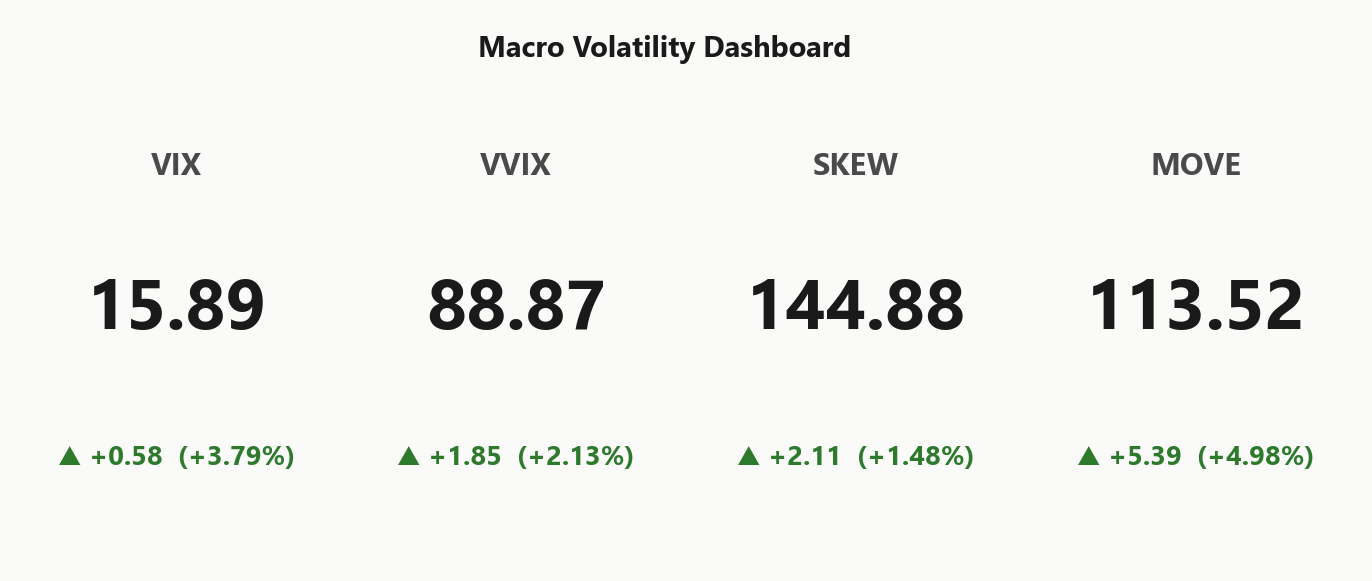
15.89
+3.79%
VVIX
88.87
+2.13%
SPX
7,733.84
+0.14%
SKEW index
144.88
+1.48%
MOVE (bond vol)
113.52
+4.98%
VIX term (9d/30d/3m/6m)
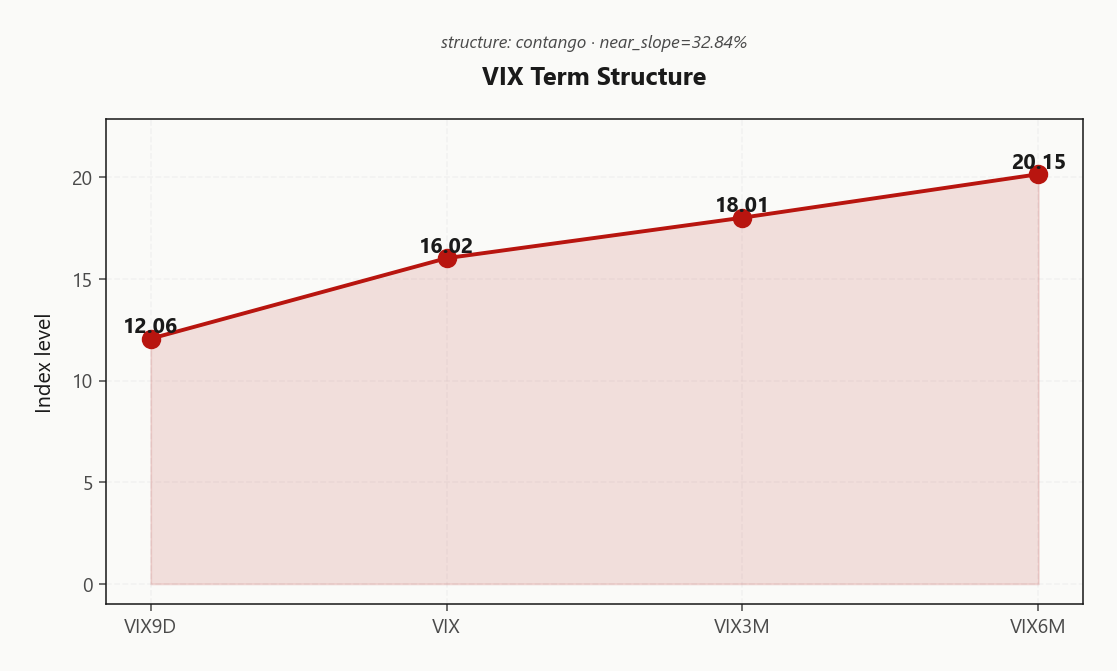
12.06 / 16.02 / 18.01 / 20.15
Steep contango
VVIX / VIX
5.59
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime prints Elevated (Elevated / Watchful) with VIX at 15.89 - elevated enough to respect, not panicked enough to fade. Half-life of 15 sessions says this state is sticky; the market does not rotate out of this bucket on a single-session impulse, and positioning should assume the backdrop persists into next week.
Transition math backs the stance. Probability of a jump to panic over the next five sessions sits at 0.05 - low, but non-zero, enough to keep tail hedges in the book rather than monetised. The base case is a drift lower: ten-session probability of a return to the low-vol bucket runs at 0.45, the single most likely path from here.
Signal yellow - trade within the regime, do not fade it. Short-vol structures stay sized standard per Standard Size, routed to IWM where VRP 4.67% actually pays; naked SPY vol-sell is under-compensated against this half-life. The regime is the floor the day trades off, not the trade itself.
What it means for your trading
Elevated-but-sticky regime at VIX 15.89 with 15-session half-life - base case is mean-reversion toward low-vol (0.45 over 10 sessions), panic tail 0.05 stays in the book. Trade inside the regime; do not short its persistence.
Trading readVVIX 88.87 calm while MOVE 113.52 jumps and SKEW 144.88 stays bid - rates-side pressure is the quiet divergence to watch.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Steep Contango from VIX9D 12.06 through VIX 16.02, VIX3M 18.01, and VIX6M 20.15 - monotonic, uninterrupted, and paying carry at every tenor. Front-to-3M slope at 32.84%% is the kind of print that keeps roll-down trades in the money without having to time a vol spike.
Front-month VIX future 18.01 against spot 16.02 leaves basis at 12.42%%, and forward 30-60 at 18.9266993953 underwrites the carry trade cleanly - forwards sit above spot but below the panic band, so sellers get paid without buying a tail. Section signal is green, regime label Steep contango - vol sellers favored, and vol-of-vol is not fighting it.
Edge concentrates in the 21-30 DTE pocket where the forward curve pays most per unit of theta risk. Avoid the very front where 59.7%% zero-DTE share injects chop, and don't push past the three-month node where forward 60-90 at 22.0835889293 starts flagging a vol floor. Route structures to the belly, not the wings.
Trading readSteep contango - vol sellers favored - carry is live and the market is not pricing imminent stress; vol sellers favored but respect the MOVE tell.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 10.5% prints barely above twenty-day realized of 10.32, leaving a VRP of 0.18% - the index is paying almost nothing for insurance it isn't using. Naked short vol in SPY is a low-pay, same-risk trade here; if the vol-sell is the thesis, demand low-cost long gamma as the hedge or re-route the premium capture to a richer standalone venue.
QQQ carries a modestly thicker cushion at 0.57% - tech is paying for its dispersion, but not enough to anchor a book around. The actual premium pocket is IWM: ATM IV 16.07% against HV20 of 11.4 leaves VRP at 4.67%, the richest standalone spread in the complex and the preferred venue for condors, strangles, and put-spread sales at the 21-30 DTE pocket.
VIX itself prints negative VRP at -22.45% - short vol-of-vol is the live tape, which reinforces the carry-on, size-standard read and keeps the IWM short-vol routing intact.
What it means for your trading
Route premium sales to IWM where VRP sits at 4.67%; SPY's 0.18% is too thin to carry naked short vol, and VIX's own negative VRP keeps the short-vol-of-vol tape live.
Skew Convexity
The quarter-delta skew prints ordered, not panic-steep. SPY smile ratio at 1.18% with put-wing 13.25% over ATM 12.25% and call-wing fading to 11.26% - downside bid, upside dull, no left-tail blowout.
QQQ skew at 2.96% runs steeper than SPY 1.99% - tech is paying up harder for downside, consistent with the long-gamma complacency sitting above it. IWM skew 2.03% with call wing 18.24% keeps the upside un-inverted, so small-cap downside spreads out-earn naked puts here.
Section signal yellow at label Skew Steep - ordered today, but MOVE at 113.52 is the tripwire. If rates vol keeps extending, the put wing steepens first in QQQ.
What it means for your trading
Skew is bid but ordered - buy protection in spreads, not outright puts, and watch QQQ's steeper wing as the first tell if MOVE pushes the complex toward panic-steep.
Vol-of-Vol Structure
VVIX prints 88.87 against VIX 15.89, with the ratio at 5.59 - Low and well below any jump-risk threshold. Vol-of-vol is not amplifying the tape; the second derivative of fear is dormant while the first derivative drifts.
With the ratio sitting where it is, there is no bimodal pricing in the VIX options complex - no fat-tail hedge bid distorting the surface, no gamma-of-vol kink to respect. Short-vol structures can be built against clean convexity rather than against a hidden long-wing cost. Sizing guidance reads Standard Size: do not haircut the book for a vol-of-vol shock that is not being priced.
Signal green, label Low. This is the quietest input in the stack and the one that frees the carry trade elsewhere - the forward-vol geometry and VRP routing calls both get to run at full size because the vol-of-vol layer is not fighting them.
Index IVs are stacked in a narrow band this morning - SPY at 10.5%, QQQ at 15.55%, IWM at 16.07% - a cluster that argues correlation drag is muted and the dispersion premium between index and single-name vol is not where the money is today.
What does stand out is IWM's standalone VRP at 4.67%, the richest premium pocket in the complex and a clean tell that index-level short vol under-prices small-cap idiosyncratic risk. Selling SPY index vol into this tape collects a thin premium while sitting long the amplified-dealer regime; routing the same structure into IWM pays the actual risk being underwritten.
Section signal prints Moderate - not a mandate to lean in, but a flag that the dispersion trade is live in where you sell, not whether. Prefer single-index IWM short vol over broad SPY sales for the duration of this regime.
What it means for your trading
Index IV cluster is tight but IWM's VRP at 4.67% says the real premium sits in small-caps; route short-vol structures to IWM over SPY while the dispersion signal reads Moderate.
Liquidity & Microstructure
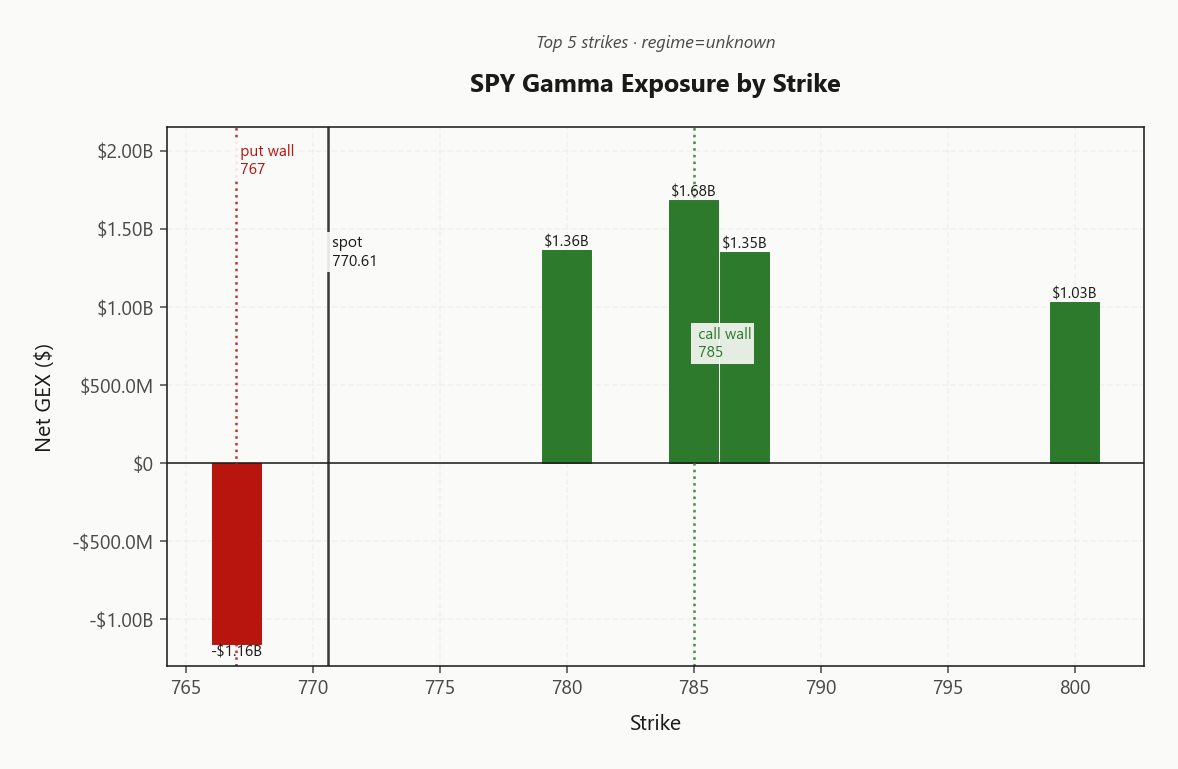
SPY's book is deep where it counts: OI stacks heaviest at 700, but the top gamma magnet sits at 785.00 with GEX $1.68B - the single strike doing the heavy lifting on intraday dampening. The call wall at 785.00 caps the overhead, and the gamma-flip engine returned Stored Sign Mismatch, so lean on wall structure rather than a disputed pivot.
The put wall at 767.00 is the first fade line, co-located with the derived charm pivot at 767 (Put Wall) - spot sits -0.4684600511% away with bias Neutral. Treat that level as a tripwire, not just a target: a break reroutes dealer flow and strips the dampener.
Zero-DTE prints 59.7%% of SPY total GEX - intraday chop around pin levels is elevated and late-session squeezes are high-noise. Trade the range between walls, not through them.
What it means for your trading
SPY's wall structure - call cap at 785.00, put floor at 767.00 coinciding with the charm pivot at 767 - is the operative map today, since the gamma-flip engine returned Stored Sign Mismatch. Zero-DTE share of 59.7%% keeps pin-level chop elevated into the close.
Trading readSPY gamma clusters heavily above spot into 785.00 and the top GEX magnet at 785.00 - dealers dampen upside here and cushion dips into the put wall at 767.00; trade range, not breakouts, until a wall gives.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY net VEX prints -$106.29B - deeply negative, which means vanna is hostile: any extension in VIX accelerates dealer-sell delta and will fight the long-gamma dampener that otherwise anchors the tape. The long-gamma frame is conditional, not unconditional.
Charm pressure is the quieter input. Net CHEX at -$2.1M is modest, so time-decay flows alone will not reroute the book - but they stack with vanna if vol lifts. The derived charm pivot sits at 767, flagged as a Put Wall, with current bias Neutral. Spot sits -0.4684600511% from that level - close enough that late-day flows can swing either way.
Trade implication: treat the put wall as a tripwire, not just a downside target. A break below 767 inverts dealer flow into sell-the-dip, and the hostile vanna reading means a coincident VIX pop would compound it. Above the pivot, mean-reversion mechanics stay intact.
What it means for your trading
Vanna is hostile at -$106.29B while charm -$2.1M is modest - the long-gamma dampener holds only if VIX stays contained; the Put Wall at 767 is the single level that reroutes dealer flow.
Cross-Asset Confirmation
MOVE at 113.52 jumped 4.98%% while VIX moved only 3.79%% - rates vol is leading equity vol into the open, and that order of operations matters: bond-market stress has front-run every meaningful equity repricing this cycle. Treat the MOVE print as the forward tell, not the confirming one.
Fear & Greed sits at Fear (40) - cautious but a long way from capitulation, so sentiment is contrarian in neither direction. QQQ at 752.73 holds above its flip while IWM at 280.51 trades fragile beneath its own; regime divergence prints True, confirming the split-tape read rather than contradicting it.
Tone resolves to Unknown - isolated-equity-stable with small-cap fragility, not a credit shock. Route hedges to IWM, keep SPY/QQQ exposure within the long-gamma dampener, and let MOVE dictate when the equity complex is forced to catch up.
What it means for your trading
Rates vol is leading equity vol with MOVE up 4.98%% against a muted VIX tick, and Fear & Greed at 40 keeps sentiment cautious rather than capitulated. The SPY/QQQ-vs-IWM regime split confirms isolated small-cap fragility, not a broad credit event - hedge in IWM, respect the MOVE tell.
Scenario EV
The scenario engine returned Unknown with VRP assessment Unknown and a Red signal - treat the automated score as noisy and lean on the composite read instead.
Composite routing is clean: short-vol structures favored in IWM, where VRP prints 4.67% - the richest premium pocket in the complex. The DTE sweet spot sits at 21-30, aligning with the forward-vol carry window and keeping structures clear of near-dated 0DTE chop. Avoid naked SPY vol-sell: VRP is too thin to justify the delta risk when IWM pays materially more for the same vega.
Sizing: Standard Size per the VVIX read - vol-of-vol is not amplifying, so no haircut is warranted on structures routed to the optimal pocket.
What it means for your trading
Engine output is Red and advisory only - the live edge is IWM short vol at 21-30 where VRP 4.67% actually pays, not naked SPY sales.
Actionable Summary
Bottom line: the day's trade is the SPY long-gamma versus IWM short-gamma divergence. Fade SPY strength into the 785.00 call wall where dealers dampen upside, and respect the 767.00 put wall with the charm pivot stacked at 767 as the tripwire below. Regime reads Elevated / Watchful - trade within it, not against it.
Route short-vol premium to IWM, where VRP prints 4.67% - the richest pocket in the complex - at the 21-30 DTE window. Avoid naked SPY vol-sells: VRP at 0.18% is too thin to pay for the gamma risk you'd carry.
Watch MOVE at 113.52 - rates vol is the forward tell. A continued jump there is the signal that equity vol follows and the long-gamma dampener gives way.
What it means for your trading
Fade SPY into 785.00, defend 767.00, route short vol to IWM at 21-30 DTE where VRP prints 4.67%, and treat MOVE at 113.52 as the leading-edge risk signal.
Supreme Court headline risk and midterm-driven Senate control probability both re-rate political uncertainty, a slow-burn input into the risk premium that sits behind VIX.
USS George Washington / Iran war coverage keeps the Middle East risk layer live - not a session catalyst by itself but part of the standing bid for puts.
Alleged UK terror plot linked to Iran deepens the geopolitical overhang - supports the ordered-skew-not-cheap read in the complex.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.89 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $1.53B. The gamma flip sits at N/A, with the call wall at 785.00 and the put wall at 767.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 770.61. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.5% with a volatility risk premium of 0.18%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.89. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime