Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
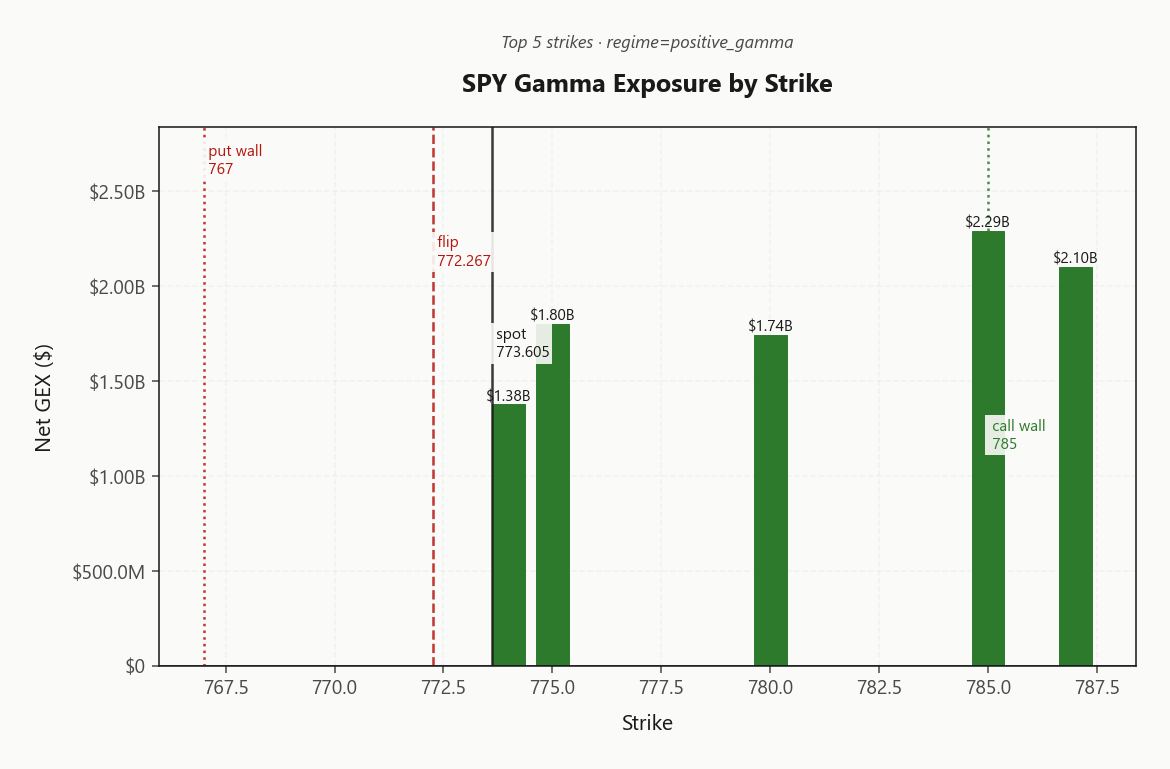
SPY trades 773.61 in Positive Gamma with net GEX $9.03B - dealers long gamma, moves get dampened and mean-reversion wins. Call wall 785.00 caps upside, put wall 767.00 supports, gamma flip 772.27 sits just below spot - thin cushion but still constructive. QQQ aligned in positive gamma, flip 748.08 with call wall 755.00; IWM diverges to negative gamma, flip 293.35 above spot - small caps amplify any index wobble. Dealer vanna -$120.03B is deeply negative, so a vol pop forces delta selling into weakness; charm skew into Friday close pressures dealers to sell. VIX at 15.51 with VVIX 85.66, term in Contango (20.02%% near slope) - vol sellers still get paid, but IV-RV spreads show SPY ATM 9.77% slightly below 20d RV 10.37, so premium is thin on SPX. IWM VRP 3.18% is the standout richness - that's where the carry lives. Bottom line: iron condor on SPX/SPY, DTE 30-45, standard size per VVIX regime; AVOID selling IWM wings naked given negative gamma amplification below 293.35.
SPY sits above 772.27 with dealers long gamma, dampening moves while QQQ aligns in the same regime. IWM diverges into negative gamma with spot below flip, meaning any index weakness amplifies through small caps first. VIX term structure in Contango with VVIX low keeps short-vol carry live - size standard, favor index condors over single-name.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
773.61
772.27
+0.17%
785
767
760
$9.03B
Long gamma
QQQ
753.78
748.08
+0.76%
755
740
725
$7.09B
Long gamma
IWM
283.19
293.35
-3.46%
285
280
285
-$2.86B
Short gamma
VIX
15.51
15.51
0.00%
20
15.50
19
-$10.53M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.77
10.37
-0.60
2.24
2.05
0.92
QQQ
14.49
15.03
-0.54
2.81
1.44
1.34
IWM
14.72
11.54
+3.18
2.27
2.45
1.20
VIX
74.09
97.92
-23.83
-118.71
0.32
0.40
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.51
+1.31%
VVIX
85.66
-1.56%
SPX
7,765.02
+0.55%
SKEW index
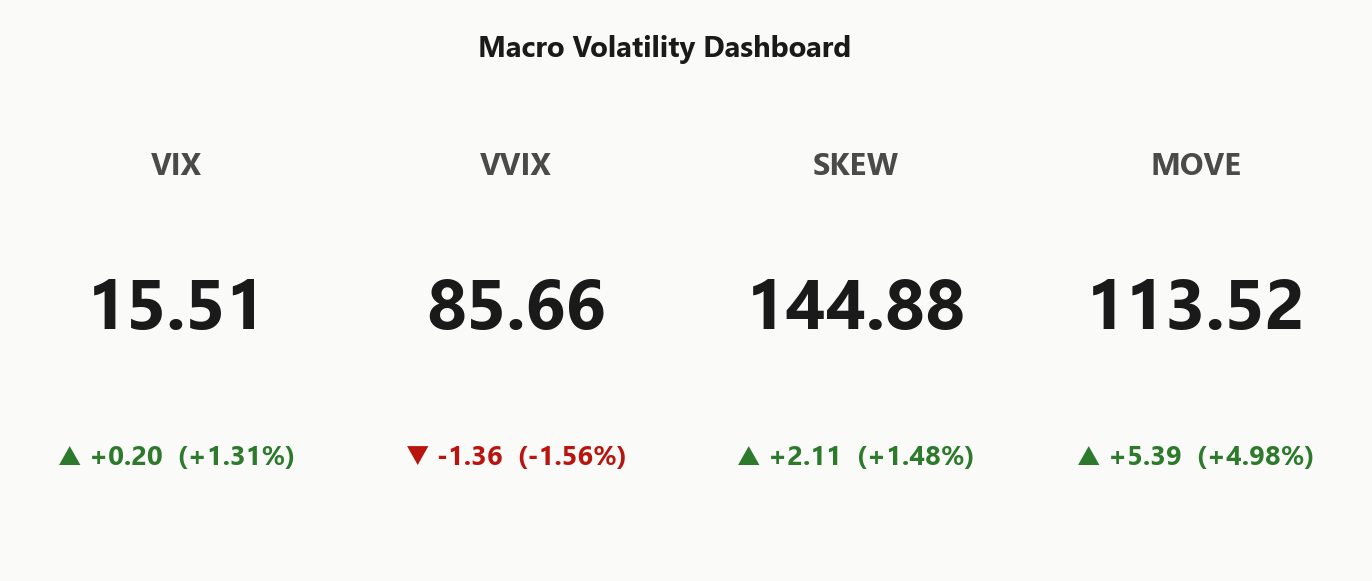
144.88
+1.48%
MOVE (bond vol)
113.52
+4.98%
VIX term (9d/30d/3m/6m)
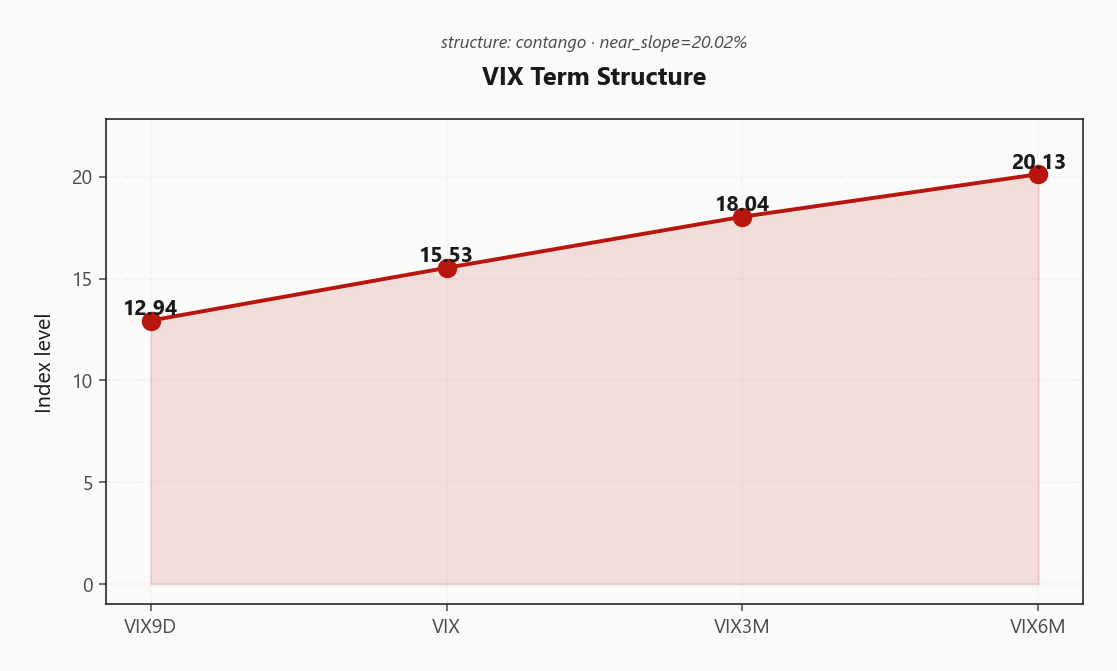
12.94 / 15.53 / 18.04 / 20.13
Steep contango
VVIX / VIX
5.52
Low
Regime
Elevated / Watchful
Regime Assessment
The tape sits in Elevated / Watchful with VIX at 15.51 - neither panic nor complacency. The 5-session transition probability to a panic regime reads 0.05, so the market is not pricing an acute shock; by contrast, the 10-session probability of decay toward low-vol prints 0.45, meaningfully higher. Direction of drift favors compression, not expansion.
Half-life sits at 15 sessions - call it roughly three weeks of persistence. This regime is sticky, not snapping: it leaks, it does not break. Watchful posture earns carry while the clock runs.
Sizing stays standard until the panic transition probability clears the twenty-percent threshold. Short-vol structures remain in play, condor risk-reward intact, and the recommended trade still scores 50 at the 30-45 DTE window. Flip the switch only on a VVIX pop or a break of 772.2672579983.
What it means for your trading
Regime is Elevated / Watchful with half-life 15 sessions - sticky and leaning toward low-vol decay, not shock. Hold standard size, harvest carry, re-rate only if panic transition probability clears the twenty-percent gate.
Trading readVIX contained but MOVE jumping intraday - rates vol repricing while equity vol sleeps is the classic early-warning divergence to watch.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The curve prints Contango with VIX9D at 12.94 sitting well under spot VIX 15.53 and VIX3M stacked above at 18.04. Translation: zero near-term event bid, structural Steep Contango carry live for vol sellers. The market prices calm now and builds term premium for the Nov-Dec event cluster - classic forward-hump geometry.
Forward 30→60 implied prints 19.1721660226, which is where the richest premium actually sits. Front-month is thin; the edge lives one tenor out. Sweet spot for structure sales is 30-45 DTE - far enough to collect the term kink, close enough to decay before the event window.
Trade is simple: fade the front, hold wings further out to harvest term premium decay. The regime-breaker is a VIX9D/VIX cross - any flip to backwardation inverts the whole structure and the carry trade dies instantly. Watch that cross before anything else.
What it means for your trading
Steep contango with VIX9D under spot and VIX3M stacked above makes 30-45 DTE the clean short-vol tenor. Backwardation break at the VIX9D/VIX cross kills the trade - that's the only line that matters.
Trading readSteep contango with VIX9D well under spot VIX = no near-term event bid, structural carry live for vol sellers through the 30-60 DTE window.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV prints 9.77% against 20-day realized 10.37, stamping VRP at -0.6% - index options trade cheap-to-realized. Short-vol on SPX pays thin here; the premium you collect barely covers what the tape is actually delivering. QQQ VRP -0.54% runs the same direction - tech vol bid above where realized justifies, so naked single-name selling in the mega-cap complex is a losing carry trade this week.
IWM is the standout. VRP 3.18% prints genuinely rich - small-cap options carry real premium over what IWM is actually delivering, and that's where the harvest lives. The regime divergence (Negative Gamma below flip 293.35) is exactly why: realized bursts higher on amplification, option sellers get paid for the risk they're genuinely taking.
60-day RV 11.09 sits above 20-day 10.37 - realized is decelerating. The forward path argues for mean-reversion in RV, which under normal regime would widen VRP back out. For now, structure the condor on IWM wings, keep SPX exposure light on premium and heavy on term.
What it means for your trading
SPY VRP at -0.6% with QQQ at -0.54% leaves index short-vol thin; IWM VRP 3.18% is the real carry - favor small-cap structure over mega-cap for premium harvest.
Skew Convexity
SPY quarter-delta skew prints 2.24% against a smile ratio of 1.23% - put wing at 12.14% paying a measured premium over ATM 10.49%, call wing at 9.9% trading below ATM. That's ordered hedging, not scramble. Downside bid is live but not panic-priced, and the call side is dead - zero upside tail conviction.
QQQ skew runs steeper at 2.81%, consistent with tech vol being bid more aggressively into the Nov-Dec event cluster. The flat SPY call wing is the trade-structuring problem: condor call wings don't finance themselves here, so premium capture leans entirely on the put side.
Translation: spread downside risk via put spreads rather than selling naked puts - the skew doesn't pay enough to carry pure short-wing exposure. Watch skew widening as earnings and FOMC land; a steepening SPY term skew is the first tell that the ordered hedging regime is breaking into something less orderly.
What it means for your trading
SPY skew at 2.24% is ordered-hedge, not panic - put spreads over naked puts, and QQQ's steeper 2.81% says tech is the richer downside premium harvest. Flat call wing kills condor call financing; lean structures to the put side.
Vol-of-Vol Structure
VVIX at 85.66 against VIX 15.51 prints a ratio of 5.52 - a Low vol-of-vol regime with no jump bid baked into the surface. The tape is pricing linear vol moves, not a bimodal outcome, which is the green light short-vol structures need before they size up. Sizing guidance reads Standard Size; no defensive half-size required here.
Flat vol-of-vol matters more than the headline VIX print. When VVIX stays contained alongside Contango, the convexity premium that would otherwise poison short-strangle math simply isn't there - dealers aren't paying up for the gap-risk wing. That shifts the trade preference cleanly toward iron condor over strangle, since the defined wings cost little when jump risk is unpriced and the term curve carries you.
Trigger to flip the regime: a VVIX pop through triple digits reprices every short-vol structure in the complex and forces size down to half. Until that break, carry the condors at 30-45 DTE and keep the wings tight.
What it means for your trading
Vol-of-vol prints Low at a VVIX/VIX ratio of 5.52, confirming Standard Size on short-vol structures and favoring iron condors over strangles given no jump premium in the surface.
Dispersion Spread
Index VRP sits compressed with SPY ATM IV at 9.77% printing VRP -0.6% and QQQ VRP -0.54% - thin edge on the core complex. IWM VRP at 3.18% stands apart as the richness in the book, and single-name premium through the mover complex runs richer than the index core. Correlation reads moderate, which is the dispersion tell: index hedges will not catch idiosyncratic single-name moves cleanly.
Translation for structure selection - index short-vol is the cleaner trade, single-name short-vol is the dirtier one into the Oct-Nov earnings cluster. The dispersion book writes itself: long single-name vol, short index vol, with the carry financed by the SPY/QQQ VRP compression against the richer single-name wings.
Favor SPY/SPX condors over naked single-name premium harvest. Earnings prints lift single-name realized through November, and selling that gamma into event dates is where short-vol books have historically bled. Keep the index as the premium engine, let single names run.
What it means for your trading
Index VRP compressed to -0.6% on SPY and -0.54% on QQQ while IWM VRP at 3.18% and single-name premium run richer - classic dispersion setup. Short index vol via SPX/SPY condors, hold single-name vol long through the earnings cluster.
Liquidity & Microstructure
SPY anchors the book with spot 773.61 sitting a hair above the gamma flip at 772.27 - a thin positive-gamma cushion that keeps dealers stabilizing but offers almost no margin before flow inverts. The call wall at 785.00 is the day's magnetic ceiling, with top-strike net GEX of $2.29B stacked at 785.00 - serious dealer long gamma overhead that caps any rally and forces supply into strength.
Beneath spot, the put wall at 767.00 is the structural floor and the highest-OI strike sits at 700, with max pain at 760.00 exerting pin pressure into Friday expiry. 0DTE at 42.6% of total gamma means intraday chop dominates - dealer rebalancing fights every directional push within the session, and mean-reversion wins unless the flip breaks.
What it means for your trading
Above 772.27, dealers buy weakness and sell strength - fade extensions toward 785.00, lean on 767.00 as support. A break below the flip inverts the whole flow regime, so size short-vol structures to the cushion, not the comfort.
Trading readDeep positive gamma clusters above spot cap upside at the call wall while dealers' short-dated long-gamma dampens intraday swings - fade strength into the wall and respect the thin cushion above the flip.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY net VEX at -$120.03B sits deeply negative - a vol pop forces dealer delta selling, accelerating any downside through the tape. Charm at -$5.5M skews dealers to sell into Friday's close, so expect a late-session fade pressure even without a fresh catalyst.
The gamma flip at 772.2672579983 is the line. Current bias reads Supportive, but spot sits only -0.1729231328 above the pivot - a thin cushion for a regime that flips from stabilizing to accelerant on a single meaningful tick lower.
Hold the flip through Friday and the dampening structure holds, call wall caps upside, mean-reversion wins. Break it and negative gamma amplification takes over, with vanna and charm both pushing the same direction into weakness. Trade the regime that's live - don't anchor to one that's one print away from inverting.
What it means for your trading
Dealer positioning is Supportive for now but structurally fragile: deeply negative VEX plus charm skew means any break of 772.2672579983 flips the regime from dampener to accelerant into Friday's close.
Cross-Asset Confirmation
MOVE prints 113.52 up 4.98%% intraday while equity vol stays contained - rates are repricing before stocks notice. Fear & Greed at 43 reads Fear, sentiment lagging a tape that keeps grinding. The credit-rates channel, not equity flow, is where the next regime shift originates.
SPY and QQQ (753.78) sit aligned in positive gamma; IWM (283.19) diverges into negative gamma below its flip. Cross-asset divergence reads Aligned at the index core, but small caps are the outlier and the fragile tail.
Lead story is small-cap fragility, not an index break. Watch IWM for the first crack; watch MOVE for the second. Mega-cap dampening holds until one of those two gives.
What it means for your trading
Rates vol up 4.98%% against sleepy equity vol is the early-warning divergence - IWM short-gamma is the amplifier if credit cracks first.
Scenario EV
Scoring routes the book to Iron Condor at 50, with the sweet spot at 30-45 DTE. Contango through the term with VVIX at 85.66 and SPY anchored in Positive Gamma above the flip at 772.27 gives the structure what it needs: term premium to collect, capped tail, dampened realized. Yellow, not green - decent carry, not a layup.
Put spread sits at 37 as the hedge alternative if the 772.2672579983 flip cracks and Positive Gamma inverts to accelerant. Sizing stays standard - VVIX in Low territory with ratio 5.52 prices no jump risk, so no defensive halving. The real edge isn't SPX wings; it's 3.18% on the call side where VRP actually pays.
What it means for your trading
Iron condor at 30-45 DTE scores 50 - yellow carry on SPX, with IWM call wings carrying the real premium edge; put spread at 37 is the regime-crack hedge if 772.2672579983 breaks.
Actionable Summary
Trade:Iron Condor on SPX/SPY at 30-45 DTE, standard size - VVIX at 85.66 confirms Standard Size. Harvest the wings on IWM where VRP prints 3.18% - richest premium-to-realized in the complex while SPY VRP -0.6% runs thin against 20d RV 10.37.
Watch: SPY flip at 772.2672579983 with spot 773.61 cushioned only -0.1729231328% - break below reverses dealer mechanics from stabilizing to accelerant given net VEX -$120.03B. Call wall 785.00 caps upside; max pain 760.00 pins into Friday.
Avoid: naked IWM downside below 293.35 - negative-gamma amplification; naked call sales above 785.00 where term premium hasn't rebuilt; long-vol single-name chases with QQQ VRP -0.54% already bid. Hedge: hold a cheap VIX call wing into the Nov event cluster - MOVE up 4.98%% flags rates vol as the next regime-mover, not equity flow. Regime reads Elevated / Watchful with half-life 15 sessions.
What it means for your trading
Sell index premium at 30-45 DTE and lean the richer wings in IWM; the whole book pivots on SPY holding 772.2672579983.
Cramer's Monday watchlist flags Microsoft and Wells Fargo upgrades plus M&A activity - mega-cap positive flow lines up with the GEX build in MSFT, reinforcing the positive-gamma SPY/QQQ regime.
Cramer's Sunday 'put cash to work' column is sentiment-timing commentary - the kind of retail call-to-action that often marks capitulation-into-support moments, worth watching for a short-term bid floor.
Alito retirement chatter plus Senate control narrative = low-probability but high-impact Supreme Court nomination tail risk - not a near-term driver but adds to Nov-Dec term vol premium.
Oil and bond markets flagged as critical drivers - rhymes with the MOVE pop today, confirming the next regime move likely originates in rates vol, not equity flow.
OpenAI safety departure and 'nuclear-level safeguards' call feeds AI governance tail risk - not an immediate catalyst but adds slow-burn pressure to AI mega-cap valuations.
Fire near Aramco facility in Riyadh is the classic energy-shock geopolitical headline - if confirmed as attack, oil vol spikes immediately and the whole MOVE/VIX relationship resets.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.51 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 772.27 against a spot of 773.61. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.77% with a volatility risk premium of -0.6%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.51. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime