Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 771.63 with Positive Gamma dealer positioning and net GEX of $7.07B - moves get damped, not amplified. Gamma flip at 769.31 is a razor's edge beneath spot; call wall 785.00 caps upside, put wall 745.00 is the demand shelf, with 0DTE gamma at 67.4%% of total doing most of the intraday work. Dealers run -$140.27B vanna and -$4.9M charm - vanna is hostile if vol spikes (dealers sell delta), charm is pulling toward the pin into expiry. Vol read: VIX 15.69 with VIX9D/VIX/VIX3M in Contango and VVIX 89.51 - carry regime, vol-sellers favored. QQQ at 752.12 aligned Positive Gamma above its flip 746.82; IWM at 282.39 is Unknown regime and below flip 293.88, with VRP 6.2% - the richest premium in the complex. Fear & Greed 29 (Fear) says sentiment is defensive even as structure is supportive - contrarian for continuation. Bottom line: iron condor 21-30 DTE in IWM wins the VRP, fade SPY call wall into 785.00, respect put wall; a close under 769.31 flips the whole posture - size down immediately.
SPY sits in supportive positive-gamma territory just above 769.31, with dealers damping intraday swings while QQQ mirrors the regime from above its own flip. IWM is the fracture point - below its flip with net negative GEX and the richest VRP in the complex - turning it into the premium-sale candidate while large caps grind. VIX contango, low VVIX, and dovish fear-sentiment keep carry trades favored, but a slip of SPY under 769.31 flips the entire dealer book from damper to accelerant.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
771.63
769.31
+0.30%
785
745
760
$7.07B
Long gamma
QQQ
752.12
746.82
+0.71%
760
740
725
$7.80B
Long gamma
IWM
282.39
293.88
-3.91%
285
280
285
-$2.93B
-
VIX
15.69
15.65
+0.26%
20
15
19
$6.87M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.20
10.67
+0.53
1.99
2.10
0.95
QQQ
16.58
15.11
+1.47
2.75
1.45
1.06
IWM
17.08
10.88
+6.20
1.94
2.36
2.52
VIX
81.97
97.46
-15.49
-142.12
0.32
0.01
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
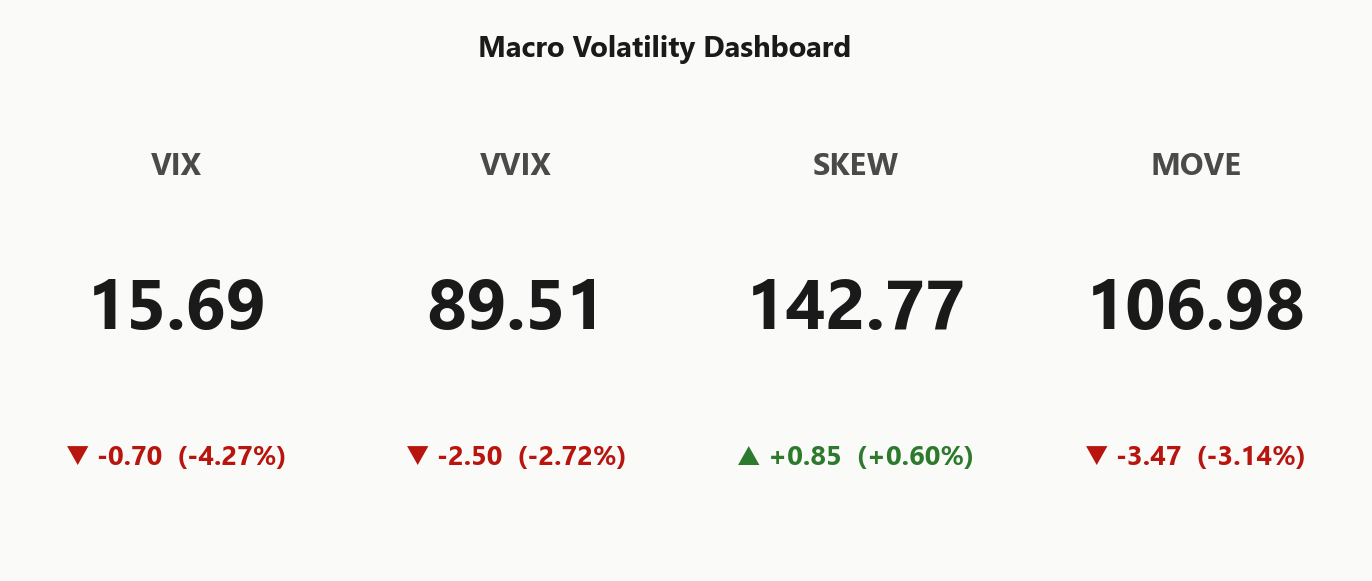
15.69
-4.27%
VVIX
89.51
-2.72%
SPX
7,745.45
+1.03%
SKEW index
142.77
+0.60%
MOVE (bond vol)
106.99
-3.14%
VIX term (9d/30d/3m/6m)
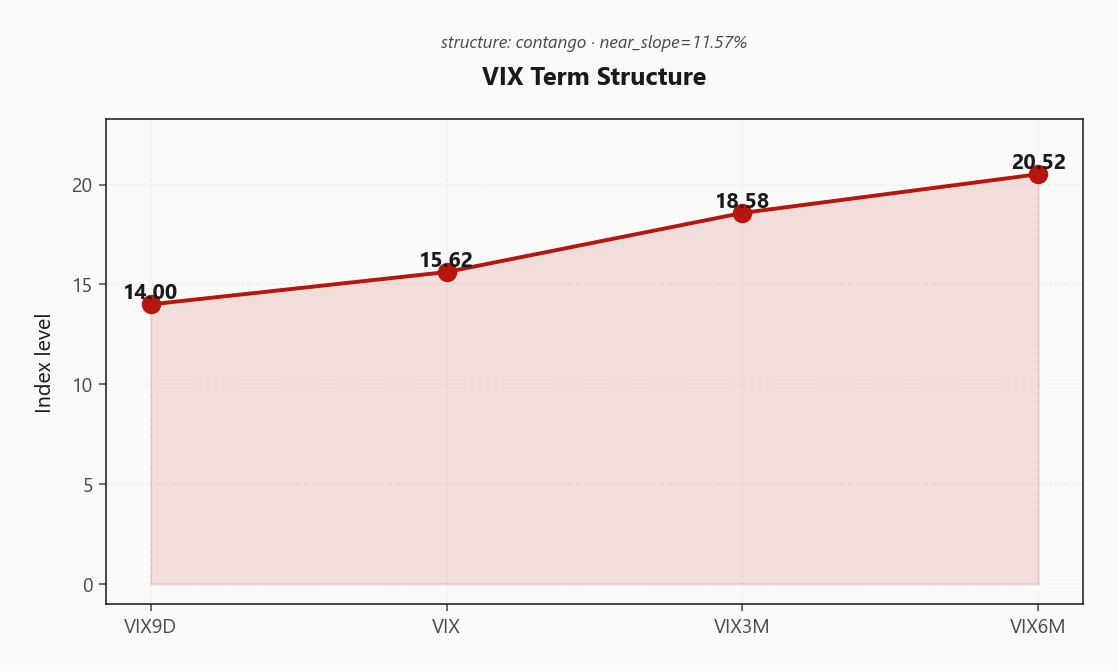
14.00 / 15.62 / 18.58 / 20.52
Steep contango
VVIX / VIX
5.70
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime reads Elevated - Elevated / Watchful - with VIX at 15.69. Not calm, not stressed. Vol sellers get paid, but with respect: this is the band where carry works right up until it doesn't, so size discipline earns its keep. The transition matrix tips the hand - probability of migrating to panic over the next five sessions is 0.05, versus a path to low-vol over ten sessions at 0.45. The higher-probability drift is toward calmer, not stormier.
Half-life of 15 sessions says this state is sticky. Regimes with this persistence profile reward holding carry structures through noise rather than flipping on every intraday wiggle. Tail hedges become optional, not required - the panic-transition probability is simply too low to tax every position with convexity premium. Reserve long-vol spend for asymmetric catalysts, not baseline insurance.
The invalidation is clean: a VIX break above twenty flips the posture immediately. Until then, the regime pays sellers who respect size and let the half-life work.
What it means for your trading
Elevated but anchored: 15-session half-life and a 0.05 panic-transition probability keep vol sellers favored, with the drift biased toward 0.45 odds of a low-vol migration over ten sessions. A VIX print above twenty is the single-line invalidation.
Trading readVIX, VVIX, MOVE all down together - vol complex is confirming lower stress across equities, options-on-options, and bonds. No divergence to trade, which itself is the signal: trend-following regime.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Contango across every tenor, with 9D at 14.00 sitting well under 30D 15.62, and the medium belly steady through 3M 18.58 into 6M 20.52. No event bump embedded, no front-end panic bid - just a textbook carry regime paying sellers across the curve.
Near-slope at 11.57%% confirms the steepness is real, not noise. Forward 30-to-60 clears at 19.895537188, pricing the sweet spot for calendar structures and anchoring the Steep Contango read. The 21-30 DTE window is where forward vol prices the richest decay against spot realized - that is the edge, and it is clean.
Breakdown risk is single-signal: a flattening or inversion of the 9D over 30D front. Until that front cracks, carry is the regime, decay is the paycheck, and long-vol positioning is the tax. Monitor the near-term differential like a trip-wire - everything else in the complex is downstream of it.
What it means for your trading
Steep Contango with 9D under 30D and forward 30-to-60 at 19.895537188 makes 21-30 DTE the premium-harvest window. Watch the 9D/30D front - a flattening there is the single signal that invalidates the carry regime.
Trading readContango across the entire curve with near slope 11.57%% = carry regime fully active; vol sellers get paid and futures-roll trades keep working until the front end inverts.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY HV20 10.67 against ATM IV 11.2% leaves a modest VRP 0.53% - short premium is paid, just not generously. The 60-day basis at 11.11 shows no realized acceleration bleeding into the front book; the implied-realized wedge is intact without being lucrative in the index itself.
IWM is where the harvest lives. Realized 10.88 against IV 17.08% drives VRP 6.2% - the richest premium in the complex and the clear routing for 21-30 DTE short-vol structures. QQQ at 1.47% sits between - tech premium is elevated but not extreme, meaning dispersion continues to pay index-over-single-name.
The tell is VIX VRP -15.49%: deep negative, confirming the complex is paying for near-term vol while realized stays tame. Vol-of-vol pricing may be too complacent, but with no RV acceleration visible on the 20-day basis, the carry trade continues until the front end flinches.
What it means for your trading
Modest SPY VRP 0.53% with IWM VRP 6.2% as the standout premium-harvest name; VIX negative VRP -15.49% flags the complex is overpaying for near-term vol against tame realized.
Skew Convexity
SPY quarter-delta skew prints at 1.99% with put IV 10.06% bid over call IV 8.07% and ATM anchoring at 9.39% - ordered downside demand, not tail panic. The smile ratio at 1.25% confirms a moderate hedging bid without the fat-tail convexity premium that would warn of a shock. The call wing sitting flat and cheap tells you the book is pricing zero upside conviction - nobody is paying up for melt-up optionality.
Cross-asset, the ordering is instructive. QQQ steepens to 2.75%, carrying the richest hedging bid in the complex as mega-cap concentration risk gets paid for. IWM is the curious one: skew runs 1.94%, shallower than SPY despite the negative gamma regime below its flip - the downside is already happening in spot, so the convexity bid has already been monetized.
Trade implication: with skew ordered rather than panicked, put spreads outperform naked long puts for hedging the index - you finance the expensive put wing by selling the cheap one. Reserve naked convexity for QQQ where the steeper curve pays harder on a shock.
What it means for your trading
Skew is bid but orderly across the complex - QQQ steepest, IWM flattest despite its weakness, SPY in the middle. Hedge with put spreads over naked puts; the cheap call wing finances the structure and leaves room to add convexity only if VVIX breaks.
Vol-of-Vol Structure
VVIX prints 89.51 against VIX 15.69, a ratio of 5.70 that scores Low on jump-risk pricing. With VVIX sitting under the triple-digit threshold, the bimodal regime tax is absent - the market is not paying up for the possibility that vol itself gets violent. Vol sellers can run Standard Size, no haircut required.
The read-through: short-premium structures across the complex are not fighting a hidden convexity bid, which keeps the carry trade clean and the hedging budget for naked gamma lean. The absence of a vol-of-vol premium also means calendars and iron condors do not need to overpay for wing protection - the tails are priced where they belong.
Trip-wire is simple and binary: VVIX pushing above 89.51 while VIX holds 15.69 is the first tell that convexity is being bid before spot vol moves. That divergence historically precedes regime shifts by sessions, not minutes - watch the ratio, not the level.
What it means for your trading
Vol-of-vol at Low with ratio 5.70 clears the way for Standard Size premium selling; the single early-warning indicator is VVIX breaking higher while VIX stays pinned.
Dispersion Spread
SPY index IV at 11.2% sits meaningfully below QQQ at 16.58% and IWM at 17.08% - basket diversification is doing exactly what it is paid to do. The index wrapper nets out single-name correlation risk that the sector and small-cap baskets cannot shed, and the spread is wide enough to trade directly.
IWM's premium is idiosyncratic small-cap stress - balance-sheet fragility and rate-sensitivity that an SPY hedge will never capture. QQQ's premium is concentration-driven, where mega-cap positioning dominates the basket and single-name vol bleeds straight into the index print. Neither spread is noise.
Trade structure: short single-name vol in the fragmented baskets, long index vol as the hedge. Prefer SPY/SPX for the vol-selling leg over single-name during this regime - dispersion is Aligned and working as designed. Fade the fragmented, hold the diversified.
What it means for your trading
The IV gap between SPY at 11.2% and the IWM/QQQ pair confirms dispersion is live and tradable - sell single-name premium, hedge with index.
Liquidity & Microstructure
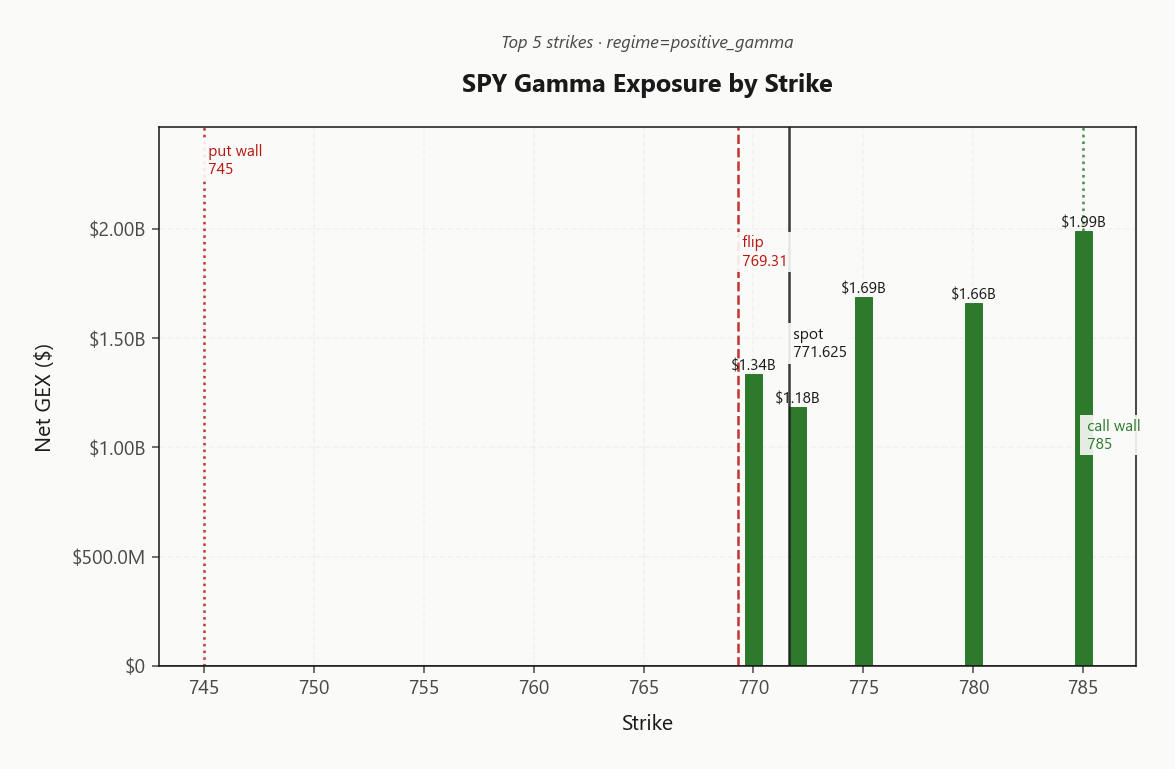
SPY's book is anchored by the 785.00 magnet carrying $1.99B of net gamma, with the deep-OTM OI cluster at 700 defining the structural anchor. Spot sits above the gamma flip at 769.31, placing dealers in the buy-weakness, sell-strength posture - the textbook mean-reversion zone that holds until the flip breaks.
The call wall at 785.00 is the clean fade: dealer suppression intensifies into it, and rallies into that print have the lowest expected follow-through of any level on the board. The put wall at 745.00 is the demand shelf dealers actively defend. Between those two prints is the damped zone; outside them, flow inverts quickly. 0DTE gamma at 67.4%% of total means intraday action is dominated by same-day chop that burns off into the close.
Cross-asset tripwires are drawn: QQQ flip at 746.82 and IWM flip at 293.88 set the lines that would flip each book from damper to accelerant. IWM already sits below its flip - the lone fracture in an otherwise supportive microstructure.
What it means for your trading
Microstructure is deep and supportive while SPY holds above 769.31: fade attempts into 785.00, respect 745.00, and treat a close under the flip as the single risk-management trigger that inverts the entire dealer posture.
Trading readThe massive positive gamma clusters above spot show where dealers damp strength - fade attempts into 785.00; the thin negative zone below the flip is where selling would get amplified fast.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer second-order Greeks tell a split story. Net VEX at -$140.27B is firmly negative - any vol spike forces dealers to sell delta into weakness, so vanna is hostile on a shock even while first-order gamma stays supportive. Net CHEX at -$4.9M is pulling flow toward the pin into the close, with charm bias registering Supportive.
The Gamma Flip at 769.3101898084 sits only -0.2999916011% beneath spot - a razor's edge. Above it, dealers damp; a close below inverts the entire book from damper to amplifier, and the negative vanna compounds any downside the moment vol kicks. Size hedges against the vol-of-vol tail, not just the delta drift.
Cross-asset vanna confirms the posture is uniform, not idiosyncratic: QQQ net VEX -$141.95B and IWM net VEX -$47.81B both sit negative alongside SPY. A coordinated vol-up shock sells deltas across the complex - hedge accordingly, don't scatter.
What it means for your trading
Charm is dovish into the pin and gamma is supportive above 769.3101898084, but negative vanna across SPY/QQQ/IWM means any vol spike compounds downside - a close through the pivot flips dealer flow from damper to amplifier and makes vol-of-vol the dominant risk.
Cross-Asset Confirmation
MOVE at 106.99 down -3.14% strips credit-shock risk off the table - bond vol is actively compressing while equity dealers run long gamma. SPX printing 7745.45 firm alongside QQQ at 752.12 keeps the mega-cap complex coherent; this is not a cross-asset dislocation, it is an isolated equity-microstructure story.
Fear & Greed reads 29 (Fear) while dealer positioning stays supportive and VIX sits in Contango - the textbook contrarian setup where sentiment lags structure. Cross-asset tone is Unknown, meaning there is no divergence to fade across bonds, vol, and equity.
IWM at 282.39 is the lone fracture - small-cap-specific, not macro. Trade it as a single-asset VRP harvest, not a systemic hedge; the rest of the complex confirms carry.
What it means for your trading
MOVE down, VIX in Contango, and SPX firm converge on an all-clear across asset classes - IWM breakdown is isolated microstructure, not a macro signal to position against.
Scenario EV
The structure of choice is Unknown across the 21-30 DTE window - the forward curve sits in Steep Contango, VVIX at 89.51 prints Low jump-risk, and the carry trade is paying across the complex. IWM carries the richest premium with VRP at 6.2%, a cleaner iron-condor candidate than SPY's modest 0.53% or QQQ's 1.47%.
Sizing follows Standard Size - no vol-of-vol surcharge to pay, and the 15-session half-life on the current regime says the carry window stays open. Calendars outperform strangles in SPY and QQQ given the Steep Contango geometry; forward 30-to-60 at 19.895537188 is where the richest decay lives.
Naked long vol is penalised in this regime - term-structure roll bleeds the position before realized ever catches implied. The invalidator is a close under 769.3101898084: that flips dealer flow from damper to amplifier and inverts the entire book.
What it means for your trading
Sell IWM iron condors 21-30 DTE for the richest VRP in the complex, run SPY/QQQ as calendars rather than strangles, and size Standard Size. A close under 769.3101898084 invalidates the carry trade immediately.
Actionable Summary
Trade the regime, not the headline. SPY holds Positive Gamma above the 769.31 flip and QQQ mirrors from above its own, while IWM breaks beneath flip with the complex's richest VRP at 6.2% - the clearest premium-sale name on the board. SELL IWM iron condors in the 21-30 DTE window where forward vol prices richest and Standard Size sizing is sanctioned by sub-ratio VVIX.
In SPY, FADE rallies into the 785.00 call wall and RESPECT the 745.00 put wall as the dealer-defended demand shelf. Contango across the VIX curve and Unknown cross-asset tone keep carry trades paid; negative net vanna at -$140.27B is the asterisk - AVOID naked long vol and oversized short gamma.
The single line that matters: 769.3101898084. Above it, dealers damp and the Elevated / Watchful regime extends on its 15-session half-life. Close below and the book inverts from damper to accelerant - size down immediately.
What it means for your trading
Carry regime with disciplined edges: harvest IWM VRP at 6.2%, fade SPY into 785.00, respect 745.00, and treat 769.3101898084 as the hard line that flips the entire dealer posture.
Jobs report framing matters because it was the first green-light macro print of the week - reinforces the supportive regime read if confirmed by follow-through buying.
Signs of a bond sell-off ending matter structurally - if yields have peaked, duration gets bid and equity multiples get a tailwind just as dealer gamma stays long.
Treasury yields firming into the jobs report sets the macro backdrop - the index response is more meaningful because it was priced through fixed-income first.
Boeing avoiding a strike is a low-key industrial-complex positive - removes a specific operational drag that could have fed into broader cyclical weakness.
Mega-cap buyback intensity (Nvidia at $235B, Micron hinted large) is a structural bid for the complex that keeps dealer-flow story coherent with corporate action.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.69 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 769.31 against a spot of 771.63. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.2% with a volatility risk premium of 0.53%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.69. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime