Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 768.97 with net GEX $3.73B - gamma regime undetermined but call wall 770.00 is live and dealers lean long gamma into the top strikes. Key levels: call wall 770.00, put wall 745.00, max pain 760.00, with spot sitting 0.1339454075% from the Call Wall - pinned regime, not trending. Dealer vanna -$120B and charm -$2.2M both negative - vol-up accelerates downside, time decay pressures tape into close. Vol read: VIX 15.70 with term structure Contango (22.92%% slope), VVIX 88.67 low = full-size positioning permitted, VRP 1.01% active. Bottom line: sell premium into 770.00, fade rips, respect 745.00 as hedge trigger - IWM's negative gamma (-$3.55B) is the fragility to watch.
SPY pinned at call wall 770.00 with VIX 15.70 contango - fade strength, sell premium 21-30 DTE
SPY grinds into the 770.00 call wall with gamma cushion $3.73B absorbing dips while VIX 15.70 holds steep contango and VVIX 88.67 prints low. The regime says premium sellers get paid - but IWM's negative-gamma backdrop (-$3.55B) is the fragility hiding under the index tape. Trade the carry; respect the IWM divergence.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
768.97
-
-
770
745
760
$3.73B
-
QQQ
749.54
744.85
+0.63%
750
725
725
$7.79B
Long gamma
IWM
281.20
293.06
-4.05%
285
280
285
-$3.55B
-
VIX
15.70
15.66
+0.24%
20
15
19
$6.57M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.26
10.25
+1.01
1.76
2.10
1.10
QQQ
16.38
15.03
+1.35
1.95
1.45
1.08
IWM
16.02
11.66
+4.36
2.01
2.36
1.92
VIX
82.83
97.90
-15.07
-137.58
0.32
0.07
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.68
-4.33%
VVIX
88.67
-3.63%
SPX
7,718.78
+0.68%
SKEW index
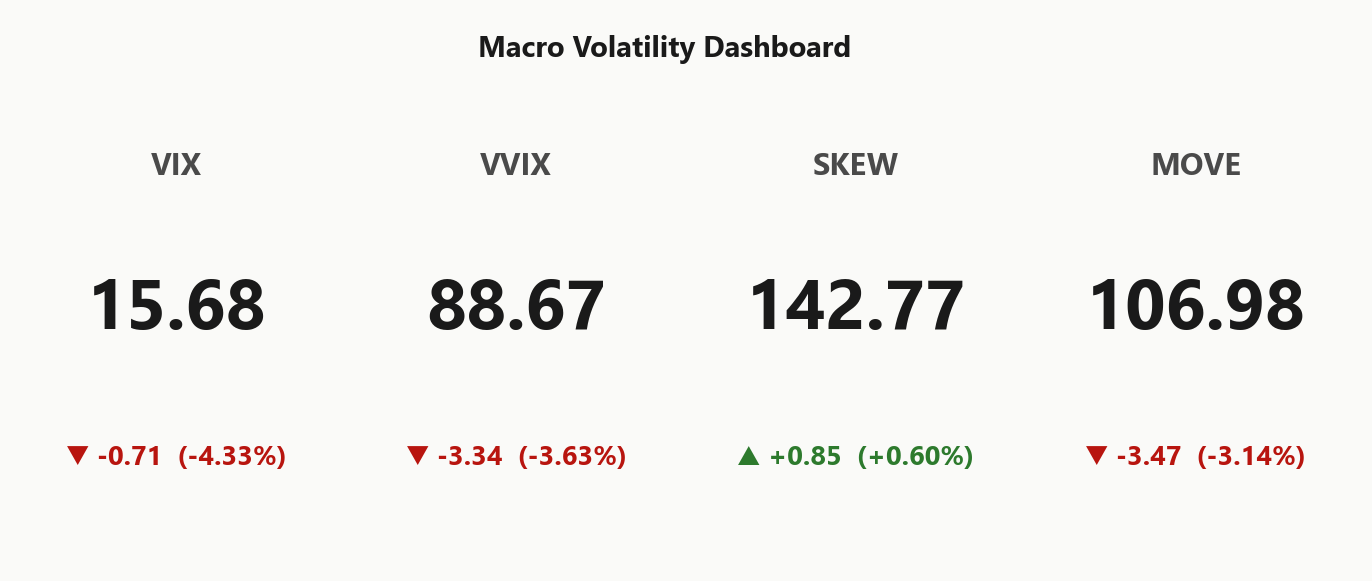
142.77
+0.60%
MOVE (bond vol)
106.99
-3.14%
VIX term (9d/30d/3m/6m)
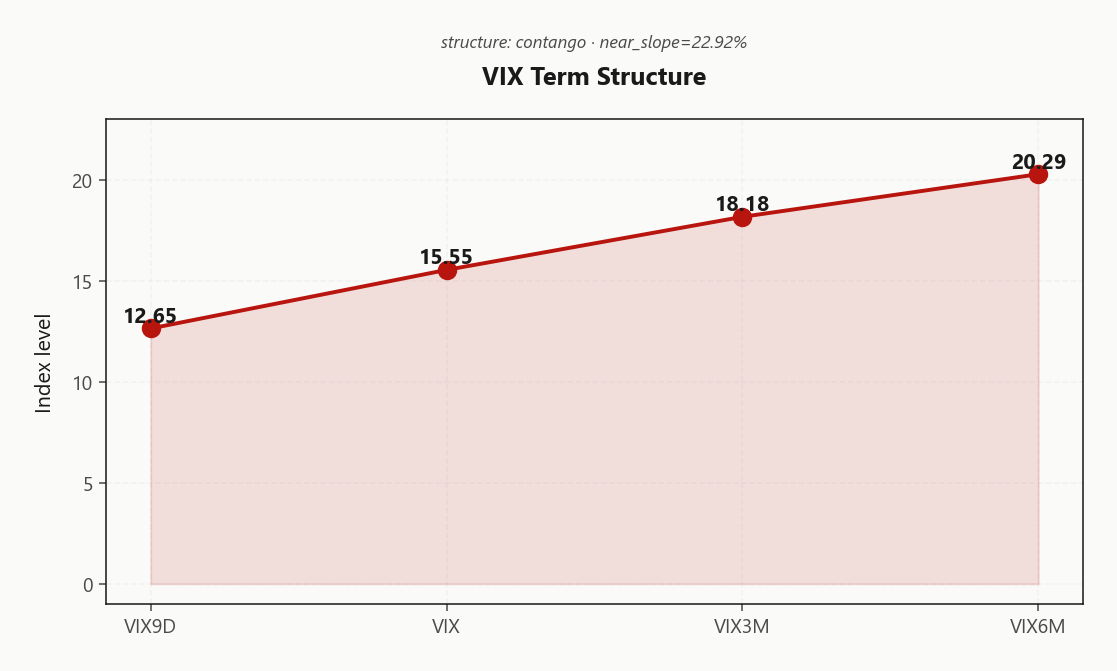
12.65 / 15.55 / 18.18 / 20.29
Steep contango
VVIX / VIX
5.65
Low
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX at 15.68 - the Elevated bucket, not stressed, not asleep. Half-life of 15 sessions says this state is sticky but not entrenched; the regime persists on the order of three trading weeks before the Markov chain resets, which is long enough to anchor carry trades and short enough that complacency is unwarranted.
The transition math favors sellers. Five-session panic probability prints at 0.05 - a thin left tail that doesn't demand a vol hedge at any price. Ten-session drift-to-low odds sit at 0.45, materially higher - room to compress from here, not expand. Signal color yellow: run premium-short structures at standard size, but keep the pivot at 770 and the put wall at 745.00 as the lines that force a size cut.
What it means for your trading
Regime Elevated / Watchful at VIX 15.68 - sticky for ~15 sessions, panic tail at 0.05, drift-lower odds at 0.45. Sell premium at standard size; respect the pivot.
Trading readVIX, VVIX, MOVE all cooling in sync - confirmatory, not divergent. SKEW stuck high is the one holdout - tail bid persists even as realized vol releases.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Contango top to bottom - 12.65 on VIX9D rolls into 15.55 spot VIX, then 18.18 at the three-month and continues up the back end. Monotonic ascent, textbook. Near-slope at 22.92%% is steep enough to pay carry but nowhere near the pancake-flat prints that mark event stress - this is structural contango, not a market holding its breath.
Forward 30-to-60 vol clears at 19.3614914198, well under where realized three-month has been grinding. Term premium is sitting on the seller's side of the ledger. Roll-down compounds inside the 21-30 DTE window where gamma exposure stays manageable and the curve pays you daily to hold the position.
Signal reads Steep contango - vol sellers favored. Calendars on SPY harvest the steepest slope; short-dated premium gets rolled, not held through expiry. The regime permits size - just not stupidity.
What it means for your trading
Curve is Steep Contango with forward vol 19.3614914198 underneath realized - sell the belly, roll the front, let carry do the work.
Trading readContango with 22.92%% near-slope - vol sellers' carry is live and generous. Market expects no stress; roll-down pays.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.26% prints over HV20 10.25 and HV60 11.06, leaving VRP at 1.01% - live, but modest. The IV/RV spread is tight; sellers get paid, but not generously. The real signal is in the complex: IWM VRP 4.36% is the richest print, well clear of SPY and QQQ.
QQQ VRP 1.35% runs elevated vs SPY - confirms the tech-vol premium is still bid, consistent with mega-cap gamma accumulation. But IWM is where the per-unit-risk payout sits: small-cap IV carries idiosyncratic tail premium that index vol can't match.
Options are rich to realized across the complex, with IWM the dispersion winner. Short-premium structures route to IWM first - iron condors capture the richest carry - while SPY gets the term-structure play rather than the VRP harvest. Trade the vehicle, not the index.
What it means for your trading
VRP active across the complex but modest in SPY at 1.01%; IWM VRP 4.36% is the best per-unit short-vol venue, with QQQ 1.35% confirming tech-vol premium bid.
Skew Convexity
Quarter-delta skew prints 1.76% with a smile ratio of 1.22% - an ordered left-tail bid, not a panic steepening. Put wing at 9.82% sits above ATM 8.49%, while the call wing at 8.06% prints flat to inverted. Translation: hedgers are paying for downside convexity in a measured, structural way, while the market refuses to pay a dime for upside tails.
SKEW index at 142.77 corroborates - tail-hedging demand is steady, not spiking. The convexity bid is doing its job as portfolio insurance without tipping into the kind of reflexive steepening that precedes a vol event. Call-side flatness is the tell: zero upside conviction priced, no one chasing melt-up optionality despite SPY grinding into 770.00.
Structural implication: prefer put spreads over naked puts. The put wing is rich enough that selling the lower leg finances the convexity you actually want, and the flat call wing makes call overwrites cheap funding for downside hedges. Naked long puts overpay for carry you can harvest via spread structures.
What it means for your trading
Skew is bid but ordered - 1.76% with SKEW at 142.77 signals steady hedging, not panic. Trade put spreads to capture carry; the flat call wing says upside premium is a gift, not a trade.
Vol-of-Vol Structure
VVIX at 88.67 against VIX 15.68 prints a Low vol-of-vol regime - ratio 5.65 sits inside the band where jump risk is dormant and bimodal event premium has drained out of the surface. VVIX cooled -3.63% intraday, confirming the binary-regime fear bid is unwinding rather than coiling.
Below the hundred-handle line, the sizing book flips green: Standard Size - no half-size haircut on short-vol structures, no mandatory tail overlay to clear risk. The one asymmetry worth naming is on the long side: vol-of-vol discount makes convexity cheap, so if you must own gamma, the far wing is where it looks mispriced against a Elevated / Watchful regime.
Trade: full-size the IWM iron condor, let the SPY calendar run - but keep a small long-vol tail on because this is the one place options are not rich.
What it means for your trading
VVIX 88.67 and ratio 5.65 greenlight full-size short-vol - jump premium is cheap, so pair the carry with a small long-wing hedge rather than skipping it.
Dispersion Spread
Single-name vol sits well over index vol: QQQ ATM at 16.38% and IWM at 16.02% dwarf SPY's 11.26%, with cross-strike dispersion at 71.21 confirming the premium stacks in the wings and in the smaller baskets, not the mega-cap tape. SPY ATM is compressed relative to its single-stock composition - correlation is elevated enough that index hedges still function, but the premium per unit risk lives downstream.
IWM ATM at 16.02% prints the idiosyncratic small-cap tail outright. That's the dispersion fade of choice: short IWM/QQQ premium funded against long SPY vol as the hedge leg. Cross-expiry dispersion at 3.35 keeps the trade clean - this isn't a correlation-crush setup where everything realizes together, it's a dispersion-earner where the index damps while the components churn.
What it means for your trading
IWM and QQQ ATM vol trade rich to SPY's 11.26% - short the single-name premium, hedge with index vol, and let the Unknown dispersion do the work.
Liquidity & Microstructure
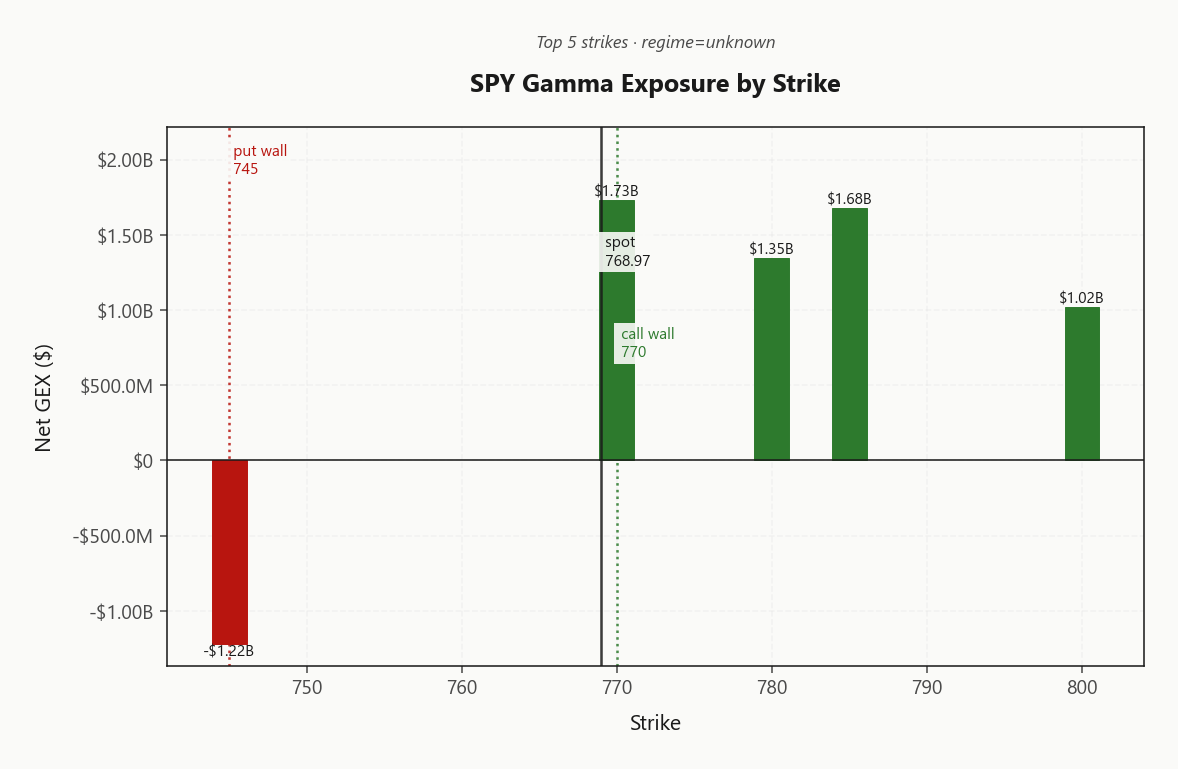
The book is concentrated, not diffuse. Top-strike net GEX sits at 770.00 carrying $1.73B against 239095 open interest - a stack this tight produces sharp pin behavior, not drift. The call wall at 770.00 is the ceiling; the put wall at 745.00 is the floor; max pain 760.00 sits cleanly inside the band, loading the tape with pin pressure into Friday.
Below spot, the highest-OI strike at 700 acts as a magnetic floor - dealers lean long gamma above and dampen rallies into 770.00, but the amplifier flips the other way the moment 745.00 breaks. The regime is deep and supportive; it is not symmetric.
0DTE represents 107.2% of total gamma - intraday is dealer-dominated tape, scalpers' terrain, mean-reversion inside the walls. Trade the band, respect the break.
What it means for your trading
Concentrated OI at 770.00 and a floor at 700 frame a sharp pin regime between 745.00 and 770.00 - fade rips into the ceiling, hedge the moment the floor breaks.
Trading readDealer gamma stacks above spot into 770.00 - rallies get sold, pullbacks get bought. The one-way amplifier only engages if 745.00 breaks.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna -$120B and charm -$2.2M both print negative - the greek bundle is primed to accelerate downside and drag the tape into the close. Vol-up means dealer delta down: a VIX pop from 15.68 gets amplified through hedging flows, not absorbed. Charm layers on top - dated puts gain delta as expiry approaches, forcing dealers to trim longs mechanically.
Charm pivot sits at 770, with spot 0.1339454075% away in Neutral bias - the line between supportive and hostile dealer flow. Cross spot through that pivot and the flow sign flips; stay below and the drag compounds into the bell. QQQ net vex -$129.36B tells the same story in tech - mega-cap gamma is long, but the vanna/charm layer underneath is short-biased.
Net read: the gamma cushion holds the range, but the second-order greeks are quietly selling. Respect the pivot; a VVIX bounce back above the 88.67 print is the trigger to cut vol-short size.
What it means for your trading
Negative vanna plus negative charm means any vol expansion gets amplified and time decay pressures the tape - spot sitting 0.1339454075% from the 770 pivot in Neutral bias keeps the regime pinned, not trending.
Cross-Asset Confirmation
MOVE at 106.99 cooled -3.14% intraday - rates vol is releasing, no credit event bleeding into equity premium. VVIX at 88.67 and VIX at 15.70 both lower in sync; the macro backdrop is confirmatory, not divergent. Fear & Greed prints Fear at 32 while SPX makes highs - sentiment lagging price, positioning hasn't caught up. The pain trade stays higher.
Under the hood, QQQ at 749.54 and IWM at 281.20 move aligned on the tape, but the dealer regime splits them: QQQ sits in Positive Gamma with spot above flip, while IWM carries net GEX -$3.55B - the small-cap fragility is the hidden story under a quiet surface. Classic late-cycle positioning: mega-cap stable, small-cap unstable.
No single cross-asset divergence is large enough to lead the day. Trade the carry, keep the IWM hedge in the drawer - that's where any break starts.
What it means for your trading
Macro complex calm and confirmatory - MOVE releasing, VVIX cool, F&G lagging price - but QQQ positive-gamma versus IWM -$3.55B negative-gamma is the fragility signature to respect.
Scenario EV
The carry stack lines up: VIX term structure prints Contango at 22.92%% near-slope, VVIX 88.67 keeps vol-of-vol Low, and skew sits bid without steepening. Sizing guidance reads Standard Size - no half-size haircut required. The 21-30 DTE pocket is where the curve pays most per unit gamma risk, capturing roll-down without eating a convex front-month tail.
Vehicle selection matters more than direction. IWM VRP at 4.36% is the richest in the complex - iron condor there earns the highest premium per unit risk, with the negative-gamma regime (-$3.55B) baked into the width. SPY carries the steepest term curve, so the trade shape is a calendar harvesting time decay against 1.01% VRP, anchored by the 770.00 ceiling and 745.00 floor.
Avoid: naked long vol into cheap VVIX, 0DTE lottery tickets, and upside call buying - the 8.06% call wing says no one is paying for right-tail convexity, so neither should you.
What it means for your trading
Sell premium at 21-30 DTE - IWM iron condor for richest VRP, SPY calendar for steepest term carry. Full-size permitted while VVIX sits Low; cut in half if it bounces.
Actionable Summary
Structure the book around carry, not direction. Recommended vehicle is Unknown at 21-30 DTE - the sweet spot where contango roll-down pays and gamma risk stays contained. IWM iron condor is the preferred venue; VRP 4.36% is richest in the complex, and the small-cap negative-gamma backdrop -$3.55B makes the premium generous for the risk taken.
Respect the walls.770.00 is the fade zone - dealers lean long gamma into the top strike and sell rips in size. 745.00 is the hedge trigger; a break there flips the regime from mean-reverting to accelerant via negative vanna -$120B. Charm pivot sits at 770 with spot 0.1339454075 away in Neutral bias - this is the line where dealer flow flips from supportive to hostile.
Avoid naked long vol, 0DTE lottery tickets, and chasing upside. Regime reads Elevated / Watchful - supports carry, punishes directional bets. Watch VVIX 88.67: a bounce back above triple-digits cuts size in half immediately.
Oil down 2% on diesel release talks - removes a key stagflation tail that was keeping SKEW bid last week.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.70 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $3.73B. The gamma flip sits at N/A, with the call wall at 770.00 and the put wall at 745.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 768.97. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.26% with a volatility risk premium of 1.01%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.68. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime