Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY settled at 770.15 into the close with net GEX $943.2M and gamma-flip status Stored Sign Mismatch - regime unresolved despite call wall 785.00 and put wall 745.00 bracketing. Max pain 760.00 sits -1.3179250795% below spot, framing a neutral charm pivot into Monday. QQQ confirms Positive Gamma above its flip 744.06, cushioned to call wall 760.00, while IWM carries net GEX -$3.26B and remains the amplification wing. VIX printed 15.31 with VVIX 87.77 - VVIX/VIX ratio at 5.68 says jump risk is cheap, standard sizing on. Term structure Steep Contango (VIX9D 12.16, VIX 15.42, VIX3M 18.08) favors the vol seller's carry. VRP split is the lead angle: SPY -0.04% (negative - options cheap to realized) vs IWM 4.02% (fat premium). Fear & Greed 32 (Fear) contrasts a VIX cooling into contango - sentiment and vol disagree. Bottom line: sell IWM 21-30 premium structures above the walls, respect SPY's unresolved flip until status clears, avoid chasing SPY vol short given the negative VRP.
SPY closed at 770.15 with net GEX $943.2M but gamma-flip unresolved while QQQ holds Positive Gamma above its flip at 744.06; IWM remains the fragile wing with net GEX -$3.26B. VIX fell to 15.31 and VVIX to 87.77, locking a Steep Contango term structure that pays carry sellers. VRP divergence (SPY -0.04% vs IWM 4.02%) and SPY/QQQ regime divergence frame the next-session trade.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
770.15
-
-
785
745
760
$943.20M
-
QQQ
750.08
744.06
+0.81%
760
700
725
$4.38B
Long gamma
IWM
281.68
293.57
-4.05%
285
280
285
-$3.26B
-
VIX
15.31
15.25
+0.39%
20
15
19
$26.92M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.32
10.36
-0.04
1.61
2.10
1.22
QQQ
15.52
15.01
+0.51
3.14
1.45
1.06
IWM
15.52
11.50
+4.02
1.77
2.36
1.77
VIX
89.26
98.82
-9.56
-138.31
0.32
0.06
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
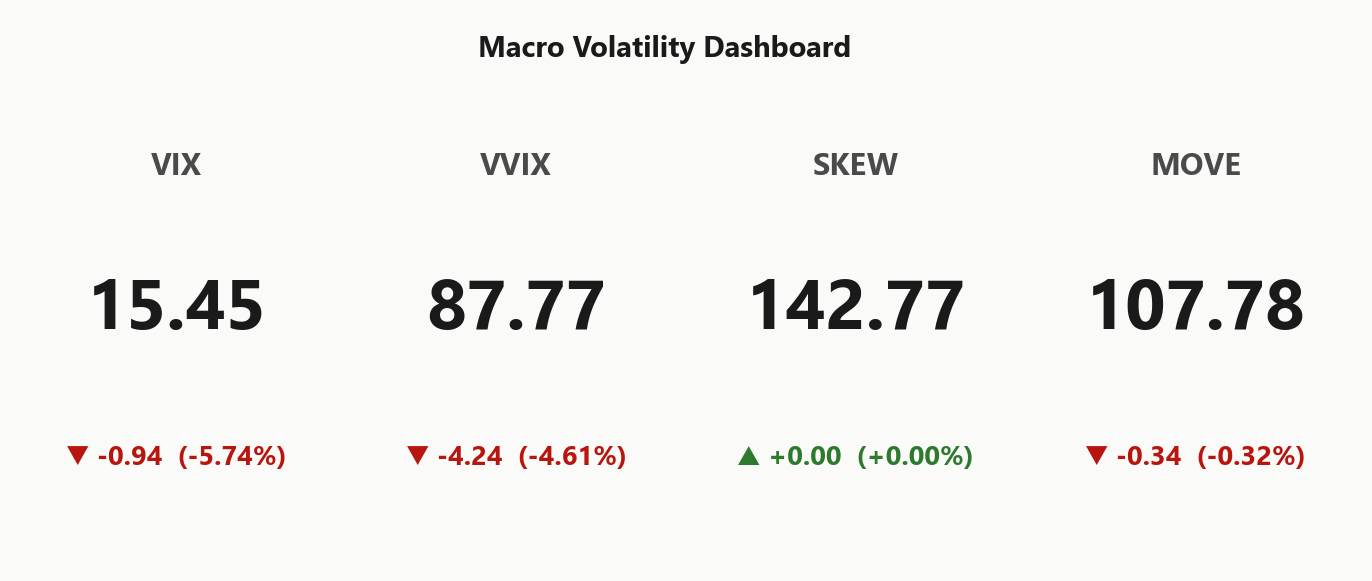
15.45
-5.74%
VVIX
87.77
-4.61%
SPX
7,722.72
+0.73%
SKEW index
142.77
0.00%
MOVE (bond vol)
107.78
-0.32%
VIX term (9d/30d/3m/6m)
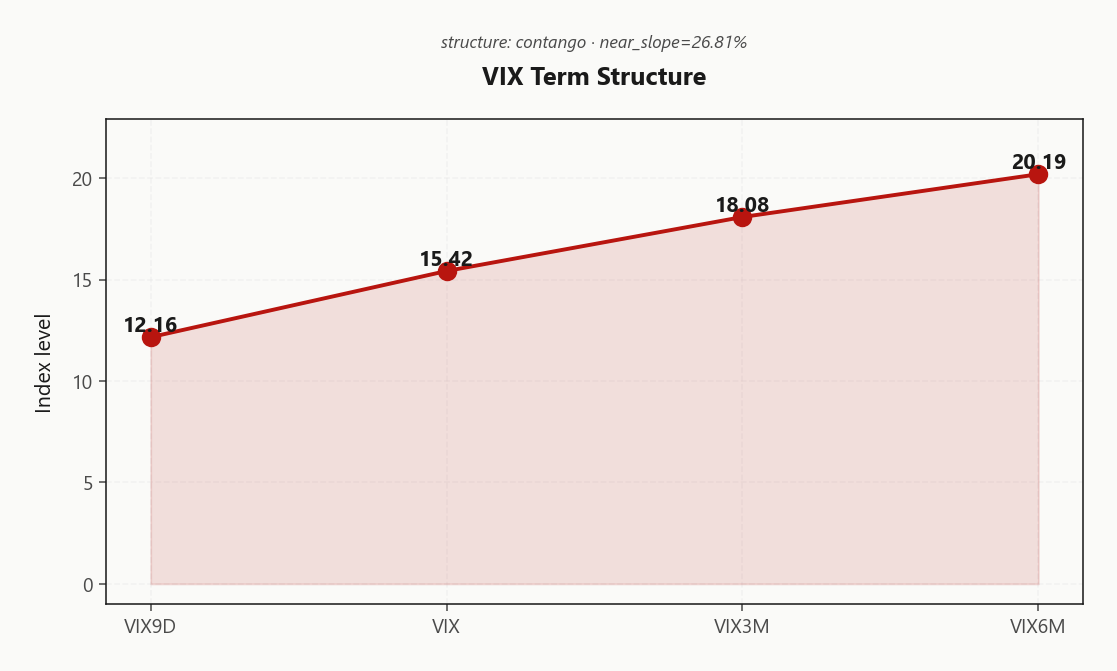
12.16 / 15.42 / 18.08 / 20.19
Steep contango
VVIX / VIX
5.68
Low
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX anchored at 15.45 - a sticky mid-band, not a transition setup. Transition probability to panic over the next five sessions prints 0.05, while the probability of drifting into a low-vol regime over ten sessions sits at 0.45. Half-life of 15 sessions says this state persists - size for duration, not for a break.
Operationally, that means the carry structure stays live: Steep Contango term curve, VVIX/VIX ratio 5.68 flagging Low jump risk, and VRP routing that favors IWM at 4.02% over SPY's negative -0.04%. SPY/QQQ regime divergence persists - QQQ holds Positive Gamma above its flip, SPY unresolved - so the fragility pocket is IWM, not the index.
Playbook: trade persistence. Premium sales out 21-30 DTE, respect SPY's charm pivot at 760, and watch VVIX plus MOVE for the first crack. Low panic odds, modest decay odds - no reason to pre-position for a regime shift that the transition matrix is not pricing.
What it means for your trading
Regime is Elevated / Watchful with VIX at 15.45 and a 15-session half-life - size for persistence, not transition, and route premium into IWM where VRP pays.
Trading readVIX cooling, VVIX cooling, MOVE flat, SKEW elevated - three of four confirm calm, SKEW alone keeps tail hedges paid. No divergence large enough to flag regime-break, but SKEW is the one to watch.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve closed in Steep Contango with VIX9D 12.16 stacked under VIX 15.42 and VIX3M 18.08 - a textbook carry curve pricing zero near-term event stress. Signal reads Green, carry trade green-lit for short-vol inventory in the belly of the curve.
Forward slope confirms the pay: 30→60 19.2728150513 rolls into 60→90 22.0994524819, handing calendar sellers clean roll-down without having to chase. The Contango structure is steep enough that 21 - 45 DTE is where the geometry pays - short the belly, let the front decay carry you.
Avoid the 0-7 DTE pocket where VIX9D 12.16 sits depressed and realized can gap-trade the implied; sweet spot is 21 - 45 DTE where slope and theta compound. Treat any flattening of the VIX9D-to-VIX leg as the first crack in the carry regime.
What it means for your trading
Term structure prints Steep Contango with the VIX9D 12.16 / VIX 15.42 / VIX3M 18.08 stack green-lighting 21-45 DTE short-vol carry while flagging 0-7 DTE as the trap window.
Trading readFront-to-3M slope 26.81%% is deep contango - vol sellers' carry is textbook, and the market is explicitly not pricing a near-term event spike.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 10.32% prints below HV20 10.36 and HV60 11.09, dragging VRP to -0.04% - options are cheap to realized, the rare inhibitor that disqualifies naked short-vol on the index. Shorting SPY premium here is selling at a discount to the tape; the carry trade requires a different venue.
IWM is that venue. ATM IV 15.52% against HV20 11.5 leaves VRP at 4.02% - the fattest premium in the index complex and the clean route for iron condors. QQQ sits in the middle with VRP 0.51%, a moderate seller's lane but secondary to IWM's richness.
Signal is Green on realized-vs-implied. Route sales into IWM at 21-30 DTE, treat QQQ as the complement, and buy SPY protection on any dislocation rather than fading the negative VRP.
What it means for your trading
SPY options are cheap to realized at VRP -0.04% - do not short SPY vol naked; route premium sales into IWM where VRP 4.02% is the richest pocket, with QQQ 0.51% as the moderate complement.
Skew Convexity
The 25-delta skew prints asymmetric but orderly: SPY skew_25d at 1.61% with smile ratio 1.26% - put IV 7.86% bid against call IV 6.25% around ATM 7.49%. The left wing is paying up, but there's no panic steepening - this is structural hedge demand, not a scramble.
QQQ carries the steeper tilt: skew 3.14% with put IV 12.06% vs call 8.92% - tech downside bid more aggressively on the back of concentrated mega-cap gamma. SKEW index at 142.77 stays elevated, confirming tail hedges remain paid across the board even as VVIX cools to 87.77.
Signal Yellow. Trade routing: put spreads over naked long puts - the put wing is rich, so finance it. Call wing is the cheap pocket for upside convexity lottos given Steep Contango term structure and QQQ holding Positive Gamma above its flip.
What it means for your trading
Skew is steep but ordered - tail bid without panic, with QQQ carrying the sharpest tilt. Finance put protection via spreads; harvest the cheap call wing for asymmetric upside convexity.
Vol-of-Vol Structure
VVIX printed 87.77 (-4.61%% session) against VIX 15.45, placing the VVIX/VIX ratio at 5.68 - Low. The panic zone sits well above where VVIX trades tonight, and the dislocation between realized vol-of-vol and spot vol says jump risk is being actively discounted by the market.
Signal reads Green with sizing guidance Standard Size - no haircut on short-vol inventory, carry trades run at full book. The flip side: with vol-of-vol crushed, convexity on the wings is being given away. Short-gamma carry is paid, but the hedge cost is trivial - a rare window where the carry seller can own the tail cheap.
Playbook: run Standard Size on premium sales anchored to the Steep Contango term structure, and opportunistically layer lotto wings - the asymmetry favors buying convexity while VVIX is this suppressed. First crack shows here before it shows in VIX.
What it means for your trading
VVIX at 87.77 and a VVIX/VIX ratio of 5.68 (Low) green-light Standard Size on short-vol carry; the suppressed vol-of-vol also makes tail wings an opportunistic buy, not a cost.
Dispersion Spread
Index vol understates the component tape. SPY ATM IV prints 10.32% while QQQ runs 15.52% and IWM matches at 15.52% - a Moderate correlation signature where single-name vol is paying up but the index wrap stays suppressed. That gap is the dispersion engine: realized correlation sits below implied, so index puts are cheap relative to the basket they insure.
Operationally, this breaks the standard playbook. Index hedges lose efficiency during idiosyncratic regimes - SPY protection won't catch a single-name blow-up in NVDA, MSFT, or the IWM tail, and QQQ regime Positive Gamma above its flip while SPY and IWM sit unresolved confirms the two-speed tape. Signal reads Yellow, flagging the dislocation but not panic.
Route accordingly: favor dispersion long - sell SPY vol against single-name vol purchases in the Mag7 complex - over naked directional index shorts. The structural edge is paid by the component premium, not the index direction.
What it means for your trading
Component IV at 15.52%/15.52% running well above SPY 10.32% flags a Moderate-correlation regime where dispersion long (short index vol, long single-name vol) dominates naked index shorts.
Liquidity & Microstructure
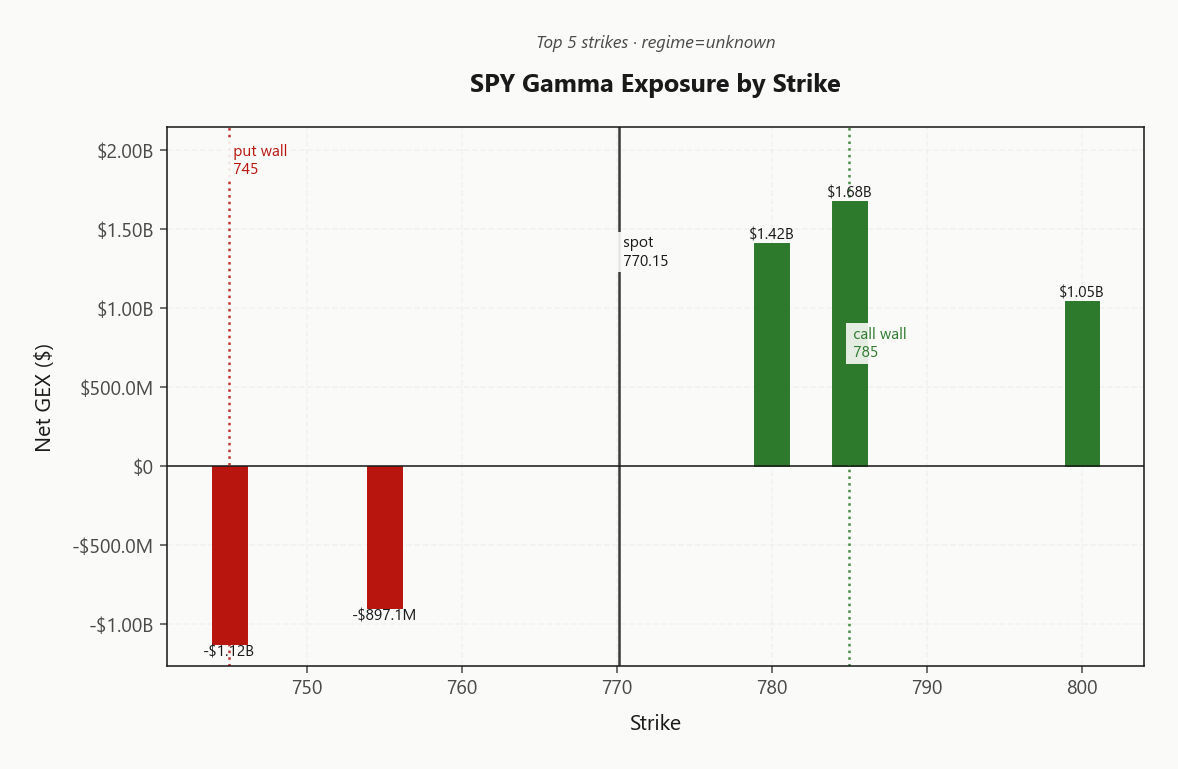
SPY's open-interest stack anchors at 700, the long-dated institutional hedging shelf that frames every tactical decision above it. The heaviest positive-GEX cluster sits at 785.00 with net GEX $1.68B - the single densest dealer long-gamma pin on the board and the magnet pulling spot into any mid-session drift.
With gamma-flip status Stored Sign Mismatch, the operating map is wall-to-wall between bookends. Call wall 785.00 caps upside into next week - expect dealer selling to accelerate on approach, mean-reversion dominant below. Put wall 745.00 is the trip-wire: a close beneath flips the hedging flow and licenses negative-gamma amplification lower.
Trade the corridor, respect the bookends. Fade strength into the call wall, buy weakness toward the pin, treat a put-wall break as the signal to step out of mean-reversion and respect momentum.
What it means for your trading
Operate wall-to-wall between 745.00 and 785.00 with the 785.00 gamma pin as the magnet; a close below the put wall is the single event that converts this liquid, mean-reverting tape into a negative-gamma slide.
Trading readDealer gamma concentrates between 745.00 and 785.00 - the operating corridor where mean-reversion dominates. Below the put wall, dealer selling amplifies downside; above the call wall, hedging caps upside into a magnet.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY net VEX at -$130.28B is deeply negative - any vol spike forces dealers to sell more delta into weakness, priming downside amplification should VVIX uncoil from 87.77. Pair that with net CHEX -$726.3K, modestly negative, and the time-decay vector is tugging dealer deltas lower rather than supporting the tape. The long-gamma pin between the walls is skin-deep: it holds only while vol-of-vol stays suppressed.
The charm pivot sits at 760 (Max Pain), roughly -1.3179250795 from spot - current bias Neutral, signal Yellow. Treat that level as the line in the sand: above, charm pulls price toward the pivot with the dealer book absorbing drift; below, vanna takes over and the VEX overhang unwinds into forced hedging.
Operating map into Monday: fade intraday pops into the call wall at 785.00 while spot sits above the pivot, but respect the put wall at 745.00 as the acceleration trigger. Do not short SPY vol into the amplification zone.
What it means for your trading
Charm pivot 760 is the single level that flips dealer flow from calm pull to vanna-driven acceleration - -$130.28B VEX means the downside unwind is loaded. Trade mean-reversion above the pivot, respect the put wall below.
Cross-Asset Confirmation
MOVE sits at 107.78 (-0.32%%) - bond vol is not co-signaling credit stress, which disqualifies the macro-shock narrative. This is an equity-domestic rotation story. Fear & Greed holds Fear at 32 against a VIX printing Steep Contango - sentiment is lagging the vol tape, the classic contrarian-long setup brewing.
SPX closed +0.73%% but the index-complex split tells the real story: QQQ at 750.08 in Positive Gamma above its flip, SPY regime unresolved, IWM at 281.68 still carrying negative gamma. Mega-cap dealer long-gamma absorbs the bid while small caps stay the fragile wing - rotation, not panic.
Bottom line: cross-asset tone Unknown, no credit co-signal, sentiment-vol divergence intact. Watch IWM for the first crack and MOVE for the first macro twitch.
What it means for your trading
Benign MOVE plus Fear sentiment against cooling vol confirms rotation under the surface, not a macro break - IWM remains the amplification wing to monitor.
Scenario EV
The scenario engine flags Unknown at signal Red - read that as the model lacking consensus, not an all-clear. SPY VRP -0.04% runs negative while IWM carries 4.02% and QQQ sits between at 0.51%; the premium is in the small-cap wing, not the index.
Writer's call: route iron condors into IWM at 21-30 DTE where VRP is clean, bracketed by call wall 285.00 and put wall 280.00. QQQ is the secondary seller against its Positive Gamma cushion above the flip 744.06. SPY stays off the short-vol menu - negative VRP means you're selling implied cheap to realized, and the gamma-flip status Stored Sign Mismatch removes the structural anchor.
Avoid the 0-7 DTE pocket where VIX9D 12.16 is depressed; the sweet spot is 21-30 DTE where Steep Contango pays the roll. Size to Standard Size - VVIX 87.77 says jump risk is cheap, not absent.
What it means for your trading
Sell IWM premium at 21-30 DTE where VRP 4.02% is clean; do not short SPY vol naked while VRP -0.04% is negative.
Actionable Summary
Regime Elevated / Watchful, pivot anchored at 760, term structure Steep Contango - the carry curve is textbook and the operating map is wall-to-wall. SPY/QQQ regime split is the lead angle: QQQ holds Positive Gamma above its flip at 744.06, SPY sits unresolved with gamma-flip status Stored Sign Mismatch, and IWM remains the fragile short-gamma wing at -$3.26B.
SELL IWM21-30 DTE iron condors against call wall 285.00 / put wall 280.00 - VRP 4.02% is the richest premium pocket in the complex. FADE SPY strength into 785.00 but do not short SPY vol naked: VRP -0.04% means you are selling cheap to realized. RESPECT745.00 as the amplification trigger - a slip there activates negative-gamma selling against net VEX -$130.28B.
AVOID 0-7 DTE vol sales where VIX9D at 12.16 is depressed; sweet spot stays 21-30 DTE. WATCH VVIX 87.77 and MOVE 107.78 - regime cracks surface there first.
What it means for your trading
Route premium sales into IWM, fade SPY into the call wall without shorting its vol, and treat the SPY put wall as the single trip-wire that flips the carry regime into amplification. Watch VVIX 87.77 and MOVE 107.78 for the first crack.
G7 coordinated diesel/oil stock release is a direct energy-vol suppressant into crude term structure - bearish for energy IV, bullish for the broader risk complex via inflation-expectation cooling.
CNBC Investing Club flagging Friday rally sustainability is a sentiment check - relevant because SPX +0.73%% matches the vol-cooling narrative tonight.
OPEC+ capacity review delay signals supply-side uncertainty into Q4 - watch for energy-vol pass-through to the broader macro complex and MOVE sensitivity.
Bond sell-off bottoming thesis matters because a yield reversal would compress MOVE further and extend the equity-vol carry regime - directly reinforces tonight's calendar trade.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.31 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $943.2M. The gamma flip sits at N/A, with the call wall at 785.00 and the put wall at 745.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 770.15. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.32% with a volatility risk premium of -0.04%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.45. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime