Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 763.46, Negative Gamma regime with net GEX -$6.37B - dealers short gamma, moves amplified. Gamma flip at 767.51 is above spot, so the tape runs with trend until reclaimed; call wall 770.00 caps upside, put wall 745.00 is the panic trigger. Dealer vanna at -$68.51B means a vol pop forces delta selling - hostile into any VIX spike; charm at $747.4K is mildly supportive into the close. VIX at 16.81 with VIX9D at 14.20 and VIX3M at 18.37 = steep contango, structural vol-sell carry. VRP on SPY is 2.52% vol points; IWM VRP is richest at 9.34%, QQQ in between at 3.53%. Bottom line: iron condor 30-45 DTE on IWM for the richest VRP, respect 745.00 as the regime tripwire, half-size any directional short vol until SPY reclaims the flip.
SPY trades below its gamma flip at 767.51 with net GEX at -$6.37B - dealers short gamma, moves amplified until spot reclaims 767.51. IWM echoes the fragile posture with the richest VRP at 9.34%, while QQQ sits in an undefined regime (stored_sign_mismatch) with positive net GEX. Steep VIX contango and benign VVIX say vol sellers still get paid - but size standard, not aggressive, with Fear & Greed at 30.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
763.46
767.51
-0.53%
770
745
760
-$6.37B
Short gamma
QQQ
741.57
-
-
750
740
725
$1.57B
-
IWM
276.78
290.71
-4.79%
280
275
285
-$4.87B
Short gamma
VIX
16.80
17.19
-2.26%
20
16
19
-$29.17M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
13.18
10.66
+2.52
2.13
2.13
1.15
QQQ
18.64
15.11
+3.53
2.50
1.40
0.80
IWM
19.94
10.60
+9.34
2.74
2.35
1.26
VIX
71.38
95.88
-24.50
-102.59
0.32
5.03
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
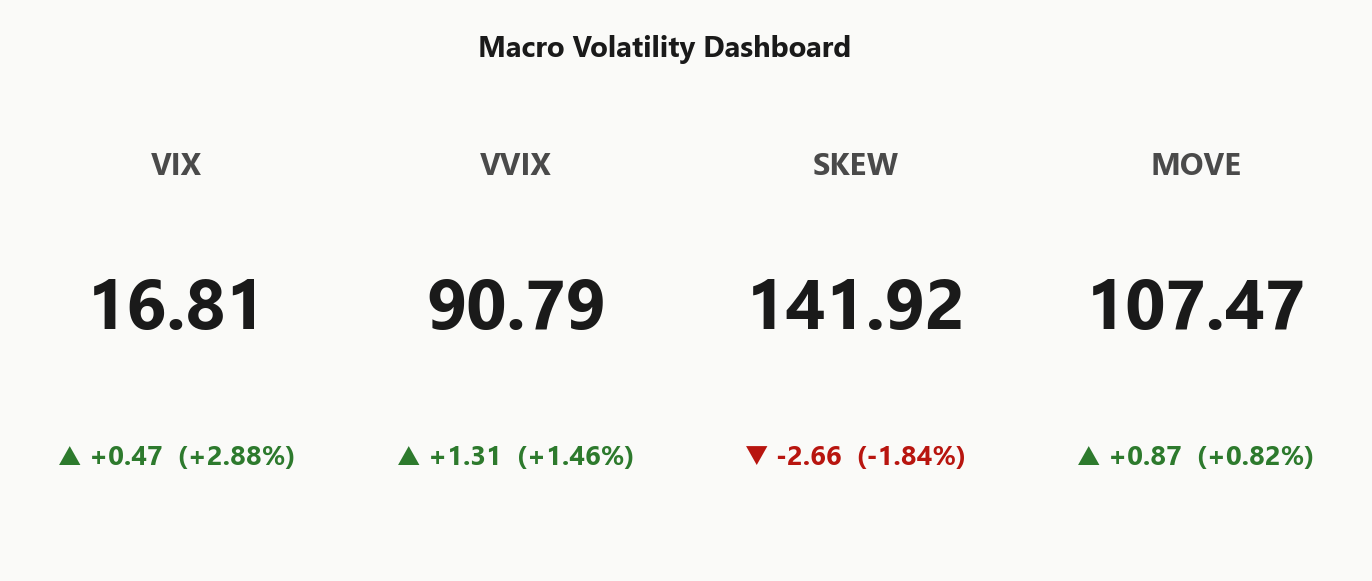
16.81
+2.88%
VVIX
90.79
+1.46%
SPX
7,664.73
+0.17%
SKEW index
141.92
-1.84%
MOVE (bond vol)
107.47
+0.82%
VIX term (9d/30d/3m/6m)
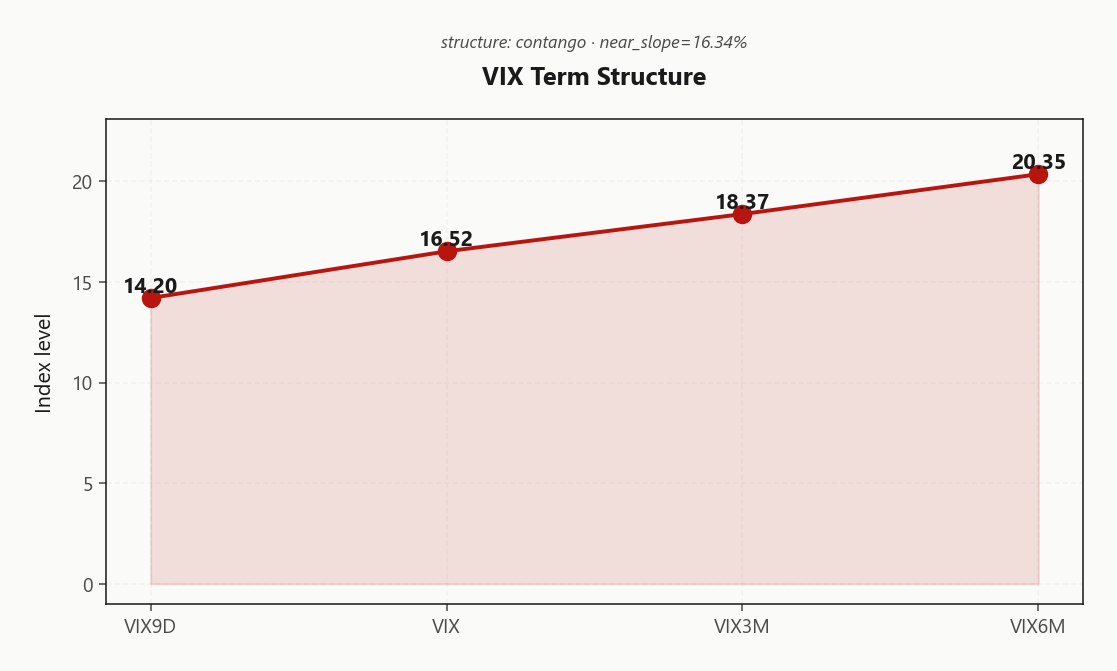
14.20 / 16.52 / 18.37 / 20.35
Steep contango
VVIX / VIX
5.40
Normal
Regime
Elevated / Watchful
Regime Assessment
Current regime reads Elevated and labels out as Elevated / Watchful with VIX at 16.81 - elevated enough to respect, nowhere near panic territory. Transition probabilities confirm the posture: panic odds over the next five sessions sit at 0.05 while reversion to low vol over ten sessions runs 0.45. The distribution is skewed toward staying put, not escaping either way.
Half-life at 15 sessions is the operative number - this is a sticky watchful regime, not a transition zone. Position for stability over the condor window, not for a regime shift that priced transition tails do not support. Signal color Yellow is watchful, not alarmed; standard sizing holds, no half-size dampener required.
Trade the regime that is, not the one you fear: elevated-but-stable favors the Iron Condor at 30-45 DTE, respects the SPY put wall at 745.00 as the only level that would force a regime re-label, and leaves cross-asset divergence True intact as a pair-trade tell rather than a hedge trigger.
What it means for your trading
Elevated but sticky - Elevated / Watchful with a 15-session half-life and panic odds only 0.05. Plan the next two weeks around stability, not transition; standard-size the condor and let the SPY put wall at 745.00 be the only line that forces a re-label.
Trading readVIX, VVIX, SKEW, and MOVE all elevated but confirming each other - no divergence yet. Confirmation means the regime is sticky; watch for VVIX breaking higher as the first regime-shift tell.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure prints Contango across every segment: VIX9D at 14.20 sits well below VIX at 16.52, which itself trades under VIX3M at 18.37. Near-slope at 16.34%% confirms no front-end event premium - the curve is pricing calm into the next two weeks, not a known catalyst.
Forward buckets ramp cleanly: the 30→60 forward prints 19.2283683655 and 60→90 steps to 22.1537378336. Carry concentrates mid-curve, so the richest roll-down lives in the 30-45 DTE window where contango slope and theta both work for sellers.
Regime label reads Steep contango - vol sellers favored with signal Green - structural carry is on, vol sellers get paid. Route 30-45 DTE short-vol structures into the mid-curve bucket; the term shape is the tailwind, not the warning.
What it means for your trading
Steep contango every segment with the richest forward carry in the 30-45 DTE window - regime Steep contango - vol sellers favored, signal Green, vol sellers favored. Size standard; the term structure is the setup, not the risk.
Trading readClean contango every segment - no event premium, structural carry on. Short the front, hedge the back if sizing up vol sales; the slope rewards 30-45 DTE positioning.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 13.18% prints above HV20 at 10.66 and HV60 at 11.11, leaving a modest SPY VRP of 2.52% vol points. Active, not stretched - the premium is there to harvest, but mega-cap index vol is not where the richness lives.
IWM VRP stands alone at 9.34%, the richest short-vol zone across the complex. QQQ sits mid-tier at 3.53%, routine harvest territory. Options are rich to realized on small-cap, routine on mega-cap - index premium-sale concentration tilts to IWM, no debate.
Critically, there is no realized vol acceleration signature yet - dealer short gamma below the 767.51 flip has not translated into an HV pickup. The vol selling thesis holds until SPY churn forces HV20 to converge on IV; until then, route the condor on IWM and respect 745.00 as the regime tripwire.
What it means for your trading
IWM VRP at 9.34% is the standout harvest zone with SPY VRP at 2.52% active but lean - concentrate 30-45 DTE premium sales on IWM. No realized vol acceleration yet despite SPY negative gamma, so the short-vol thesis is intact until HV20 at 10.66 starts closing on ATM IV at 13.18%.
Skew Convexity
Quarter-delta put skew runs steep across the index complex. SPY prints a 2.13% skew with smile ratio 1.13% - put-25d IV at 18.77% trades well above ATM at 17.49%, while call-25d IV at 16.64% sits below ATM. Downside is bid, upside flat - the book is paying for protection, not chasing calls.
IWM carries the richest put-wing bid at 2.74%, consistent with its leanest regime posture and the fattest VRP at 9.34%. QQQ at 2.5% matches its own tape lean. The signal reads Skew Steep - convexity is being accumulated, not sold.
Trade implication: naked puts are expensive relative to flat call wings. Favor put-spreads to cap wing cost, and lean the condor's harvest on the call side where no upside conviction is being paid for. The clean short-vol expression is call-wing sales against defined-risk put structures - not symmetric wings.
What it means for your trading
Steep put skew across the complex with IWM at 2.74% leading SPY at 2.13% - protection bid, upside flat. Route call-wing sales as the cleaner condor leg; use put-spreads over naked puts to avoid overpaying wing convexity.
Vol-of-Vol Structure
VVIX prints 90.79 against VIX at 16.81 - a ratio of 5.40 that lands squarely in Normal territory. No jump-risk premium is being bid into the vol-of-vol surface; the tape is not pricing a bimodal outcome, and the signal reads Green.
That matters because VVIX is the gate on sizing. Below the panic threshold, the vanna hostility implied by negative dealer VEX stays latent, not acute - a vol pop would activate it, but the market is not currently paying for that risk. Sizing guidance therefore holds at Standard Size, no dampener applied.
Translation: short-vol structures 30-45 DTE deserve conviction weight. Iron condors, defined-risk credit - not half-size. The moment VVIX breaks higher, this call flips; until then, the carry is yours to collect.
What it means for your trading
VVIX at 90.79 with a Normal label and Standard Size guidance - convinction-sized short vol is warranted, no half-size dampener, pending any break in the VVIX regime.
Dispersion Spread
Index IV stacks in a clean tier: IWM at 19.94% towers over QQQ at 18.64% and SPY at 13.18%, with cross-strike dispersion at 67.05 and cross-expiry at 2.43. Cross-asset tone reads Unknown and the dispersion signal prints Moderate - moderate correlation at elevated vol, which means index wings do not cover single-name tail risk.
The implication is routing, not sizing. Index premium-sale concentrates on IWM where the tier, the VRP at 9.34%, and the 2.74% put skew combine into the cleanest short-vol economics in the complex. SPY is too lean to pay the carry, QQQ sits mid-tier with mega-cap positive gamma distorting the fair value. Keep single-name directional exposure in named flow - index condors will not hedge an idiosyncratic mega-cap move.
What it means for your trading
Clean index IV tier with IWM at 19.94% above QQQ at 18.64% and SPY at 13.18% plus Moderate dispersion routes index premium-sale onto IWM and keeps single-name risk off the index wings.
Liquidity & Microstructure
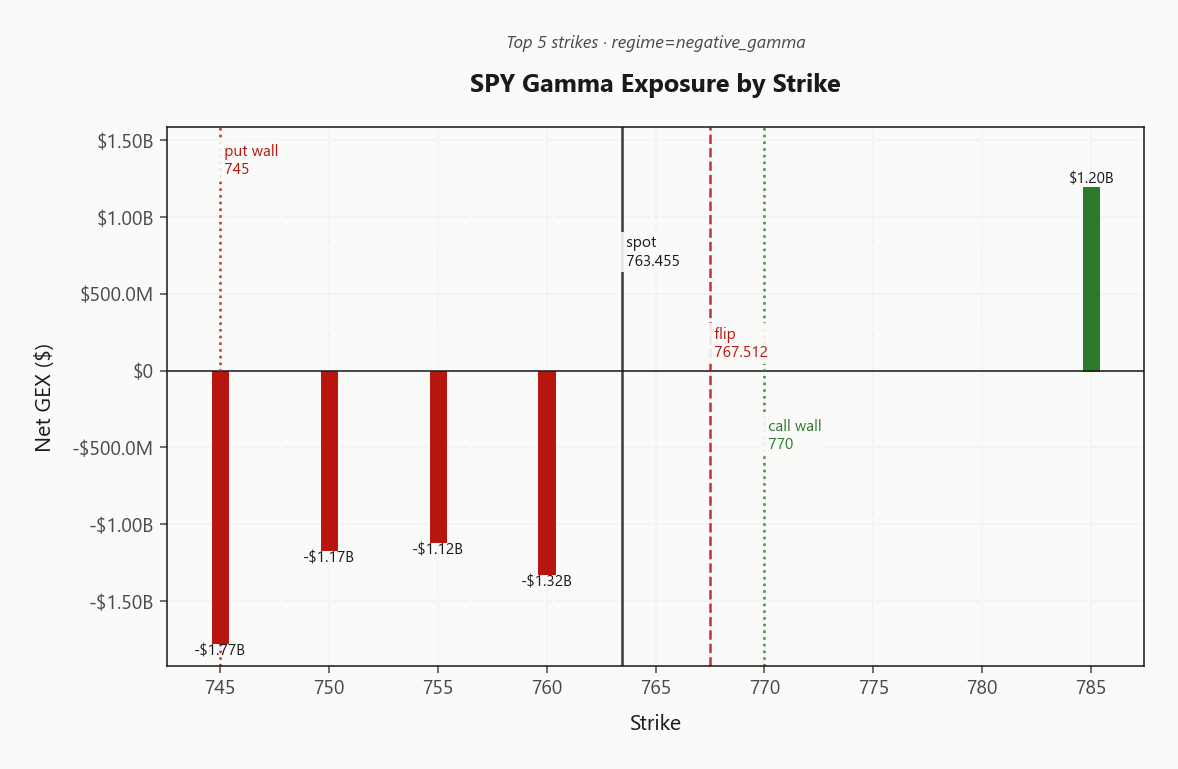
The dealer book is organized around a single dominant pole: 745.00 carries net GEX of -$1.77B against total OI of 384213, making it the tape magnet below spot. The gamma flip at 767.51 sits above spot at 763.46 - that gap is the regime line, and until it closes, dealer hedging amplifies rather than dampens directional flow.
Topology is asymmetric by design: the call wall at 770.00 caps rallies through forced supply, the put wall at 745.00 is the tripwire where negative-gamma convexity turns reflexive, and the highest OI strike at 700 anchors the book's center of mass. Zero-DTE is only 1.6% of total GEX - dated gamma, not expiry-day flow, dictates behavior.
Translation: fade strength into 770.00, respect weakness toward 745.00, and treat any reclaim of 767.51 as the only clean regime-off signal.
What it means for your trading
Deep, dated OI concentration below spot with the flip at 767.51 overhead defines a negative-gamma tape where dealer flow amplifies down-moves - 745.00 is the tripwire, 770.00 is the ceiling.
Trading readDealer gamma stacks negative from 745.00 through spot with the heaviest concentration at 745.00 - below the flip, dealer selling amplifies down-moves. 770.00 caps upside; the asymmetry says fade strength, respect weakness.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits at -$68.51B - deeply negative and the single most hostile Greek on the book. A VIX pop forces delta-selling into any downside, so a vol spike doesn't just mark positions, it compounds them. With spot below the gamma flip and VVIX only at 90.79, the vanna risk is latent - not acute, but one shock away from active.
Charm offsets the picture only modestly. Net CHEX at $747.4K is mildly positive, nudging dealers to buy into the close as time decays long-dated gamma. The charm pivot at 760 is the single level where dealer bias flips; spot at 763.46 runs -0.4525479563% off that pivot, leaving current bias Neutral.
Trade implication: respect the vanna asymmetry. Short vol structures size standard per stable VVIX, but any VVIX break higher activates the delta-selling cascade instantly - half-size directional short vol until SPY reclaims the flip.
What it means for your trading
Hostile vanna at -$68.51B is latent today only because VVIX at 90.79 is benign; charm at $747.4K offers a close-of-day buffer but doesn't neutralize the risk. Watch the charm pivot at 760 as the bias-flip trigger.
Cross-Asset Confirmation
The index complex splits cleanly today - SPY confirmed in Negative Gamma with spot below the flip, while QQQ runs an undetermined regime carrying positive net GEX. Mega-cap is the cushion, broad index and small-cap are the fragility. QQQ at 741.57 trades on a stable gamma pocket; IWM at 276.78 echoes SPY's hostile posture below its own flip. Trade the divergence, don't bet against it.
MOVE at 107.47 is elevated but not a credit crisis print - rates vol is confirming equity caution, not screaming contagion. Fear & Greed at 30 (Fear) says sentiment is already defensive, which trims the reflexive-downside tail. VIX futures basis at Contango with a 11.2%% spread shows no stress term structure building - the curve is pricing carry, not panic.
Read: a Unknown cross-asset tape with regime divergence Unknown. This is a mean-revertible setup - route index vol-sale on IWM, keep QQQ as the stability anchor, and respect SPY's put wall as the regime tripwire.
What it means for your trading
SPY/QQQ regime divergence with defensive sentiment at Fear and no stress in VIX basis points to a cross-asset mean-revertible setup, not a compounding credit event - fade walls on index, concentrate premium-sale where VRP is richest.
Scenario EV
Scenario EV ranks Iron Condor as the top structure at 47, clear of put-spread at 37. With VRP active across the complex and VVIX at 90.79 labeled Normal, defined-risk two-sided premium beats paying up for directional downside - sizing guidance holds at Standard Size, no half-size dampener.
Optimal DTE window at 30-45 sits in the middle of the contango curve, where forward 19.2283683655 and 22.1537378336 stack richest. VIX9D at 14.20 under VIX3M at 18.37 locks in structural carry; theta compounds through the belly, not the front.
Route the condor on IWM where VRP at 9.34% dwarfs SPY 2.52% and QQQ 3.53%. Call wings cheaper than put wings per 2.13% skew; respect 745.00 as the regime tripwire.
Primary structure: route an Iron Condor 30-45 DTE on IWM, where VRP at 9.34% clears SPY at 2.52% and QQQ at 3.53%. Scenario EV score 47 beats the put-spread alternative at 37, and VVIX at 90.79 keeps sizing Standard Size - no dampener warranted.
Respect the SPY put wall at 745.00 as the regime tripwire: a breach flips the tape from Elevated / Watchful into compounding selloff via net VEX at -$68.51B. Fade the call wall at 770.00 - dealer gamma caps rallies and the charm pivot sits at 760 with bias Neutral.
Avoid naked single-name short vol; dispersion labeled Moderate leaves idiosyncratic risk uncovered by index wings. Watch VVIX at 90.79 and MOVE at 107.47 - a VVIX break higher activates the latent vanna hostility that current benign vol-of-vol is masking.
What it means for your trading
Iron condor 30-45 DTE on IWM is the trade; SPY 745.00 is the line that redefines the regime, and 90.79 VVIX is the signal that converts latent vanna risk into realized flow.
UK 30-year gilt yield breaking 6% for the first time since 1998 is a global long-end rate stress signal that could pressure US equity multiples and widen credit - relevant for anyone running duration or multiple-sensitive exposure.
Japan PM claiming yen policy will build confidence after failed US intervention keeps the dollar-yen carry unwind risk alive - matters for global vol as currency volatility bleeds into cross-asset positioning.
Three oil tankers hit by projectiles in the Hormuz strait is a direct geopolitical shock to the energy complex - energy-vol linkage can lift index skew via rates and inflation re-pricing.
China suspending fuel exports pushed oil up 2% - compounds the Hormuz news into an energy-supply narrative that could feed through to CPI and rates expectations.
SpaceX launching Google TPUs into orbit toward space-based data centers is a durable AI-infrastructure signal - supports the mega-cap positive-GEX positioning narrative in QQQ.
Two 'Magnificent Seven' options trades at 50% above 30-day average volume confirms the mega-cap positioning concentration showing up in today's top GEX movers - flow and positioning aligning.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.80 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.51 against a spot of 763.46. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 13.18% with a volatility risk premium of 2.52%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.81. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime