Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 761.31 sits fractionally below the gamma flip at 766.39, net GEX -$10.38B - dealers are short gamma and amplifying moves until spot reclaims the pivot. Key levels: call wall 770.00, put wall 760.00 (also max pain 760.00), flip 766.39 - spot is pinned at the put wall which is why tape feels heavy but orderly. Dealer vanna -$54.31B is deeply negative so any vol pop forces dealer delta selling - hostile; charm $3.7M is modestly supportive into close. Vol read: VIX 16.96 with term structure in Contango (slope 13.32%%), VVIX 94.28 normal, VRP 2.34% - options are paid over realized but the premium isn't extreme. IWM carries the richest VRP in the complex at 9.1% vs its 10.59 realized - that's the cleanest premium-sale fit. Bottom line: iron condor 30-45 DTE on IWM harvests the fattest VRP while SPY grinds the flip; fade strength into 770.00, respect 760.00, cover if VVIX breaks above the ratio threshold.
SPY 761.31 trades fractionally below the gamma flip at 766.39 with dealers short gamma - moves get amplified until spot reclaims the pivot. VIX term structure in Steep Contango with VVIX at 94.28 says vol carry is paid but the market is quietly bidding vol-of-vol. IWM's 9.1% VRP is the richest premium-sale fit in the complex; SPY and QQQ sit in symmetric negative-gamma below their respective flips.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
761.31
766.39
-0.66%
770
760
760
-$10.38B
Short gamma
QQQ
738.15
739.08
-0.13%
740
730
725
-$1.44B
Short gamma
IWM
278.50
291.16
-4.35%
280
275
285
-$4.47B
-
VIX
16.97
17.04
-0.40%
20
16
19
-$27.14M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
13.07
10.73
+2.34
1.75
2.13
1.16
QQQ
18.21
15.24
+2.97
1.56
1.40
0.92
IWM
19.69
10.59
+9.10
1.74
2.35
1.39
VIX
77.64
97.22
-19.58
-113.37
0.32
0.96
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
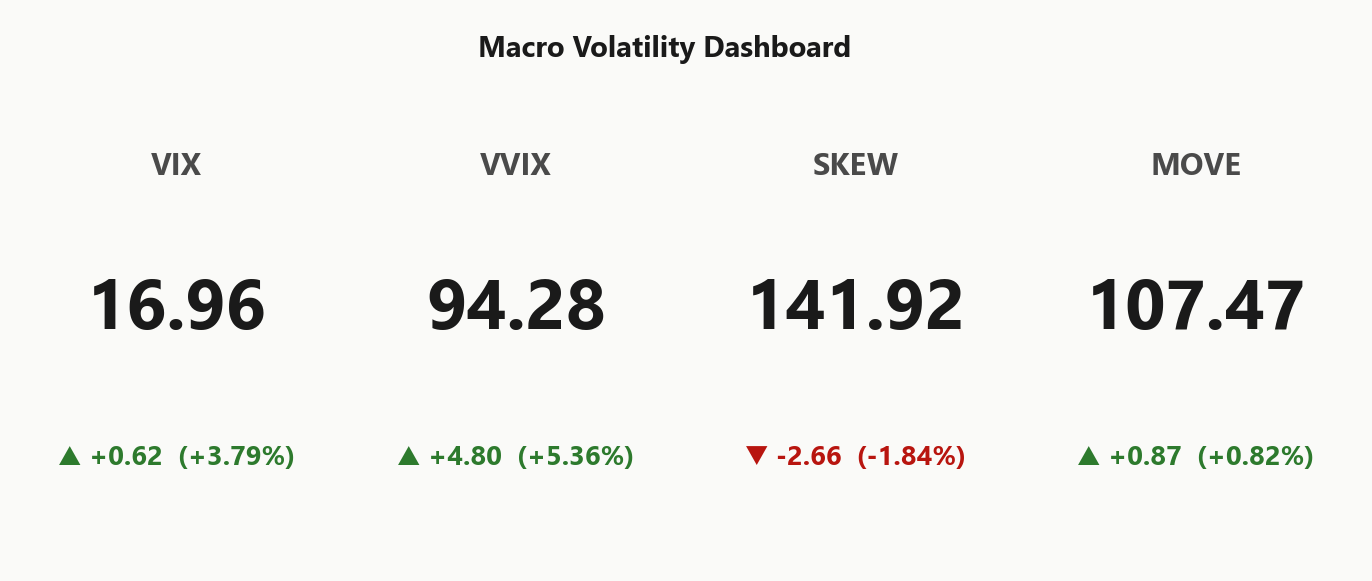
VIX
16.96
+3.79%
VVIX
94.28
+5.36%
SPX
7,642.60
-0.12%
SKEW index
141.92
-1.84%
MOVE (bond vol)
107.47
+0.82%
VIX term (9d/30d/3m/6m)
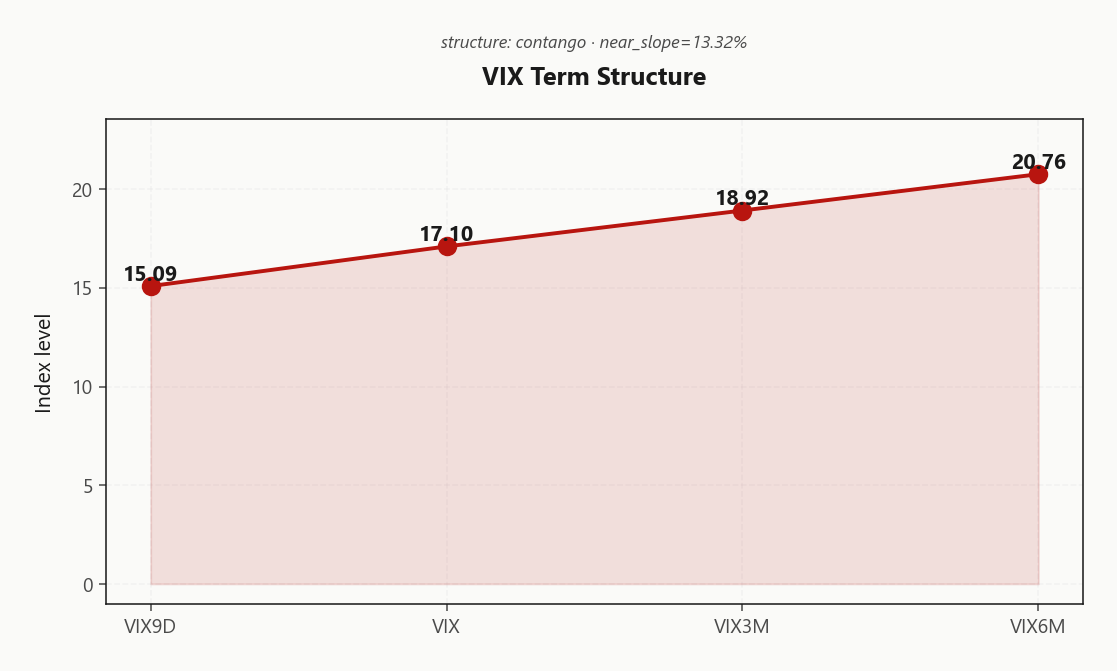
15.09 / 17.10 / 18.92 / 20.76
Steep contango
VVIX / VIX
5.56
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated (Elevated / Watchful) with VIX anchored at 16.96 - watchful, not panicked. The transition probability to panic over the next five sessions sits at 0.05, while the move back to low-vol over ten sessions prints 0.45. Standard carry size remains appropriate; this isn't a regime that demands defensive sizing yet.
Half-life of 15 sessions is the key number - the setup is sticky, not transient. Carry trades have runway to collect the paid premium without racing a decaying regime. Forward vol in Steep Contango and VVIX/VIX at 5.56 (Normal) confirm the structural edge.
Panic probability is low but non-zero. Keep protection cheap and nearby - put spreads over naked wings, size per Standard Size, and respect the pivot at 760 as the regime-break tell.
What it means for your trading
Elevated/watchful regime with a 15-session half-life gives carry time to work at standard size, while 0.05 panic probability keeps cheap protection on the shelf.
Trading readVIX, VVIX, SKEW and MOVE all elevated-but-orderly - no divergence pointing to imminent regime shift, though VVIX's upward drift is the quiet signal to monitor.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure prints textbook Steep Contango - VIX9D at 15.09 below spot VIX at 17.10 below VIX3M at 18.92, with near-slope 13.32%%. The curve is structural, not event-driven; no near-dated kink is pricing a discrete catalyst, so roll-down is clean rather than compensation for a known risk.
Forward 30→60 lands at 19.7672608118 and 60→90 at 22.4496948754 - steady step-ups that pay vol sellers to warehouse term exposure without reaching for max event convexity. The 30-45 DTE bucket sits in the sweet spot where structural carry compounds before the long-dated gamma decay accelerates.
Carry is paid but not free - Steep contango - vol sellers favored favors sellers while VVIX at 94.28 and ratio 5.56 keep sizing at Standard Size. A VVIX breakout is the regime-break tripwire; until then, the forward surface is the vol seller's friend.
What it means for your trading
Term structure in Steep Contango with forward 30→60 at 19.7672608118 prints a clean roll-down edge - 30-45 DTE is the structural sweet spot. Carry is favored at Standard Size but watch VVIX for regime-break risk.
Trading readSteady Steep Contango with near-slope 13.32%% - vol carry pays, the market isn't bracing for a discrete shock, and 30-45 DTE sellers get the cleanest roll-down.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 13.07% sits above HV20 at 10.73, printing a VRP of 2.34% - Moderate Premium. RV5 at 7.48 runs well below the 20-day, so the near-tape has been quieter than the implied bid admits. Standard harvest territory, not stretched.
IWM is where the premium concentrates. ATM IV 19.69% over HV20 10.59 prints 9.1% VRP - the richest fit in the complex. QQQ sits between the two with VRP 2.97%, confirming the small-cap outlier isn't an artifact.
Options are rich versus recent realized across all three, but the premium is being paid up unevenly. Index iron condor on IWM harvests the fattest spread; SPY is a size-standard carry; QQQ an acceptable second vehicle. No sign of panic steepening - this is paid vol, not scared vol.
What it means for your trading
IWM carries the richest VRP at 9.1% versus SPY's active-but-moderate 2.34% - route premium-sale flow into small-cap first, index second, mega-cap third.
Skew Convexity
SPY quarter-delta put IV prints 18.03% against ATM 16.83% and a quarter-delta call at 16.28%, leaving the skew measure at 1.75% and the smile ratio at 1.11%. Puts carry a measured bid while the call wing sits flat - this is orderly downside hedging, not panic steepening. Protection is being accumulated, not chased.
The flat call wing is the tell: no one is paying up for upside convexity, which is consistent with spot sitting below the gamma flip and the complex trading in aligned negative-gamma. Call-side premium is a free-option bid when conviction returns - right now, it isn't being paid. Put skew remains the only wing earning rent, and it isn't shrieking.
Given SPY VRP at 2.34%, naked long puts are expensive relative to the hedge delivered; put spreads dominate on cost efficiency. The wings are cheap enough to spread, the body is rich enough to finance, and the smile isn't pricing a discrete tail - exactly the convexity profile where defined-risk downside beats outright premium.
What it means for your trading
Skew at 1.75% and smile ratio 1.11% show hedgers present but not panicked, with the call wing flat - favor put spreads over naked puts given the active VRP and the lack of upside convexity bid.
Vol-of-Vol Structure
VVIX prints 94.28 against VIX 16.96 for a VVIX/VIX ratio of 5.56 - squarely in the Normal vol-of-vol regime. No jump premium is being paid in the surface, which means carry structures can run at Standard Size without a convexity discount. The market isn't pricing a binary; it's pricing drift.
That said, VVIX added 5.36%% on the session while spot stayed pinned - a quiet divergence where the second derivative bids even as the first stays anchored. It's a soft tell, not a trigger: the ratio at 5.56 is still standard carry territory, and the regime label hasn't flipped. Full size remains the correct read.
The explicit sizing trigger is a VVIX breach above 120 - current prints sit well below that line. Until it breaks, iron condors and calendar sells harvest the fattest VRP in the complex without a vol-of-vol tax. Monitor the drift; don't preempt the breach.
What it means for your trading
VVIX at 94.28 and the VVIX/VIX ratio at 5.56 keep the regime Normal and sizing at Standard Size; the quiet VVIX bid against flat spot is a watch-item, not a cut signal.
Dispersion Spread
Index-level IV on SPY prints at 13.07% with cross-strike dispersion at 62.26 and cross-expiry at 2.43 - the complex isn't moving as a correlated block, and single-name premium isn't collapsing into the index the way a true dispersion setup requires.
IWM ATM IV at 19.69% dislocates meaningfully above SPY at 13.07% and QQQ at 18.21%, so the small-cap wing carries idiosyncratic premium rather than reflecting a shared complex-wide bid. Cross-asset regime reads Aligned on direction but the vol levels disagree - single-name hedges against SPY won't offset IWM stress cleanly, and single-name strangles leak basis against the index book.
Preferred vehicle for premium sale is the index iron condor, not a dispersion trade or single-name strangle grid. Correlation is moderate, not depressed, so selling index vol against long single-name vol gives up carry without the correlation collapse that pays dispersion. Harvest IWM VRP at 9.1% via condor; leave single-name premium alone.
What it means for your trading
IWM's dislocation above SPY and QQQ is idiosyncratic small-cap richness, not a complex-wide signal - sell it via index iron condor, skip the dispersion book while correlation sits moderate.
Liquidity & Microstructure
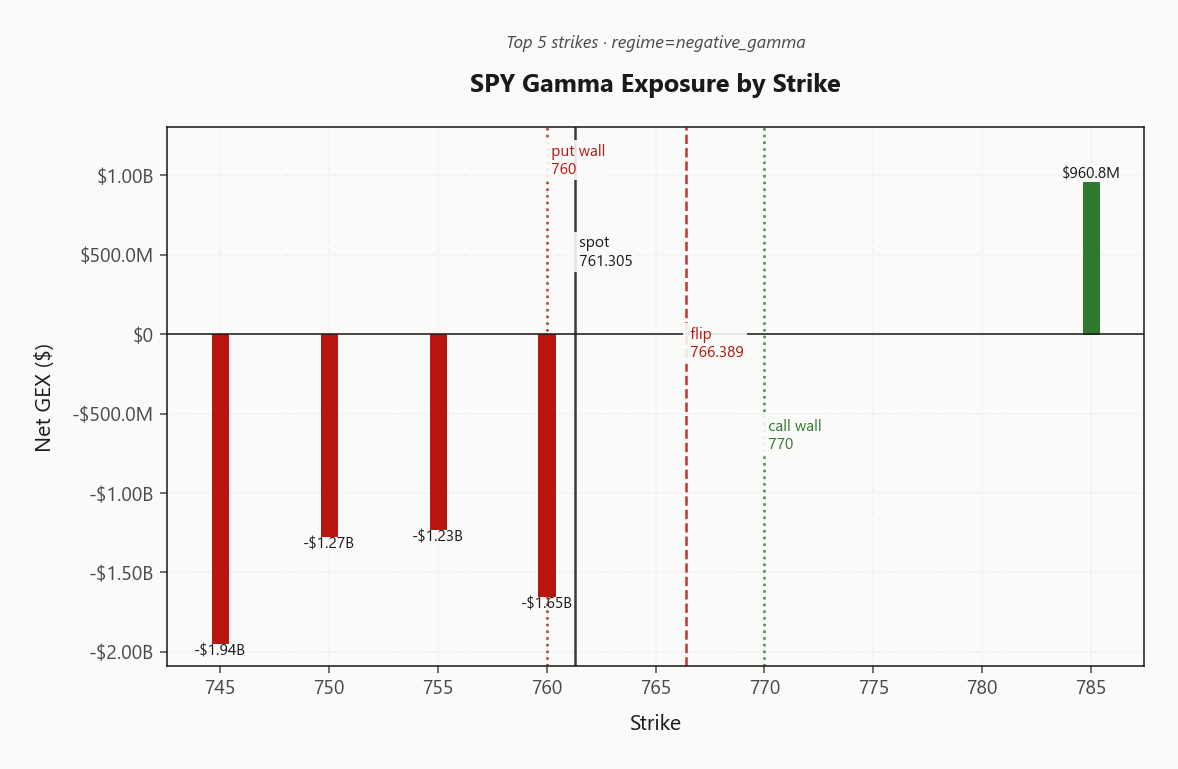
SPY's OI cluster parks at 700, far below spot 761.31 - a legacy book, not the pressure point. The live level is the gamma flip at 766.39; spot trades -0.1714161867% below it, which is the entire reason the tape is amplifying moves rather than dampening them. Reclaim flips the dealer response from selling-into-weakness to buying-into-strength; until then, every push lower gets the extra push dealers are forced to deliver.
The put wall at 760.00 is doing double duty as max pain 760.00, which is why spot feels pinned rather than crashing - the magnet is working even inside negative gamma. Overhead, the call wall at 770.00 caps strength and is where fades belong. The accelerant sits between: the top negative-GEX strike at 745.00 prints -$1.94B, the band where dealer hedging compounds any directional break.
Trade the book, not the cluster: respect 760.00 as a floor-magnet, fade into 770.00, and treat a clean reclaim of 766.39 as the regime switch that unlocks the long side.
What it means for your trading
The gamma flip at 766.39 is the single level that matters; the put wall at 760.00 magnetizes spot while 745.00 marks where dealer hedging turns an orderly drift into an accelerant.
Trading readNegative-gamma stack sits right at and below spot with the put wall 760.00 acting as magnet - dealers amplify moves until spot reclaims the flip, so the strikes to watch are the ones directly overhead, not the deep OI cluster at 700.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna at -$54.31B is deeply negative - the hostile side of the book. Any VVIX breakout forces mechanical delta selling as dealers rebalance against rising implieds, which compounds downside rather than dampening it. With VVIX at 94.28 and the VVIX/VIX ratio reading Normal, there's no jump premium being paid yet, but the vanna configuration means the first vol pop does the damage, not the second.
Charm at $3.7M is modestly positive - time decay buys dealers back into the close and provides a mild intraday tailwind. That offset is real but secondary; if VVIX breaks higher, vanna overwhelms charm and the supportive drift evaporates. The pivot sits at 760 (Put Wall), with current bias reading Neutral - this is the single flow-flip level where dealer behavior reverses.
Trade implication: carry structures can still run at Standard Size, but keep protection within reach. A VVIX break and a loss of 760 together is the signal to cut, not either in isolation.
What it means for your trading
Vanna is the hostile greek and charm the mild offset; the complex is one VVIX pop away from compounding downside, with 760 as the flow-flip trigger.
Cross-Asset Confirmation
Rate-vol speaks first: MOVE at 107.47 is elevated but orderly, nowhere near shock territory. No credit event is pricing through the curve, which matters because MOVE leads equity vol when the stress is macro. The absence of that signal reframes today's negative-gamma complex as an equity-positioning problem, not a systemic one.
Sentiment confirms the setup: Fear & Greed at 27 (Fear). Positioning is defensive, hedges are on, and the contrarian floor is firming - but a firming floor is not a buy signal while spot sits below the flip. The cross-asset picture is uniform: QQQ at 738.15 and IWM at 278.50 both trade below their respective flips alongside SPY. Regime is Aligned.
Operational read: no divergence trade available - the complex moves as one block. Wait for a flip reclaim in any one leg before fading the caution; MOVE breaking higher is the signal that would upgrade this from equity-centric to macro.
What it means for your trading
Rate-vol orderly, sentiment at Fear, QQQ and IWM both below their flips with SPY - regime Aligned and no divergence trade. Equity-centric caution, not a credit shock; the first flip reclaim is the all-clear.
Scenario EV
Scenario scoring favors Iron Condor at 47 versus put-spread at 35 - the directional risk premium isn't being paid in this regime, so defined-wing premium sale wins outright. Optimal DTE lands in the 30-45 bucket, which captures structural roll-down in Steep Contango without stepping into max event convexity.
IWM is the cleanest vehicle: VRP at 9.1% against HV20 10.59 is the richest premium in the complex, SPY at 2.34% and QQQ at 2.97% sit well behind. Contango carry on the 30→60 forward at 19.7672608118 compounds the short-vol edge, and small-cap wings price wide enough to anchor the condor without reaching for strikes.
Size Standard Size per vol-of-vol regime - VVIX at 94.28 and the ratio at 5.56 sit in normal territory, so no jump discount is required. Cut gross if VVIX breaks higher or SPY loses 760.00; those are the two triggers that invalidate the carry.
What it means for your trading
Iron condor 30-45 DTE on IWM is the trade - richest VRP, cleanest wings, contango tailwind. Standard size holds until VVIX cracks higher or SPY breaks the put wall.
RESPECT: SPY put wall 760.00 doubles as max pain 760.00 - magnet, not floor. FADE strength into call wall 770.00. WATCH flip 766.39; spot 761.31 sits -0.1714161867% below - a reclaim rotates bias from amplified to supportive.
AVOID naked short vol, chasing above the call wall, and single-name premium sale while the complex trades Aligned. Cut carry if VVIX/VIX breaks higher - regime is Elevated / Watchful with half-life 15 sessions, sticky but non-zero panic probability.
What it means for your trading
Harvest the richest VRP in the book via IWM iron condor at 30-45 DTE while SPY grinds the flip at 766.39; respect the put wall 760.00, fade the call wall 770.00, and size down the moment VVIX breaks regime.
UK 30-year gilt yields breaching 6% for the first time since 1998 is a global duration signal - long-end sovereign stress leaks into risk assets and widens term premium across curves.
Japan PM reasserting yen-support policy after failed intervention keeps JPY/USD and carry-unwind risk live - a disorderly yen move historically bleeds into US equity vol.
China suspending fuel exports is a tangible supply-side shock to global energy - watch oil tape, which cross-reads into inflation expectations and MOVE.
Indian benchmarks posting their longest weekly losing streak in 25 years is an EM-signal - synchronized global equity weakness is a watch-item for US sentiment transmission.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.97 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 766.39 against a spot of 761.31. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 13.07% with a volatility risk premium of 2.34%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.96. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime