Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 764.66 sits below the gamma flip at 768.39, net GEX -$5.28B - dealers short gamma, moves get amplified not dampened. Call wall 785.00 caps upside, put wall 745.00 is the tripwire; max pain 760.00 and highest OI at 700 tells you where the magnet lives. Dealer vanna -$83.23B is destabilizing - vol up means dealers sell more delta, downside gets a kicker if VIX pops. VIX 16.38 with term structure in Contango (vix9d 13.87 < vix3m 18.53), VVIX 91.35 normal - carry is live, VRP 1.66% on SPY is modest but IWM VRP 8.1% is rich. Fear & Greed at 29 (Fear) with QQQ regime unknown and SPY/QQQ diverged - don't lean on index correlation. Bottom line: iron condor 30-45 DTE on IWM is the recommended harvest, respect the SPY put wall as the line where dealer flow turns toxic, half-size any naked wings while vanna stays destabilizing.
SPY trades below the gamma flip at 768.39 with dealers short gamma, meaning any directional push gets amplified rather than absorbed. VIX term structure stays in steep contango with VVIX normal - vol sellers keep carry, but the destabilizing charm pivot and Fear sentiment say stay sized conservatively. Best harvest sits in iron condors 30-45 DTE where IWM's rich VRP 8.1% pays the most per unit of risk.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
764.66
768.39
-0.49%
785
745
760
-$5.28B
Short gamma
QQQ
742.94
-
-
760
730
725
$1.62B
-
IWM
279.38
292.32
-4.43%
280
275
285
-$4.32B
-
VIX
16.38
16.62
-1.42%
20
16
19
-$37.10M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.35
10.69
+1.66
1.24
2.13
1.15
QQQ
17.77
15.13
+2.64
2.41
1.40
1.00
IWM
18.95
10.85
+8.10
0.88
2.35
1.27
VIX
77.63
95.89
-18.26
-125.69
0.32
0.57
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
16.33
-0.06%
VVIX
91.35
+2.09%
SPX
7,666.45
+0.19%
SKEW index
141.92
0.00%
MOVE (bond vol)
110.00
-0.41%
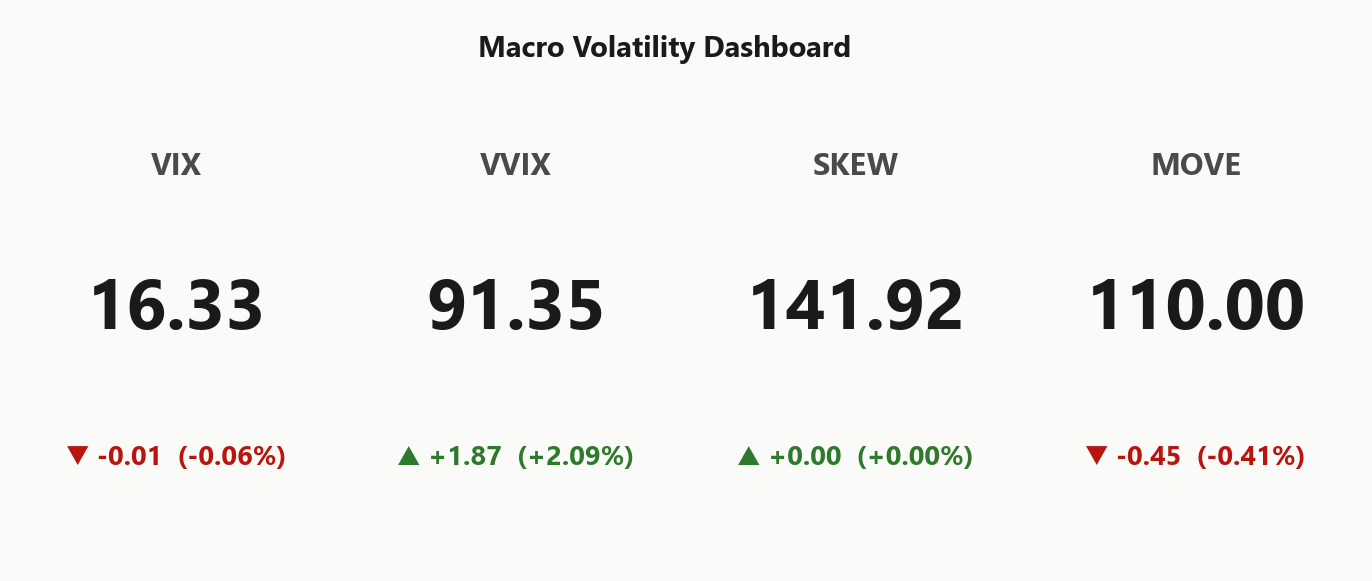
VIX term (9d/30d/3m/6m)
13.87 / 16.33 / 18.53 / 20.50
Steep contango
VVIX / VIX
5.59
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated, label Elevated / Watchful - VIX at 16.33 sits just under the 20 line, close enough to carry but far enough from calm to keep hedges live. Half-life runs 15 sessions, meaning this isn't a transient print - the tape is sticky here and mean-reversion to either tail takes real catalyst, not drift.
Transition math backs the bias: panic probability over five sessions sits at 0.05 - low, no shock priced - while the ten-session fade to low-vol prints 0.45, a moderate pull lower. The asymmetry says bias stays short-vol into carry, but the destabilizing vanna profile and SPY sub-flip positioning mean you keep wings bought, not sold naked.
Trade the regime, don't fight it: harvest premium at 30-45 DTE where theta beats gamma, size Standard Size, and treat any VVIX breakout as the signal the half-life just collapsed.
What it means for your trading
Elevated/watchful regime with low panic odds and a moderate drift toward lower vol - stay short-vol, hedged, and sized to the 15-session half-life rather than the next session's noise.
Trading readVIX 16.33, VVIX 91.35, MOVE 110.00 all confirm - no credit stress, no vol-of-vol spike, equity softness is isolated. Watch for divergence to signal regime shift.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
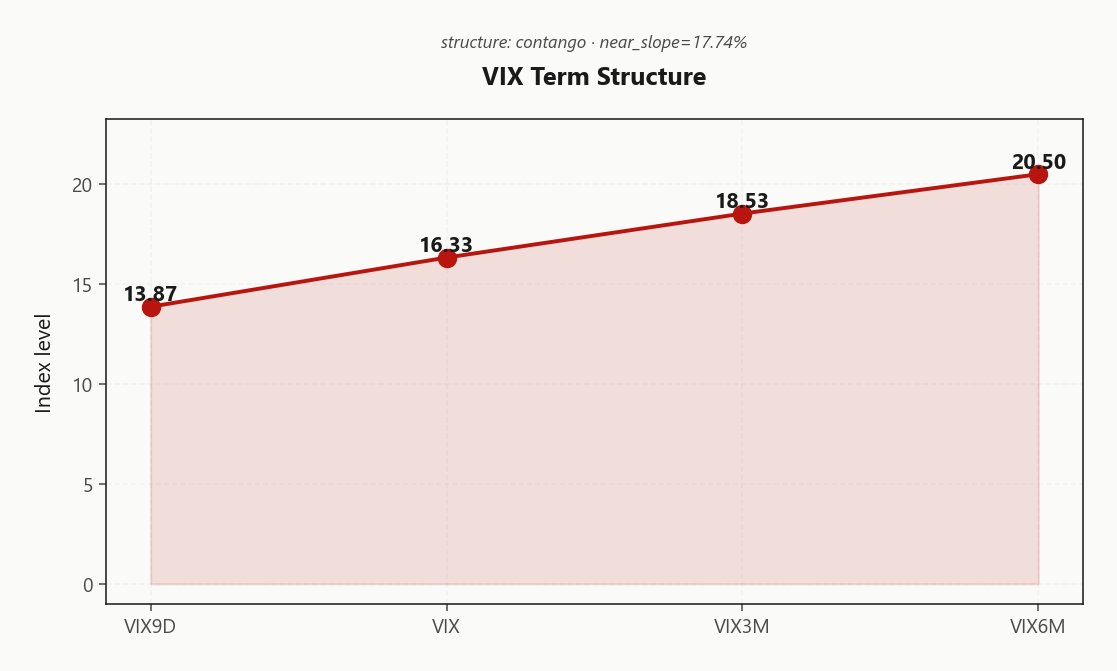
VIX term structure sits in Contango with 13.87 on the front, 16.33 at the 30-day, and 18.53 at the 3-month - a near slope of 17.74%%. Forward 30→60 implied prints at 19.5373206966, the 60→90 at 22.2966163352. That curve pays sellers of front vol who buy back further out, and the Steep contango - vol sellers favored regime tag confirms the structural carry trade is live.
The 30-45 DTE bucket is the sweet spot - far enough out that theta clears gamma per unit of vega, close enough that forward vol stays rich before the September-jobs catalyst can repice the back. Shorter tenors eat gamma risk for too little carry; longer tenors give back the slope premium. VVIX at 91.35 sits Normal, so sizing stays Standard Size.
Caveat: SPY is below the gamma flip at 768.39 with vanna Destabilizing, so carry alone doesn't justify naked wings. Harvest through defined-risk condors where IWM's rich VRP at 8.1% gives the fattest premium per unit of risk.
What it means for your trading
Steep contango from 13.87 to 18.53 keeps the short-front, long-back carry live - route to 30-45 DTE condors on 8.1% VRP, keep sizing Standard Size while vanna stays destabilizing.
Trading readContango says the market isn't pricing an immediate shock - vol-carry trade is alive, back-month vol is where sellers get paid without eating event risk.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Options are rich to recent realized across the complex, but the premium stacks unevenly. SPY ATM IV at 12.35% prints above HV20 10.69 and HV5 7.84, leaving a VRP of 1.66% - live but Thin Premium. Index wings don't pay enough to carry the destabilizing vanna book alone.
IWM VRP at 8.1% is the standout - richest in the complex and the cleanest short-vol target per unit of vega risk. QQQ VRP 2.64% sits in the middle, offering less edge than small-caps and more growth-cap event sensitivity than SPY. The dispersion favors routing harvest down the cap stack rather than leaning on index premium.
Tilt the book toward IWM wings at 30-45 DTE where theta beats gamma; keep SPY exposure defined and half-sized while vanna stays Destabilizing.
What it means for your trading
VRP is Vrp Active but concentrated in small-caps - route condors to IWM, not SPY.
Skew Convexity
SPY front-month skew sits at 1.24% with a smile ratio of 1.08% - ordered steepening, not panic. Put 25d IV at 16.66% clears ATM at 15.54%, while call 25d IV at 15.42% prints flat to the body. The left tail is being paid up; the right wing has no bid.
VIX call skew runs hot at 150.92% - upside vol-of-vol is where the hedging demand lives, not in SPY calls. That split is the tell: dealers absorb protection flow on the equity side while vega buyers reach for VIX convexity. Section signal reads Skew Steep, yellow - convex left tail, no right-side conviction.
Trade accordingly. Prefer put spreads over naked puts to avoid overpaying the wing; sell call wings where skew is cheapest and the premium is unloved. With dealer bias Destabilizing below pivot 768.387384715, buy the structure, not the raw convexity.
What it means for your trading
Put skew at 1.24% with VIX call wing at 150.92% says downside is bid in ordered fashion while upside conviction is absent - buy put spreads, sell call wings, skip naked tails.
Vol-of-Vol Structure
VVIX at 91.35 against VIX 16.33 prints a ratio of 5.59 - mid-range, Normal. The vol-of-vol tape is not pricing a binary; the kurtosis bid is absent and jump premium stays contained. Translation: carry trades clear at advertised size, no stealth hedge required against a gap in VIX itself.
Sizing guidance resolves to Standard Size - full clip on iron condors in the 30-45 window where theta dominates gamma. The combination of a Steep Contango VIX term and a benign VVIX is the textbook harvest setup; the only overlay worth paying for is a tactical wing on IWM where VRP at 8.1% is richest.
Watch VVIX breaking higher alongside a VIX pop as the regime-break trigger - above that threshold, half the clip and buy wings reflexively. Until then, the vol surface is a seller's tape and the Normal ratio keeps dealer gamma reflex muted even with SPY sitting Negative Gamma below 768.39.
What it means for your trading
VVIX/VIX at 5.59 reads Normal - standard sizing on Iron Condor harvest, no vol-of-vol premium required. Flip the switch to half-size and buy wings only if VVIX breaks higher with VIX in confirmation.
Dispersion Spread
Cross-expiry IV dispersion sits at 2.68 with cross-strike at 39.16 - a Moderate read that says single-name IVs are holding a premium to index without correlation crushing the harvest. Index vol-selling edges single-name here; dispersion is wide enough to pay but not so wide it screams idiosyncratic shock.
Growth premium shows up cleanly: QQQ ATM IV at 17.77% trades over SPY ATM IV at 12.35%, while IWM ATM IV at 18.95% prints richest in the complex - small-cap vol pays the most per unit of vega. Mega-cap earnings risk stays uncorrelated to the macro tape, so single-name premium decays on its own clock.
Route harvest to index condors, not single-name strangles - correlation is cooperative enough that the index wrapper captures the dispersion premium without eating gap risk. IWM is the preferred vehicle while its ATM IV leads the complex.
What it means for your trading
Dispersion is moderate at 2.68 cross-expiry - index condors beat single-name strangles today, with IWM at 18.95% ATM IV the richest harvest in the complex.
Liquidity & Microstructure
SPY's book sits put-dominated, with the highest OI cluster parked at 700 - a magnet well below spot that anchors downside hedging demand rather than directional conviction. The gamma flip at 768.39 rides above spot 764.66, pinning dealers on the destabilizing side: they sell into weakness and chase into strength instead of absorbing the tape.
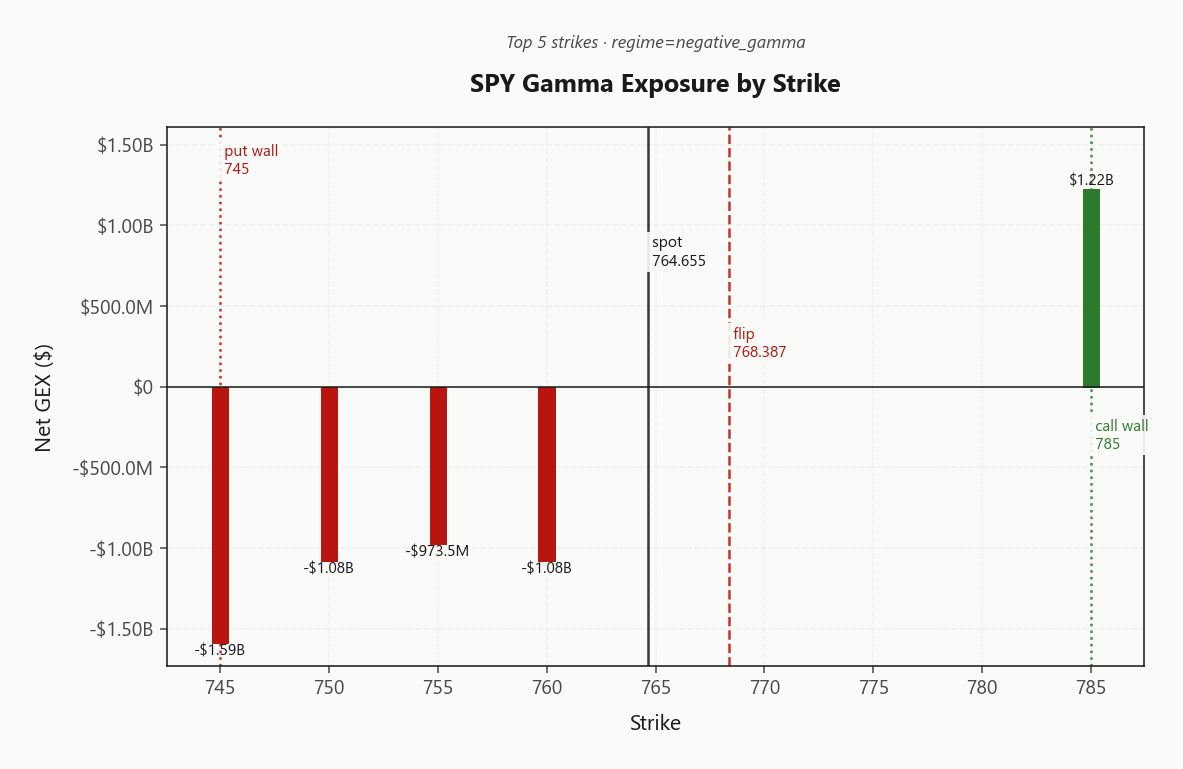
The ceiling sits at the 785.00 call wall - rallies get sold against it until flow structurally rotates. The tripwire sits at the 745.00 put wall, which doubles as the top short-gamma pocket at strike 745.00 with net GEX -$1.59B. Below that line, hedging flow turns toxic and mean-reversion dies.
Trade the range mechanically: fade into the call wall, respect the put wall as the regime-break level, and keep naked wings half-sized while dealers remain short gamma below flip.
What it means for your trading
SPY's microstructure is a put-heavy, dealer-short-gamma book bounded by 785.00 above and 745.00 below, with the 745.00 pocket carrying the heaviest short-gamma load. Treat the put wall as the structural tripwire - below it, dealer flow amplifies the move instead of damping it.
Trading readDealer short-gamma pockets stacked below spot and call wall 785.00 capping upside - fade strength into the wall, respect the put wall as the line where tape acceleration begins.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits deeply negative at -$83.23B - any uptick in vol compounds the delta-selling, so a VIX pop doesn't just hurt, it accelerates the tape lower. This is the destabilizing side of the book, and it's where the asymmetry lives today.
Charm reads -$557.7K - negative decay bleeds dealer long-delta into the close, forcing sell-flow regardless of spot direction. Stack that on top of short gamma below the flip and you get the classic amplifier: downside gets a kicker from vanna, close-of-day gets a kicker from charm, and neither needs a catalyst to fire.
The structural line is the pivot at 768.387384715 - above it, dealer flow stabilizes; below, it compounds. Current bias reads Destabilizing, red signal. Don't fight the tape here - fade strength into the pivot, respect the put wall as the acceleration zone, and keep naked wings half-sized while vanna stays this short.
What it means for your trading
Vanna -$83.23B and charm -$557.7K both lean destabilizing - any vol-up or close-of-day flow adds to dealer selling pressure. Treat the pivot at 768.387384715 as the structural line; below it, don't fade the move.
Cross-Asset Confirmation
MOVE prints 110.00 - bond vol is contained, so the equity softness isn't bleeding from a credit channel. Fear & Greed sits at 29 (Fear), which is sentiment-driven weakness, not systemic stress. No cross-asset confirmation of a shock - the tape is isolated to equities and inside equities, isolated to specific pockets.
Those pockets are where the story gets interesting. QQQ at 742.94 is holding mega-cap bid while IWM at 279.38 stays fragile - small-cap carries the beta, mega-cap carries the stabilizer. The regime split is live: SPY/QQQ diverged flags True, and the divergence direction reads Unknown.
Don't lean on index correlation to hedge - it's not available today. Treat each tape independently: IWM wings for the richest premium, SPY for the dealer-flow line at the put wall, QQQ as the capex-narrative stabilizer. Cross-asset confirmation is aligned in the sense that nothing contradicts the setup, but it's not giving you a free hedge.
What it means for your trading
MOVE contained and F&G at Fear say this is equity-local softness, not credit contagion - but with SPY/QQQ regimes diverged (Unknown), hedge each tape on its own book rather than relying on index correlation.
Scenario EV
The scoreboard reads Iron Condor at 42 versus the put spread at 29 - wings win when VIX term runs Contango, VVIX stays Normal, and IWM VRP prints 8.1%. Carry is the trade, not direction.
Sweet spot sits at 30-45 DTE where theta clears gamma without eating event risk. Route size to IWM for the richest harvest per unit of vega; SPY VRP at 1.66% is thin by comparison, and QQQ sits in between. Sizing guidance stays Standard Size while the VVIX/VIX ratio holds contained.
Caveat: dealer vanna at -$83.23B remains destabilizing below the pivot at 768.387384715. Half-clip any naked wing, respect the SPY put wall at 745.00, and fade strength into the call wall at 785.00 - the condor earns the carry, not the pin.
What it means for your trading
Iron Condor at 30-45 DTE on IWM is the harvest; keep naked exposure half-sized while vanna stays destabilizing below 768.387384715.
Actionable Summary
The tape sets up as a Iron Condor regime at 30-45 DTE, with IWM VRP 8.1% the richest harvest in the complex versus SPY 1.66%. SELL wings on IWM where premium pays most per unit of vega; the Elevated / Watchful regime with VVIX at 91.35 supports Standard Size, not reach.
RESPECT the SPY put wall at 745.00 - below it, dealer vanna -$83.23B compounds selling and charm -$557.7K drives close-of-day pressure. The pivot sits at 768.387384715 with bias Destabilizing; AVOID naked long gamma or unhedged puts while flow stays this side of the line. FADE strength into the call wall at 785.00 - do not chase above it.
WATCH VVIX and MOVE at 110.00 for the regime break; a VVIX pop with MOVE confirmation flips the carry trade. Until then, condors route to IWM, SPY stays a tactical fade, and QQQ divergence True means hedge each tape on its own book.
What it means for your trading
Short vol via IWM iron condors at 30-45 DTE is the paid trade; respect SPY put wall 745.00 as the line where dealer flow turns toxic and keep sizing to Standard Size while vanna remains Destabilizing.
BoE flagging its own policy error on Iran shock keeps geopolitical vol-of-vol live even with MOVE contained.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.38 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.39 against a spot of 764.66. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.35% with a volatility risk premium of 1.66%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.33. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime