Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 766.62 with net GEX at -$651.9M - dealers short gamma, moves get amplified until we reclaim the flip. Flip sits at 767.95 (spot 0.1740051784% below), call wall 770.00, put wall 765.00, max pain 760.00 - this is a tight channel where a break either way triggers the amplification loop. Dealer positioning: net VEX -$98.54B (vol-up = sell delta, downside accelerant), net CHEX -$4.7M with charm pushing dealers to sell into close - hostile bias. Vol read: VIX 15.77 in Contango (VIX9D 14.21 → VIX3M 18.09), VVIX 88.71 = low vol-of-vol, VRP 0.89% vs QQQ 1.41% and IWM 5.87% - IWM richest. QQQ sits above its flip 738.95, IWM buried below 291.12: cross-asset regime is diverged. Bottom line: Iron Condor in the 30-45 DTE window, IWM wing bias for VRP capture, half-hedge tail exposure through the flip zone.
SPY negative gamma just under 767.95; contango vol carry; charm destabilizing
SPY at 766.62 trades a hair below the gamma flip at 767.95, keeping dealers short gamma and moves amplified while VIX at 15.77 sits in Contango. Cross-asset regime is diverged with QQQ above its flip and IWM decisively short-gamma, so index-level hedges are dulled and structure selection matters more than direction. Best fit: defined-risk premium capture in the 30-45 DTE window, sized standard given VVIX at 88.71.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
766.62
767.95
-0.17%
770
765
760
-$651.94M
Short gamma
QQQ
741.79
738.95
+0.38%
745
730
725
$2.86B
-
IWM
279.44
291.12
-4.01%
280
275
285
-$4.96B
-
VIX
15.78
16.21
-2.67%
20
15
19
-$22.77M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.92
11.03
+0.89
2.07
2.23
0.81
QQQ
17.43
16.02
+1.41
1.96
1.43
0.82
IWM
18.12
12.25
+5.87
1.16
2.28
2.11
VIX
73.86
98.68
-24.82
-127.91
0.32
0.05
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.77
-1.68%
VVIX
88.71
-1.11%
SPX
7,694.98
+0.31%
SKEW index
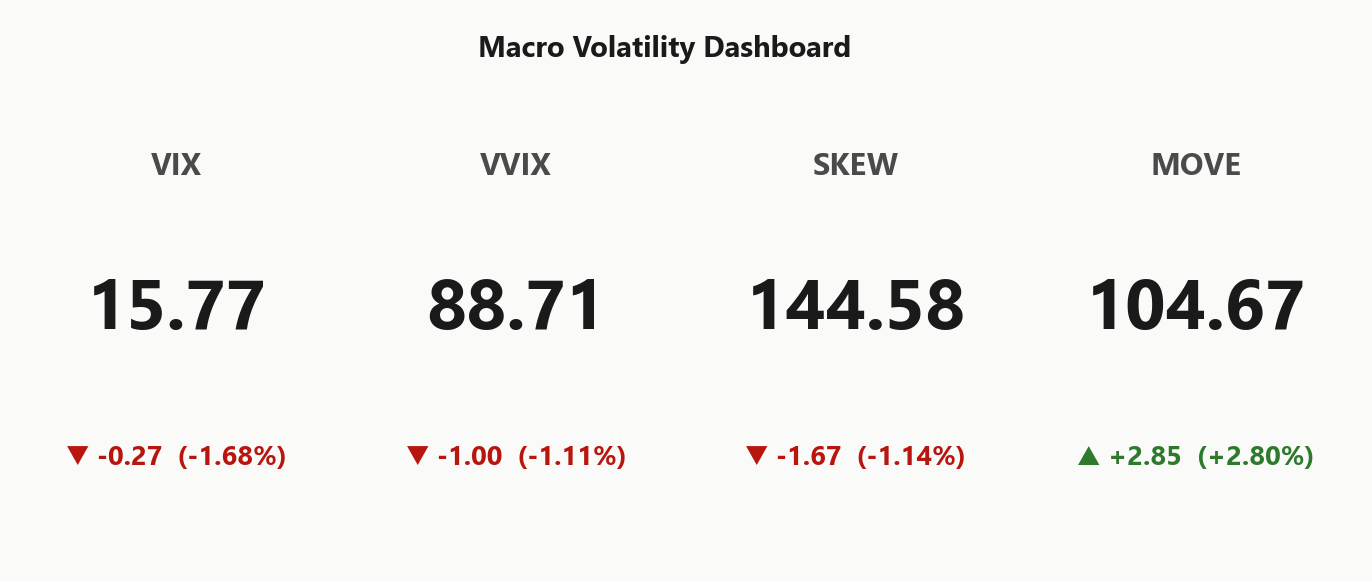
144.58
-1.14%
MOVE (bond vol)
104.67
+2.80%
VIX term (9d/30d/3m/6m)
14.21 / 15.91 / 18.09 / 20.20
Steep contango
VVIX / VIX
5.63
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime prints Elevated - Elevated / Watchful - with VIX anchored at 15.77. The transition matrix reads benign in the near window: probability of escalation to panic over the next five sessions sits at 0.05, while decay back to a low-vol state over ten sessions runs at 0.45. Tails are cheap to insure and the drift is toward compression, not expansion.
Half-life on the elevated read is 15 sessions - sticky enough to trade around rather than fade on a single print. Signal color Yellow keeps books in watchful posture: full expression on defined-risk premium capture, but tail wings stay on because the panic-in-5 optionality is priced too cheaply to skip.
Bias slightly toward being paid to wait - the low-in-10 path is the higher-probability drift, and the Steep Contango vol carry pays vol sellers to sit through the elevated read rather than chase directional convexity.
What it means for your trading
Regime is Elevated / Watchful with a half-life of 15 sessions - elevated but sticky, panic tails cheap to hedge, and drift toward the low-vol state favored over the two-week window.
Trading readMOVE up while VIX is down is the day's tell - bond vol is bidding a story equity vol hasn't discounted. Watch for a VIX rerating higher; that's the divergence trigger.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
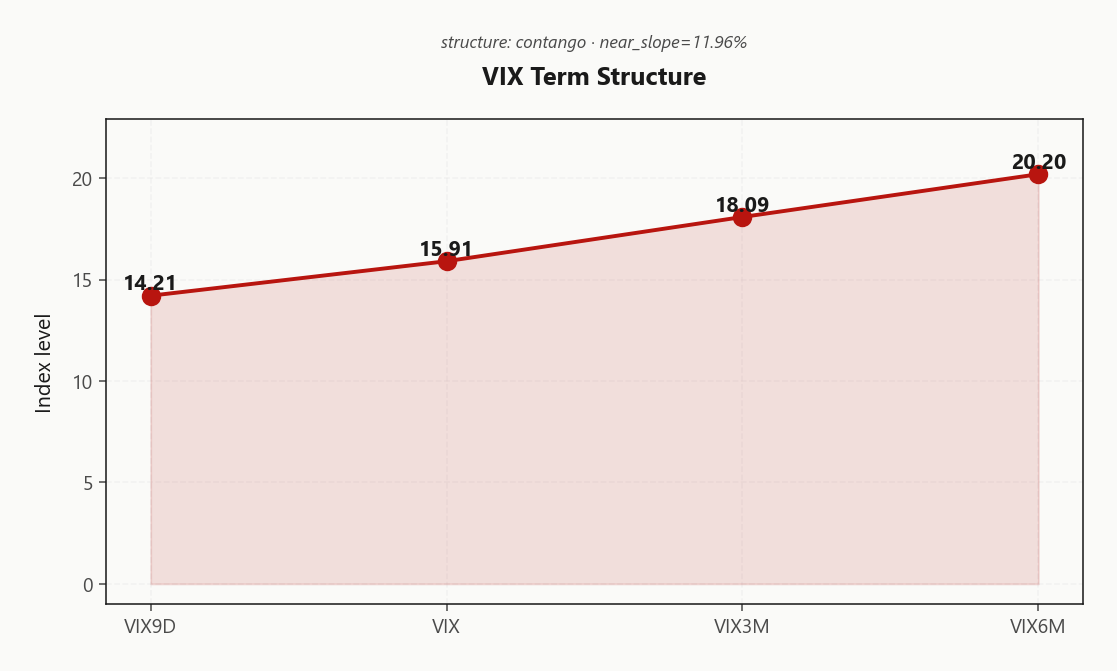
VIX term structure sits in Contango with a positive near-slope of 11.96%, VIX9D at 14.21 pinned under spot VIX at 15.91 - no near-term event is being priced. The curve then rolls orderly through VIX3M 18.09 and VIX6M 20.20, so structural vol carry is available without the panic signature that usually complicates the belly.
The forward 30→60 bucket prints 19.0868567344 against a back-month 60→90 at 22.1095431884 - carry favors selling the front, buying back-month if hedging, and the 30-45 DTE window threads past 0DTE charm risk while staying inside the richest theta-per-unit-risk zone. Regime label reads Steep contango - vol sellers favored.
Bottom line: the forward geometry gives premium sellers a clean runway, but pair it with defined-risk wings - carry is available, not extreme.
What it means for your trading
Forward curve says Steep Contango with the 30-45 DTE window as the sweet spot for theta capture. Sell front vol, keep back-month hedge cheap while the near slope holds.
Trading readContango with a healthy front slope confirms no acute event is priced - vol sellers get paid, but the 30-45 DTE window is the sweet spot to avoid charm land mines.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.92% prints only a hair above HV20 11.03 and HV60 11.17 - index vol is fairly priced, not richly bid. VRP at 0.89% vol points is present but slim, and it doesn't pay the freight for naked short-premium expression at the index.
The dispersion tell is IWM. ATM IV at 18.12% against HV20 12.25 carries a VRP of 5.87% vol points - dramatically richer than SPY's and where systematic vol sellers actually get paid. QQQ's 1.41% sits between the two: respectable, not exceptional.
Preference: harvest through defined-risk IWM structures where realized has undershot implied for weeks, and use SPY as the delta-controlled hedge leg where premium is modest. Route the short wings to the fat tape, keep the index in the middle of the book.
What it means for your trading
IWM VRP at 5.87% versus SPY VRP at 0.89% defines the harvest asymmetry - short wings belong on IWM, SPY is the hedge, QQQ is neutral filler.
Skew Convexity
SPY 2.07% quarter-delta skew with a smile ratio of 1.15% prints an ordered put bid - downside is paid for, but the tape is not paying a crash premium. Put quarter-delta IV at 15.53% against ATM at 14.07% and call quarter-delta at 13.46% traces a wing asymmetry that rewards spread structure over naked long puts on cost basis.
Call side is flat-to-inverted versus ATM, telling us the crowd carries no upside conviction to bid - a signal that call spreads are capped in expected value and long calls trade cheap in absolute dollars but poor in convexity. The put wing steepness is doing all the work; smile above one confirms the geometry without tipping into the reflexive bid that shows up ahead of a real event.
Preferred expression: put spreads over naked puts to neutralize the paid-up wing, sell call wings into the flat side to capture VRP where the crowd underprices it, and pair with near-money calls for cheap upside optionality - the flat call skew is where dollar-cheap convexity actually lives.
What it means for your trading
Skew at 2.07% with smile ratio 1.15% is elevated but ordered - put spreads dominate naked puts, and the flat call side offers the session's cheapest upside optionality.
Vol-of-Vol Structure
VVIX prints 88.71 against a VIX of 15.77, putting the VVIX/VIX ratio at 5.63 and the vol-of-vol regime firmly in the Low bucket. No bimodal outcome is priced into the vol surface, so sizing guidance holds at Standard Size - full expression is permitted on defined-risk premium trades rather than the defensive half-clip that a stress-tier VVIX would demand.
The read matters because it green-lights the recommended Iron Condor in the 30-45 DTE window at standard clip. With vol-of-vol asleep, wings behave and the theta-per-unit-risk stays intact even with charm hostile at the pivot. The caveat: this framework is contingent, not permanent - a VVIX rerating through the triple-digit line flips convexity math instantly and forces a size cut mid-book.
Track intraday. A VVIX bid alongside the 104.67 MOVE strength would be the earliest tell that cross-asset vol contagion is arriving before spot equity vol reprices.
What it means for your trading
Vol-of-vol reads Low at VVIX 88.71 - sizing stays Standard Size on defined-risk structures, but a rerating through triple digits flips the framework and requires an immediate clip reduction.
Dispersion Spread
SPY ATM IV at 11.92% sits well under QQQ at 17.43% and IWM at 18.12% - index vol is compressed versus single-name, with cross-expiry dispersion at 2.65. The correlation embedded in that spread isn't high enough to make SPY the efficient hedge for a single-name book; the index simply isn't paying for the fragility carried in the constituents.
The tape's real driver is mega-cap gamma concentration - NVDA, MSFT and META top the GEX movers and are structurally steering the index through the dispersion channel. Dispersion-aware books express this classically short SPX vol / long single-name vol; at the retail scale the mirror is a SPY put credit spread funding a single-name long-vol leg where realized has room to catch up.
Wing bias belongs on the small-cap side: IWM VRP is the fattest premium in the complex and its ATM IV at 18.12% is where systematic sellers get paid cleanest. Route short wings into IWM, keep SPY as the delta-controlled expression, and let the mega-cap gamma stack do the index work.
What it means for your trading
Index vol at 11.92% is a poor hedge for single-name risk while IWM at 18.12% carries the richest wing premium - short SPX vol against single-name long-vol, bias wings to IWM.
Liquidity & Microstructure
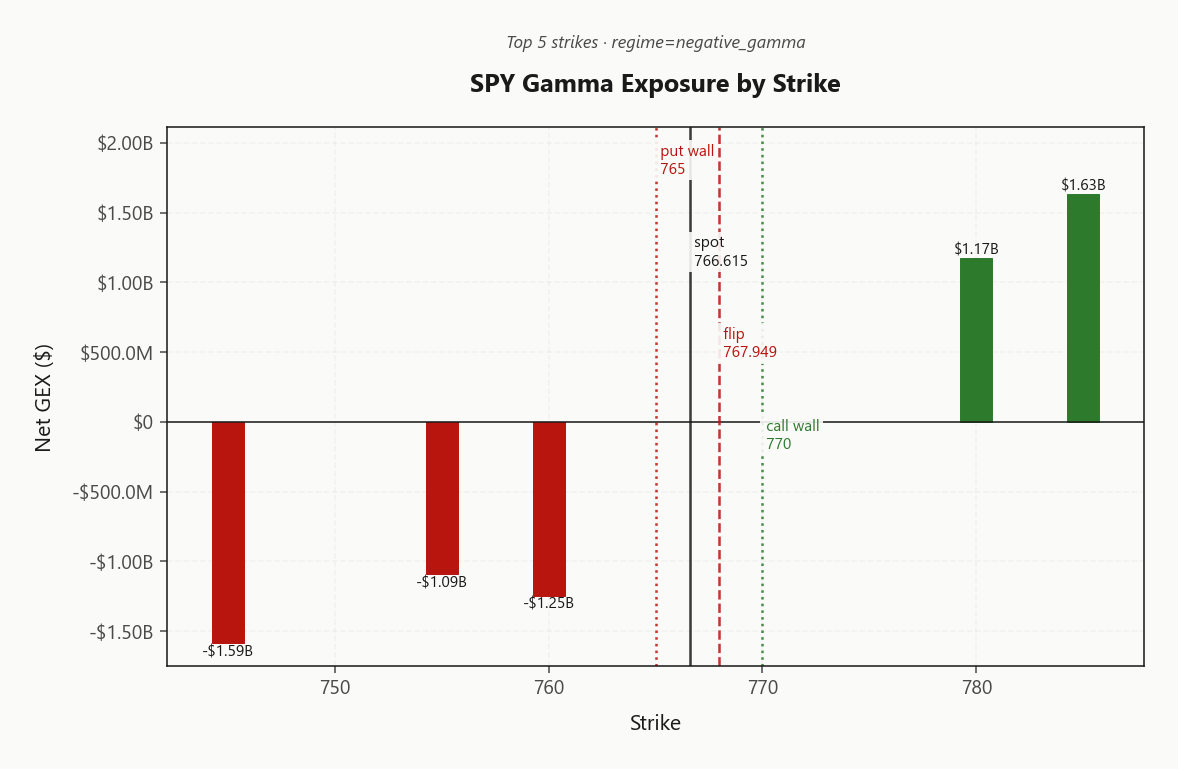
The book anchors at 700 for open interest, but the working pivot is the gamma flip at 767.95. Spot at 766.62 sits fractionally below, keeping dealer flow in amplification mode until reclaimed. Above, the 770.00 call wall caps any push; below, 765.00 is the first tape support of consequence.
Top strike 785.00 carries net GEX of $1.63B - the ceiling magnet if a run develops, and the reason rallies compress rather than extend. Max pain at 760.00 sits under spot, adding natural gravity into expiration and reinforcing the mean-revert bias inside the wall channel.
The single decision level is a reclaim of 767.95: above, dealer flow flips supportive and the amplification loop breaks; below, every slide sells into the 765.00 bounce zone. Trade the channel, not the breakout, until that pivot resolves.
What it means for your trading
Spot pinned below the flip at 767.95 inside a 765.00 - 770.00 channel - amplification stays on until reclaim, with max pain at 760.00 pulling into expiration.
Trading readDeep negative gamma below the flip zone means every push lower gets amplified while every rally into 770.00 gets dampened - trade the channel, not the breakout, until spot reclaims 767.95.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Charm compounds it. Time decay pushing dealers to sell - pressure into close, meaning the closer we run to expiry, the heavier the mechanical offer gets. The charm pivot sits at 767.9489497985, essentially on spot - bias reads Destabilizing at signal Red. A break below extends the sell-delta loop; a reclaim flips dealers back to supportive and the whole flow map inverts.
Trade implication: avoid naked short vol here. Cap the tail with defined-risk structures through the pivot zone until the sign of gamma turns.
What it means for your trading
With net VEX -$98.54B, net CHEX -$4.7M and the charm pivot at 767.9489497985 reading Destabilizing, dealer flow amplifies moves until spot reclaims the pivot. Keep risk defined.
Cross-Asset Confirmation
The dissonant tell today is MOVE at 104.67 printing up 2.8%% while VIX at 15.77 softens in Contango - bond vol is bid, equity vol is not. That footprint reads credit- and rates-led, not equity-led. Watch for spillover: a VIX rerate would rewrite the entire book, and MOVE strength is the leading edge.
Fear & Greed at Fear with score 29 confirms defensive positioning without panic - bounce fuel, not squeeze fuel. Beneath the index, the regime is Unknown: QQQ at 741.79 trades above its flip and carries the tape via mega-cap gamma stability, while IWM at 279.44 sits buried below its flip in short gamma - the fragility trade of the session.
Trade implication: index-level hedges misprice the asymmetric fragility concentrated in small caps. Bias short wings to IWM where VRP is fattest, keep SPY as the delta-controlled expression, and treat MOVE strength as the tripwire for repricing.
What it means for your trading
Regime is diverged, not synchronized: QQQ carries the leadership above its flip, IWM buried below is the fragility leg - and MOVE strength while VIX softens is the cross-asset warning worth respecting.
Scenario EV
Structure selection resolves cleanly: Iron Condor scores 40 against a put spread at 27 - VRP is thick enough to monetize both wings rather than one-sided directional premium. The 30-45 DTE window is the operative expression: past the 0DTE charm minefield with spot sitting 0.1740051784% off the flip, and inside the forward 19.0868567344 vol bucket where the curve pays sellers without an event embedded.
Sizing stays Standard Size. VVIX at 88.71 reads Low - no bimodal tail is priced, so full defined-risk expression is on the table. Bias the short wings to IWM where VRP prints 5.87% versus SPY at 0.89%; that's where the harvest actually pays. Use SPY as the delta-controlled leg and keep the tape hostage to the charm pivot at 767.9489497985 as the intraday entry filter.
What it means for your trading
Iron condor in the 30-45 DTE window with short wings biased to IWM - VRP fattest there, VVIX at 88.71 keeps sizing standard.
Actionable Summary
Trade plan:Iron Condor in the 30-45 DTE window, short wings biased to IWM where VRP prints 5.87% - the richest in the complex. SPY put spreads dominate naked puts with quarter-delta skew at 2.07% ordered, not panicked. Charm pivot at 767.9489497985 is the entry decision level - spot sits 0.1740051784% below with dealer positioning hostile through the flip zone.
Avoid naked short strangles while charm is destabilizing; defined-risk only. Watch a SPY reclaim of 767.95 to flip intraday flow bias, and MOVE at 104.67 for spillover into VIX - that repricing rewrites the framework. Regime label Elevated / Watchful keeps the stance forward-lean, not defensive.
Size Standard Size - VVIX at 88.71 sits low enough that no half-size discipline applies. Full expression on defined-risk premium capture; harvest the IWM wing, delta-control through SPY.
What it means for your trading
The clean expression is an IWM-wing iron condor in the 30-45 DTE window, entered on a charm-pivot reclaim of 767.9489497985 and sized Standard Size. Skip naked short vol while spot trades 0.1740051784% below the flip with hostile charm.
Cooler PCE and Micron tonight - a soft-inflation confirmation plus a semiconductor bellwether landing after the bell explains why VIX9D at 14.21 isn't repricing yet.
Trump uncertainty language on Iran keeps geopolitical optionality live - precisely the kind of headline that makes selling naked tail wings expensive to insure.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.78 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.95 against a spot of 766.62. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.92% with a volatility risk premium of 0.89%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.77. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime