Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 768.14 with net GEX $2.94B - dealers long gamma, moves dampened intraday. Call wall pins price at 770.00, put wall support at 765.00, max pain sits at 760.00 - spot is within a two-dollar band of the pivot at 770, near-neutral bias. Dealer vanna at -$108.4B is negative - a vol spike would flip them short delta and accelerate downside; charm at -$7.3M is small and non-committal into the close. VIX at 15.87 with VIX9D 13.69 < spot VIX < VIX3M 18.06 - steep contango, no event priced short-dated, structural carry favors vol sellers. VRP 0.65% on SPY is modestly positive, IWM VRP 5.57% is materially richer - small-cap is where premium sales pay the most. QQQ regime Positive Gamma above flip 738.97 - mega-cap cushion intact; IWM regime Unknown with spot below 292.38 - fragile leg. Bottom line: sell IWM 30-45 DTE defined-risk premium, fade SPY strength into 770.00, respect 765.00 as the tripwire.
Steep VIX contango, positive-gamma QQQ, IWM neg-gex - mean-reversion in mega-caps, fragility in small-caps
SPY at 768.14 sits pinned between call wall 770.00 and put wall 765.00 with dealers net long gamma, while QQQ trades comfortably above its flip at 738.97 - a mean-reversion tape for mega-caps. IWM breaks the pattern: net GEX -$5.32B and spot below its flip mark small-caps as the fragile leg. VIX term structure in Contango with VIX9D at 13.69 keeps vol sellers paid on index while IWM's rich VRP 5.57% rewards defined-risk premium sales.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
768.14
-
-
770
765
760
$2.94B
-
QQQ
743.82
738.97
+0.66%
745
730
725
$5.87B
Long gamma
IWM
279.61
292.38
-4.37%
280
275
285
-$5.32B
-
VIX
15.87
16.13
-1.63%
20
15
19
-$21.95M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.59
10.94
+0.65
1.81
2.23
0.98
QQQ
17.01
15.29
+1.72
1.71
1.43
1.15
IWM
17.46
11.89
+5.57
1.48
2.28
1.09
VIX
76.96
98.66
-21.70
-127.91
0.32
0.64
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
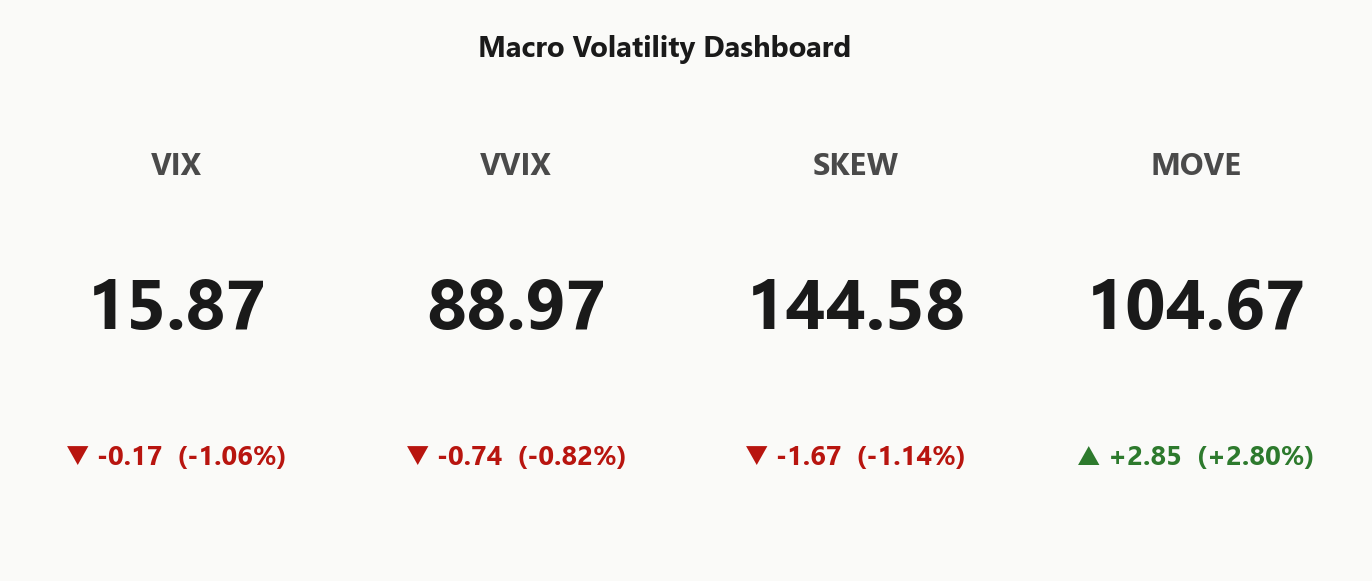
VIX
15.87
-1.06%
VVIX
88.97
-0.82%
SPX
7,711.55
+0.53%
SKEW index
144.58
-1.14%
MOVE (bond vol)
104.67
+2.80%
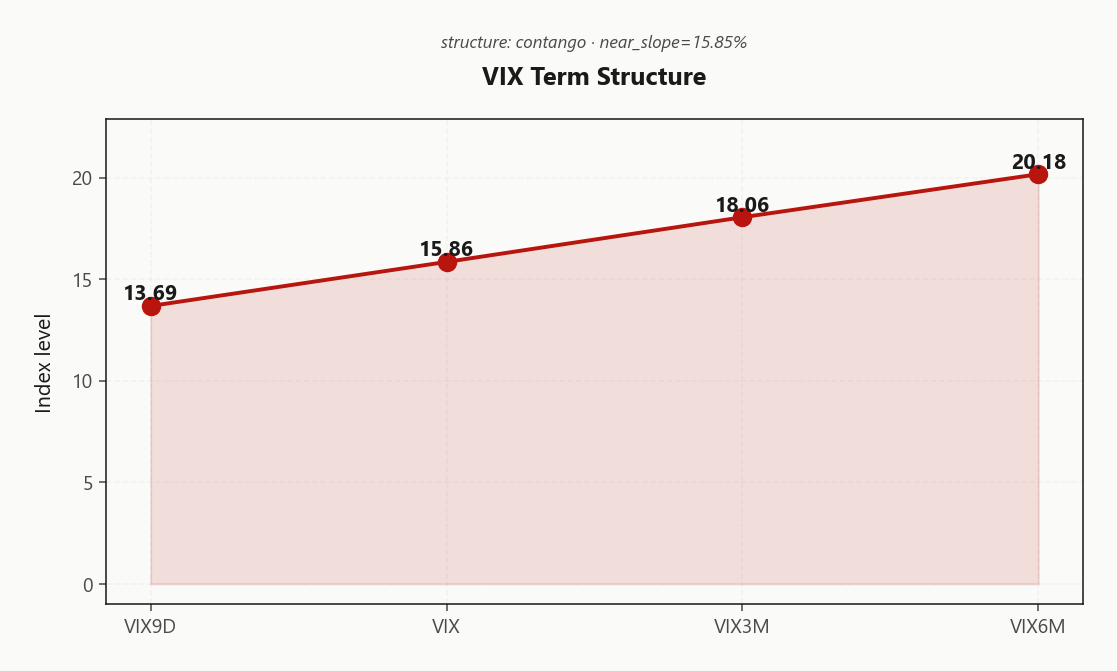
VIX term (9d/30d/3m/6m)
13.69 / 15.86 / 18.06 / 20.18
Steep contango
VVIX / VIX
5.61
Low
Regime
Elevated / Watchful
Regime Assessment
The volatility regime reads Elevated / Watchful with VIX at 15.87 - call it watchful, not defensive. Transition probability into panic over five sessions sits at 0.05, effectively no acute stress signal in the tape. The far more likely path is compression: probability of migrating into the low-vol regime over ten sessions runs 0.45, nearly an order of magnitude higher than the panic tail.
Regime half-life prints 15 sessions - the state is sticky. That stickiness is the underwriting case for patient premium selling: the regime does not flip on a single tick, and mean-reversion inside the range is the dominant intraday behavior while dealers stay long gamma in SPY and QQQ sits above its flip at 738.97.
Trade the tape the regime prescribes: defined-risk short vol routed where VRP is richest - 5.57% on IWM against 0.65% on the index - with VVIX/VIX at 5.61 keeping sizing at standard. The tripwire remains the SPY put wall at 765.00; a breach re-rates the whole probability tree.
What it means for your trading
Regime Elevated / Watchful with half-life 15 sessions and compression probability 0.45 well above panic probability 0.05 - patient defined-risk premium sales are the trade, small-cap the venue.
Trading readMOVE 104.67 pushing higher while VIX drifts lower - the divergence often precedes an equity-vol wake-up. SKEW at 144.58 sits mid-range, not warning yet.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure prints textbook Contango: VIX9D at 13.69 sits under spot VIX 15.86, which sits under VIX3M 18.06 and VIX6M 20.18. The front pinned below the belly tells you the tape is not pricing a near-term event - this is structural carry, not a countdown to a print.
Forward 30→60 solves to 19.0650360608 against forward 60→90 at 22.0975383244. Both buckets carry positive, and the curve steepens into the belly rather than flattening - the roll-down pays without asking the seller to warehouse expiry gamma. Regime read: Steep Contango, signal green for patient vol sellers.
Operational takeaway: 30-45 DTE is the sweet spot. Short enough to capture the steepest slope of the forward curve, long enough to stay clear of the front-week gamma bleed. Calendars long the belly against a short front, or defined-risk premium sales in that window, are the shape the term structure is paying for today.
What it means for your trading
VIX term in Contango with forward 30→60 at 19.0650360608 below forward 60→90 at 22.0975383244 - structural carry, no event premium, 30-45 DTE captures the roll without expiry gamma risk.
Trading readSteep contango top-to-bottom - vol carry trade is intact and structural, not fragile. Short vol at the belly, roll month over month, no near-term event premium to fade.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV 11.59% against HV20 10.94 and HV60 11.18 prints a VRP of 0.65% - thin, and consistent with index premium already trading efficient. There is edge in the complex, but it does not sit in SPY.
IWM is the routing target. ATM IV 17.46% versus HV20 11.89 produces VRP 5.57% - options materially rich to the realized tape and the fattest carry per dollar of defined-risk premium sold. QQQ VRP 1.72% is elevated as well, but HV60 18.92 reflects prior heat that current tape has cooled - the setup is less clean than IWM.
IV-RV spread reads Thin Premium. Route defined-risk short vol to IWM at 30-45 DTE, keep SPY sales opportunistic into strength, and avoid naked single-name shorts absent a dispersion basket.
What it means for your trading
SPY VRP 0.65% is thin; IWM VRP 5.57% is the richest in the complex - that is where premium sales pay.
Skew Convexity
SPY quarter-delta skew sits at 1.81% with a smile ratio of 1.14% - put wing IV 14.91% against call wing 13.1%. That's ordered put steepening: insurance is bid, but the wing isn't pricing a left-tail event.
The call side tells the other half of the story. Call-wing IV prints below ATM 13.69% - no upside conviction is being paid for. With the put wing carrying a meaningful premium over the call wing, put spreads dominate naked puts on a delta-adjusted basis; selling the far wing back finances the near strike at a discount the flat call side won't offer.
Cross-asset, IWM quarter-delta skew at 1.48% sits flatter than SPY - small-cap fear is diffused across the surface rather than concentrated in the wings. That routes tail-hedging demand to the index and premium-selling structures to IWM, where the shape doesn't overpay for the crash strike.
What it means for your trading
Skew shape is steep but orderly with a suppressed call wing - favor SPY put spreads over naked puts, and route defined-risk premium sales to IWM where the flatter skew 1.48% keeps wing pricing honest.
Vol-of-Vol Structure
VVIX prints 88.97 against spot VIX 15.87, putting the ratio at 5.61 - squarely inside the normal band and reading Low on the vol-of-vol scale. There is no bimodal jump premium embedded in the front - the tape is not paying up for either a vol crush or a vol spike, so the distribution of the next VIX print is unimodal and mean-reverting.
Sizing follows: Standard Size is the operative rule - full standard risk on premium sales, no half-sizing tax. That matters most where VRP is richest, and IWM at 5.57% vs SPY at 0.65% is where the sizing budget deploys most efficiently. Vol-of-vol is not the constraint today; VRP asymmetry is the routing signal.
Trigger for a posture change is mechanical - a VVIX pop through the hundred handle flips the sizing rule and the assumption of unimodal vol. Until then, the Low read on vol-of-vol is a green light on standard-size, defined-risk short vol.
What it means for your trading
Vol-of-vol at Low with VVIX/VIX ratio 5.61 - full standard sizing on premium sales, no bimodal jump risk priced. Watch a VVIX break above triple-digits as the first sign to cut.
Dispersion Spread
Index vol is compressed while single-name proxies sit meaningfully richer - SPY ATM IV at 11.59% against QQQ at 17.01% and IWM at 17.46%. That spread is the dispersion signature: correlation is soft, so the index averages out what the constituents are actually paying in vol. IV-dispersion measure {"cross Expiry":2.8,"cross Strike":88.11} confirms the cross-strike and cross-expiry spread is live, not a print artifact.
The structural read: index premium sales are the efficient short-vol expression here, not single-name. Selling naked single-name vol into this tape leaves you short the dispersion leg without the basket - you collect compressed correlation premium and eat the realized single-name variance when it prints. SPY and SPX vol sales route around that trap by construction.
Discipline point: if the trade thesis genuinely needs single-name short vol, pair it against a dispersion basket rather than running it naked. QQQ at 17.01% and IWM at 17.46% versus SPY at 11.59% is the map - trade the spread, not the leg.
What it means for your trading
Index IV at 11.59% sits below QQQ 17.01% and IWM 17.46% with dispersion {"cross Expiry":2.8,"cross Strike":88.11} confirming soft correlation - route short-vol through SPY/SPX, and never short single-name vol without a dispersion basket to hedge the correlation leg.
Liquidity & Microstructure
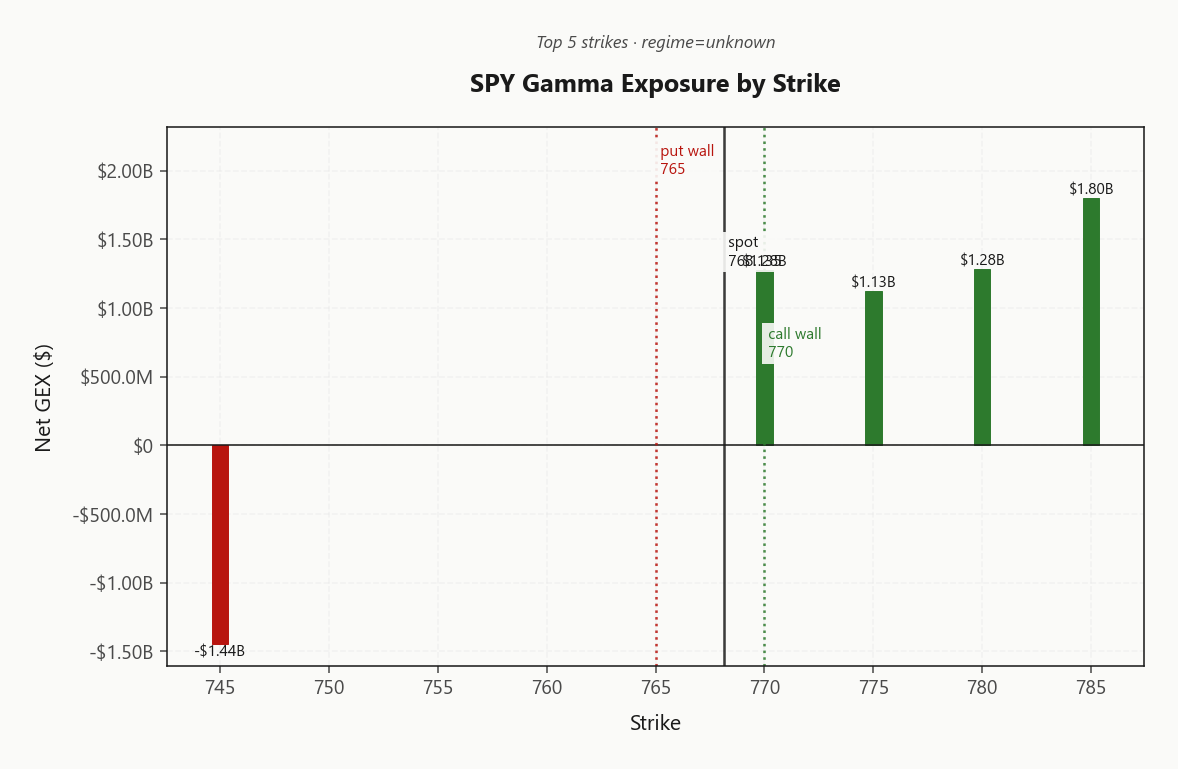
SPY's book anchors on the 700 highest-OI magnet, with the dominant positive-gamma cluster stacked at 785.00 contributing $1.8B. That block anchors dealer buying on dips and pulls intraday drift back toward the magnet through weekly expiry.
The call wall at 770.00 is the operative fade zone; the put wall at 765.00 is the tripwire whose breach flips the regime. Gamma flip status Stored Sign Mismatch means the flip level is not clean - treat the wall structure, not the flip, as the pivot that matters. Inside the range, dealer hedging dampens; outside the put wall, it inverts.
IWM is the mirror: net GEX -$5.32B below its flip at 292.38 means dealer flow amplifies moves rather than dampens them. Same complex, opposite microstructure - mega-caps cushioned, small-caps fragile.
What it means for your trading
Trade the SPY wall structure, not the flip: fade into 770.00, respect 765.00 as the regime tripwire, with the 785.00 cluster as the intraday magnet. IWM's negative-gamma regime routes defined-risk premium sales there - dealer amplification below its flip makes naked exposure the wrong side.
Trading readPositive-gamma cluster stacks between put wall 765.00 and call wall 770.00 - dealers dampen inside the range, so intraday moves fade to the highest-OI magnet at 700. Below put wall, the sign flips and dealer flow amplifies.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX prints -$108.4B - dealers are short vanna, and a vol pop is the accelerant risk. The book dampens spot inside the wall structure, but a spike in 15.87 flips hedgers short delta and turns today's cushion into tomorrow's amplifier. This is the hidden convexity underneath a positive-gamma tape: benign until it isn't.
Charm sits at -$7.3M - small enough to ignore. No forced into-close hedging pressure, no time-decay tailwind for either side. The pivot at 770 (Call Wall) sits 0.2427958627 from spot, with dealer bias Neutral - no directional lean baked in.
Trade the structure, not the sign. Dampening holds while 88.97 stays contained; a VVIX pop is the tell that vanna is about to become the story. Respect 765.00 as the tripwire - a breach with vol expanding is when negative vanna does its damage.
What it means for your trading
Positive gamma dampens today, but negative vanna at -$108.4B is the accelerant if 15.87 spikes. Charm neutral, bias Neutral - the pivot at 770 defines the flip zone.
Cross-Asset Confirmation
Rates vol is the tell today. MOVE at 104.67 is drifting higher with change 2.8% while equity vol compresses under a steep VIX contango - bond vol is doing the work that equity vol isn't, and that asymmetry usually resolves through equities, not the other way. Fear & Greed reads Fear at score 35, which sits at odds with a benign tape - that mismatch is fuel for mean-reversion, not continuation.
The lead story is the intra-index split. QQQ at 743.82 holds above its flip and prints regime Positive Gamma, while IWM at 279.61 trades below its flip - divergence flag True. This is not a broad credit-shock signature; it's targeted small-cap fragility with the mega-cap complex still cushioned.
Route accordingly: sell premium where the fragility is priced, not where the tape is calm.
What it means for your trading
Rates-vol lifting into an equity-vol compression with F&G at Fear flags a mean-reversion setup, not a trend break. The QQQ-above-flip / IWM-below-flip split (True) localises the fragility to small-caps - trade the divergence, don't hedge the index.
Scenario EV
Scenario EV output flags Unknown as the routing signal with the optimal window at 21-30 DTE and VRP assessment Unknown. The complex-wide edge sits in small-caps: IWM VRP at 5.57% dwarfs SPY VRP at 0.65%, and defined-risk premium sales route there for the richest carry per dollar of risk.
Iron condors sized to the 21-30 DTE window capture the steepest roll-down without inheriting expiry gamma. SPY premium is efficient and thin - index short-vol is a carry trade, not an edge trade. IWM is where the payoff geometry earns its keep, and the vol-of-vol backdrop at Low supports full standard sizing rather than a defensive half-clip.
Standard size stands until VVIX/VIX ratio breaks its band or MOVE keeps drifting higher - either signal flips the sizing rule to reduced before the structure itself gets repriced.
What it means for your trading
Route defined-risk premium sales to IWM in the 21-30 DTE window where VRP prints 5.57% versus SPY's 0.65%. Vol-of-vol Low keeps sizing at standard, not reduced.
Actionable Summary
Bottom line: recommended structure Unknown anchored at pivot 770 with regime Elevated / Watchful. Route defined-risk premium sales to IWM where VRP prints 5.57% - the richest carry in the complex - and fade any SPY strength into the 770.00 call wall.
The 765.00 put wall is the tripwire: a clean breach flips the mean-reversion tape into an accelerant regime as negative vanna kicks in. Avoid naked single-name short vol without a dispersion basket - index IV is compressed but single-name IV is not, and the correlation cushion is thin.
Watch:88.97 pushing through the vol-of-vol warning zone, and a continued grind higher in 104.67 as the macro tell that rates vol is leaking into equities.
What it means for your trading
Sell IWM premium at 5.57% VRP, fade SPY into 770.00, and treat 765.00 as the line that flips the regime.
Cooler PCE combined with tonight's Micron print is the near-term catalyst pair - semis are the QQQ engine and a Micron surprise re-rates single-name vol.
Iran diplomatic thread developing quietly - not moving markets today but a change in tone would spike MOVE first and VIX second.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.87 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $2.94B. The gamma flip sits at N/A, with the call wall at 770.00 and the put wall at 765.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 768.14. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.59% with a volatility risk premium of 0.65%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.87. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime