Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closes at 763.42 in Negative Gamma with net GEX -$6.59B - spot sits below the 768.38 flip, so dealers amplify moves rather than dampen them. Call wall 785.00 caps upside; put wall 745.00 defines the trapdoor; max pain 760.00 is the magnet into monthly expiry. Dealer vanna -$69.91B and charm -$317.5K lean destabilizing - a vol pop translates to more selling, and time decay pulls dealers offer into close. VIX 16.42 with term structure Contango (VIX9D 13.98 → VIX3M 18.24) says carry favors vol sellers; VVIX 89.77 keeps vol-of-vol muted so standard size is appropriate. IWM VRP 6.96% dwarfs SPY 1.66% and QQQ 2.79% - that's where premium sales pay the most per unit risk. Bottom line: Iron Condor at 30-45 DTE, route to IWM for the fattest VRP, respect 760 as the pivot that flips dealer flow direction.
SPY Negative Gamma vs QQQ pos-gamma cushion; IWM fragile with rich VRP 6.96%
Close wrap prints SPY in Negative Gamma with spot beneath 768.38 while QQQ retains positive-gamma cushion and IWM stays fragile against a rich 6.96% vol premium. VIX term structure Contango with VVIX 89.77 keeps vol-of-vol quiet, favoring premium sellers. Iron condor 30-45 DTE is the highest-scoring structure, best sized around the 760 pivot.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
763.42
768.38
-0.65%
785
745
760
-$6.59B
Short gamma
QQQ
740.61
-
-
760
730
725
$2.05B
-
IWM
277.96
291.89
-4.77%
290
275
285
-$4.67B
Short gamma
VIX
16.32
16.67
-2.09%
20
16
19
-$32.41M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.44
10.78
+1.66
1.25
2.23
1.02
QQQ
17.90
15.11
+2.79
2.64
1.43
1.18
IWM
18.77
11.81
+6.96
1.37
2.28
1.22
VIX
72.39
98.62
-26.23
-116.62
0.32
0.64
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
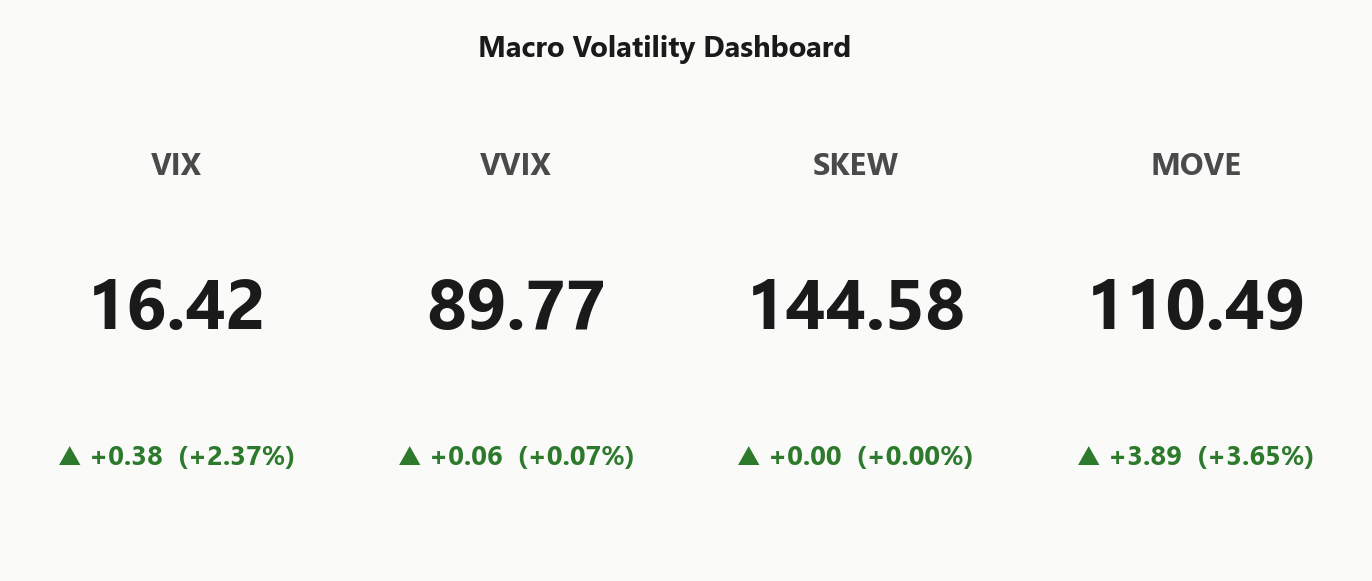
16.42
+2.37%
VVIX
89.77
+0.07%
SPX
7,651.54
-0.25%
SKEW index
144.58
0.00%
MOVE (bond vol)
110.49
+3.65%
VIX term (9d/30d/3m/6m)
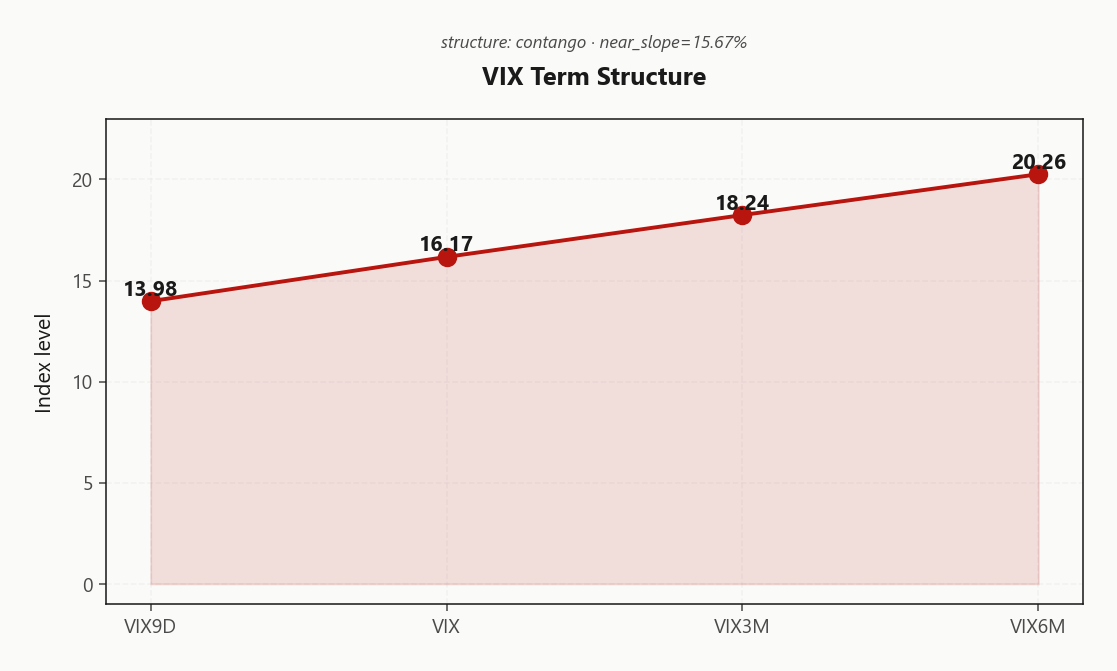
13.98 / 16.17 / 18.24 / 20.26
Steep contango
VVIX / VIX
5.47
Low
Regime
Elevated / Watchful
Regime Assessment
The tape sits in a Elevated / Watchful regime with VIX at 16.42 - not calm enough to size aggressively, not stressed enough to hedge for a break. The Elevated classification is a middle-of-the-map read that respects the Contango carry while acknowledging the negative-gamma amplification below 768.38.
Transition probabilities frame the asymmetry cleanly: panic-in-five-sessions sits at 0.05 against a revert-to-low-in-ten of 0.45. The tail is quiet; the base case is normalization, not escalation. VVIX at 89.77 corroborates - no bimodal pricing, no jump premium, sizing stays Standard Size.
Regime half-life prints at 15 sessions - persistent enough to trade, not so sticky that structures need to survive a quarter. That window is the horizon for the Iron Condor at 30-45 DTE: the regime outlasts the trade, not the other way around.
What it means for your trading
Regime Elevated / Watchful at VIX 16.42 favors premium sellers with a 15-session horizon - normalize is the base case, panic is the tail, and Standard Size clears standard book.
Trading readVIX and VVIX are both muted but MOVE is quietly bidding and SKEW sits elevated - that combination is the quiet-before-repricing setup, not confirmation of calm; tail hedges stay warranted even as premium sales work.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
VIX term structure holds Contango with near-slope 15.67% - no event premium priced across the front. The stack runs clean upward: VIX9D 13.98 under spot 16.17, VIX3M 18.24 above, VIX6M 20.26 capping the curve. No kink, no event pricing - the carry trade is unopposed.
Forward vol geometry says the pickup lives in the belly. Forward 19.1914551298 on the 30→60 bucket beats the 60→90 forward at 22.0960992033 for realized-adjusted carry per unit gamma exposure, marking 30-45 DTE as the sweet spot where front vol is too cheap to sell and back vol too slow to earn.
Regime label prints Steep Contango - Steep contango - vol sellers favored. Vol sellers get paid, the belly is where the money is, and there is nothing in the term structure suggesting the market is bracing for a discrete event.
What it means for your trading
Term structure Contango with the 30→60 forward at 19.1914551298 defines 30-45 DTE as the highest-carry window for premium sales. Regime Steep Contango keeps vol sellers unopposed until a front-end kink appears.
Trading readContango with clean upward slope from VIX9D through VIX6M says the market is not pricing an event - the carry trade is live and unopposed, which is exactly when vol sellers get paid.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 12.44% against HV20 10.78 prints a modest but live VRP of 1.66% - options are paid over realized, not richly, but enough to matter when carry lines up with the rest of the book. HV60 11.13 against HV20 10.78 shows realized decelerating, which is exactly the tape short-vol wants underneath it - the base drifts lower while implieds hold their bid.
Cross-asset, the premium isn't evenly distributed. IWM VRP 6.96% dwarfs SPY's 1.66% and QQQ's 2.79% - small-cap sellers get paid multiples per unit risk versus the index, while QQQ sits in the middle with mega-cap options fairly priced rather than a giveaway. Section signal reads Vrp Active.
Route the premium sale where the carry is fattest: IWM is the compensated seat, SPY the marginal one, QQQ the pass. Decelerating realized on the index removes the main tail-risk to short structures.
What it means for your trading
VRP is live but concentrated - SPY at 1.66% is the marginal seller's edge, IWM at 6.96% is where premium sales actually pay. Decelerating HV20 10.78 versus HV60 11.13 supports the short-vol thesis into the next cycle.
Skew Convexity
SPY quarter-delta skew prints 1.25% with the smile ratio at 1.09% - the put wing is bid, but this is ordered protection demand, not the tail-of-tail chase that shows up before dislocation. Put quarter-delta IV 14.83% sits above ATM 14.45% by a measured margin, consistent with book-level hedging against a Negative Gamma tape rather than convex tail buying.
Call quarter-delta IV 13.58% trades under ATM - no upside conviction bid, no chase into the 785.00 wall. That's the tell: sellers of upside vol are still in control while put buyers accumulate deliberately, giving a balanced convexity profile rather than the bimodal pricing that would force a size-down.
Section reads Skew Steep - steep enough to make put-spread sellers get paid, flat enough on the call side that iron condors clear both wings without giving up the range. Route wing sales into IWM where VRP 6.96% compounds the skew edge; SPY structures respect the 760 pivot.
What it means for your trading
Skew is steep but ordered - put wing paying above ATM at 1.25% without a smile blowout - so put-spread sellers get compensated without the convexity risk that would show up in a bimodal regime. Call side flat under ATM means iron condor wings clear on both sides at 30-45 DTE.
Vol-of-Vol Structure
VVIX 89.77 against VIX 16.42 prints a ratio of 5.47 - squarely in the Low regime. The vol-of-vol tape is not pricing a bimodal outcome: no jump premium in the wings, no crush setup in the body. Options on options are cheap in absolute terms and boring in relative terms, which is the quiet green light short-vol books wait for.
The ratio sits in the comfort zone where neither a VIX crush nor a VVIX spike carries an obvious edge - that removes the two-way convexity bet that usually caps sizing in the front book. With signal Green and level Low, dealer-hedging feedback into a vol pop stays orderly rather than reflexive, so the destabilizing vanna on SPY does not get compounded by vol-of-vol convexity buyers chasing the tape.
Sizing guidance therefore reads Standard Size - full book allowed. Route the Iron Condor at 30-45 DTE at working size; the vol-of-vol tape is not the constraint today.
What it means for your trading
VVIX/VIX at 5.47 keeps the regime Low with sizing Standard Size - vol-of-vol is not the binding constraint, so put risk on at spec size where VRP pays.
Dispersion Spread
Index dispersion is where the tape pays today. IWM ATM IV at 18.77% runs materially rich against SPY 12.44%, with QQQ threading the middle at 17.9%. That gap is small-cap idiosyncratic risk asking to be sold, not an index correlation break - mega-cap cross-name correlation stays anchored while single-name dispersion inside the Russell keeps its wing bid.
Section reads Moderate: cross-name correlation is holding, so single-name premium sales lack the correlated tailwind that makes them worth the gap risk. The index vol premium, by contrast, is compensated cleanly by Contango carry and muted VVIX at 89.77 - the sell side of the book gets paid without a jump-risk tax.
Route the trade to index wings, not single names. IWM iron condor captures the richest ATM IV on the board; QQQ and SPY offer thinner but structurally cleaner fills. Selling individual dispersion into Moderate correlation is the classic trap - you collect thin premium and wear the fat tail.
What it means for your trading
IWM ATM IV 18.77% tops the trio versus QQQ 17.9% and SPY 12.44% with cross-name correlation at Moderate - sell the index wings, not the constituents.
Liquidity & Microstructure
SPY's book anchors at 700 - deep long-dated protection, not day-trade fuel - while spot sits below the gamma flip at 768.38. That geometry puts every tick in the amplification zone: dealers sell weakness and buy strength, so intraday flow leans one-way rather than mean-reverting.
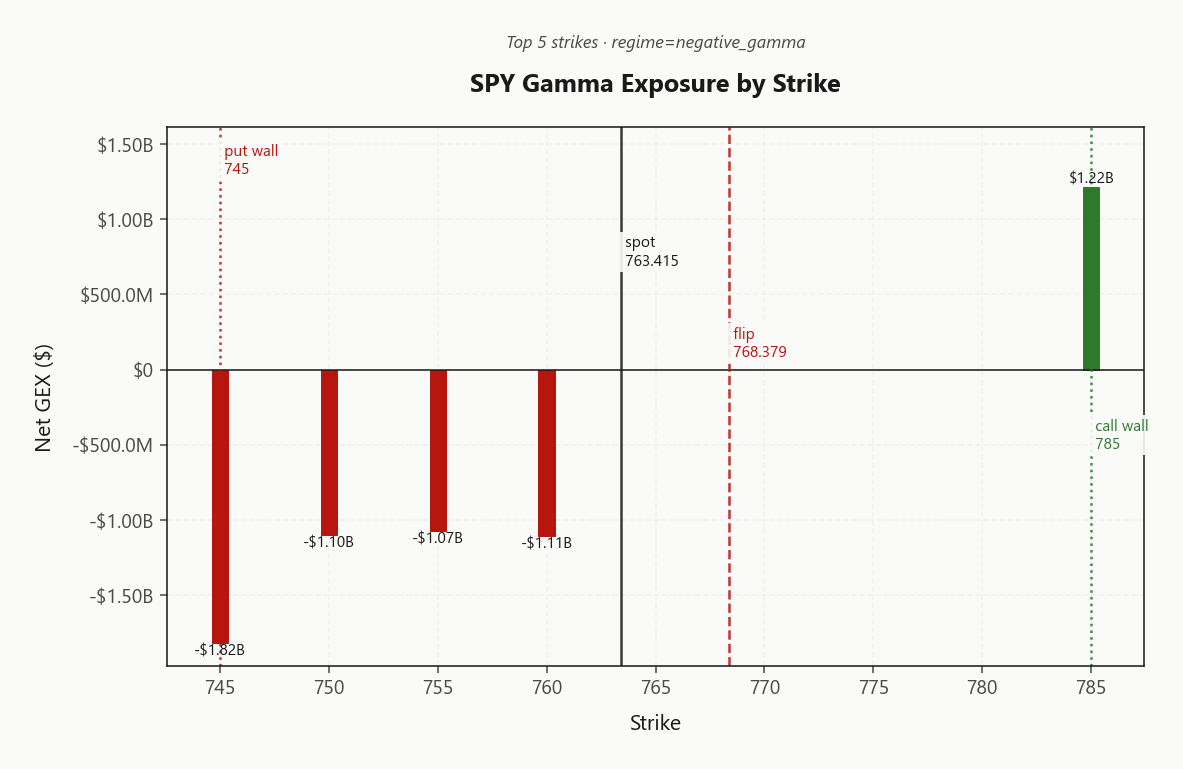
The call wall at 785.00 caps any rally attempt, and the put wall at 745.00 defines the trapdoor if bids fail. The top strike 745.00 carries -$1.82B in concentrated negative gamma - that's the pivot where dealer flow direction actually flips, not a decorative number on the chart.
Structure reads deep on liquidity but fragile on direction: plenty of size to trade against, no cushion beneath spot until the put wall. Route range structures respecting the 785.00 - 745.00 band; treat any break of 745.00 as a regime tell, not noise.
What it means for your trading
Spot below flip at 768.38 with concentrated negative gamma at 745.00 means dealers amplify downside - fade rallies into 785.00, respect the trapdoor at 745.00.
Trading readSPY sits below its gamma flip so every downside strike is an amplifier and every upside strike toward 785.00 is a dampener - fade rallies into the wall, respect the trapdoor at 745.00, and understand why the same tape reads differently on QQQ.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna prints -$69.91B - deeply destabilizing. Any vol pop forces dealers to sell delta into the move, turning an IV spike into a downside accelerant rather than a fade opportunity. Pair that with net charm at -$317.5K and the book leans one-way into the bell: time decay pulls dealer delta lower each session, manufacturing a persistent offer that thickens the last hour of tape.
The pivot sits at 760 with spot hugging it at -0.447332054% distance - bias reads Neutral, the tug-of-war zone where charm flow can flip direction on a single print. Above the pivot dealers relieve pressure; below it they press harder into weakness. This is the level that defines whether tomorrow's tape mean-reverts or trends.
Trade the asymmetry: fade rallies that stall before the pivot, respect breaks that clear it downside, and size vol sales knowing a spike in IV is not a gift here - it is a signal that dealer sell-flow is about to compound.
What it means for your trading
Vanna -$69.91B and charm -$317.5K both lean destabilizing, so vol pops amplify downside and time decay pressures dealers offer into close. Watch 760 as the flow-direction switch - bias is Neutral there now.
Cross-Asset Confirmation
Cross-asset tape reads coherent, not chaotic. MOVE at 110.49 (3.65%%) is quietly bidding while equity vol stays muted - bond vol is the leading tell here, and it says rate-path uncertainty is doing the pushing even as VIX prints benign. Fear & Greed at Fear (33) confirms sentiment is defensive without tipping into panic - the setup where positioning matters more than mood.
Index dispersion tells the day's story cleanly. QQQ at 740.61 holds the mega-cap cushion with dealer flow leaning supportive, while IWM at 277.96 confirms the small-cap fragility that VRP already flagged. SPX prints 7651.54 (-0.25%%) - mild drift, no capitulation flow, no conviction bid. Regime divergence stays Unknown across the complex.
Read: rate vol is the divergence to respect, not equity vol. Sell IWM premium where fragility is compensated, keep QQQ as the anchor, and treat MOVE drift as the early-warning line rather than the trigger.
What it means for your trading
Cross-asset signal reads Aligned - bond vol quietly bidding while equity vol and sentiment stay defensively muted. Trade the QQQ-cushion / IWM-fragile split, watch MOVE as the tell.
Scenario EV
The scoreboard is unambiguous: Iron Condor at 30-45 DTE clears the field with score 39, while the put spread trails at 27. Three independent inputs all point the same direction - Steep Contango carry from VIX9D 13.98 beneath VIX3M 18.24, ordered skew at 1.25% without smile blowout, and VVIX/VIX ratio 5.47 in the Low zone. Sell the wings, not the body.
The DTE window matters as much as the structure. Front vol trades too cheap against realized to justify a gamma sale, while the back end at VIX6M 20.26 decays too slowly to compensate for the calendar risk. The 30-45 belly is where the 30→60 forward at 19.1914551298 hands over the fattest carry per unit of gamma bleed.
Put-spread score 27 tells you the directional edge is thinner than the range trade - MOVE at 110.49 notwithstanding, no single-sided lean gets paid enough here. Route to IWM where VRP 6.96% is richest, size at Standard Size, and respect 760 as the flow-direction hinge.
What it means for your trading
Iron condor at 30-45 DTE with score 39 is the highest-conviction structure on the board - contango carry, contained skew, and Low vol-of-vol all validate premium sales at Standard Size. Route the risk to IWM where VRP 6.96% pays the most per unit of margin.
Actionable Summary
Primary trade: route the Iron Condor at 30-45 DTE into IWM, where VRP 6.96% dwarfs SPY 1.66% and QQQ 2.79%. Contango carry from VIX9D 13.98 up through VIX6M 20.26 pays the wings, and moderate skew 1.25% keeps put-side compensation fair.
What to avoid: naked short puts on SPY below the 768.38 flip - dealers amplify downside there, with net VEX -$69.91B turning any vol pop into a delta-sell cascade. Respect the 785.00 cap and 745.00 trapdoor; treat 760 as the pivot where dealer flow direction flips into monthly expiry.
Sizing and horizon: VVIX 89.77 against VIX 16.42 keeps vol-of-vol in the Low zone, so Standard Size is appropriate. Regime is Elevated / Watchful with a 15-session half-life - that is your trade window, not longer.
What it means for your trading
Sell wings where you are paid - IWM at 30-45 DTE - and hedge SPY structures around the 760 pivot with Standard Size until the 15-session half-life resolves.
Micron post-close print is the near-term event pressure point for semis positioning; options implied a slam-dunk which magnifies disappointment risk.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.32 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.38 against a spot of 763.42. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.44% with a volatility risk premium of 1.66%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.42. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime