Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 765.13 with net GEX -$5.88B - dealers are short gamma and the tape amplifies moves in both directions. Call wall sits at 770.00, put wall at 760.00, gamma flip at 768.22 - spot is below the flip by 0.4051050868%, meaning any bid gets faded until reclaimed. Dealer positioning: net vanna -$73.93B and net charm $229.9K - vol-up sells more delta (accelerant lower) but charm still nudges supportive into close. Vol read: VIX at 15.97, VVIX at 90.17, term structure Contango with near-slope 9.87%%, VRP at 1.11% - options carry richer than realized but the premium is thin. MOVE at 101.82 up sharply - bond vol is the tell, not equity vol. Bottom line: iron condor 30-45 DTE remains the recommended structure (Iron Condor), size standard per Standard Size, but respect 768.22 as the pivot - a break lower flips dealer flow destabilizing and expands range.
Negative gamma across index complex, SPY below flip at 768.22 - moves amplified, VIX contango intact
SPY at 765.13 sits below the gamma flip at 768.22 - dealer short-gamma amplifies both directions and the tape leans trend-following until spot reclaims the pivot. VIX at 15.97 in steep contango with VVIX at 90.17 keeps vol sellers paid, but MOVE at 101.82 flags a bond-vol tell that argues for tail hedges alongside carry. Cross-asset regime is aligned negative-gamma across SPY/QQQ/IWM - the lead story is the charm pivot at 768.2245602956, not divergence.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
765.13
768.22
-0.40%
770
760
770
-$5.88B
Short gamma
QQQ
736.80
737.35
-0.08%
740
730
725
-$1.58B
Short gamma
IWM
280.45
289.76
-3.22%
285
280
285
-$4.44B
Short gamma
VIX
15.97
16.03
-0.38%
20
15
19
-$20.90M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.12
11.01
+1.11
2.13
2.02
1.08
QQQ
17.93
16.02
+1.91
1.65
1.42
1.50
IWM
18.59
12.31
+6.28
1.02
2.31
1.03
VIX
285.02
102.25
+182.77
-123.57
0.31
0.04
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
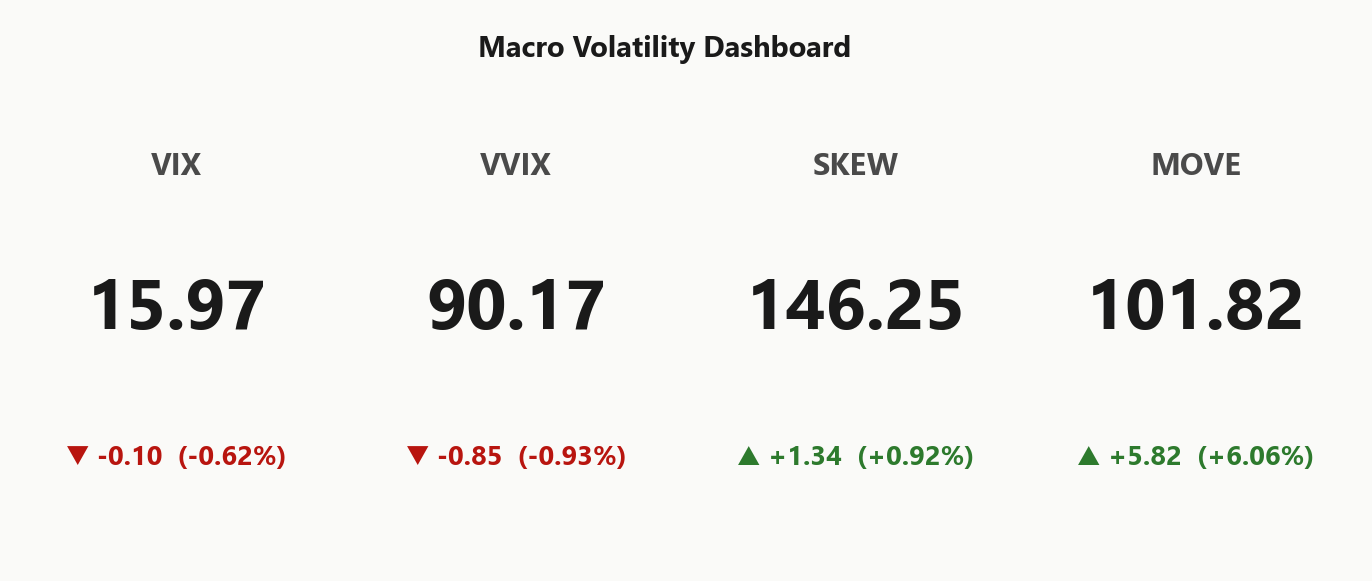
15.97
-0.62%
VVIX
90.17
-0.93%
SPX
7,680.84
-0.04%
SKEW index
146.25
+0.92%
MOVE (bond vol)
101.82
+6.06%
VIX term (9d/30d/3m/6m)
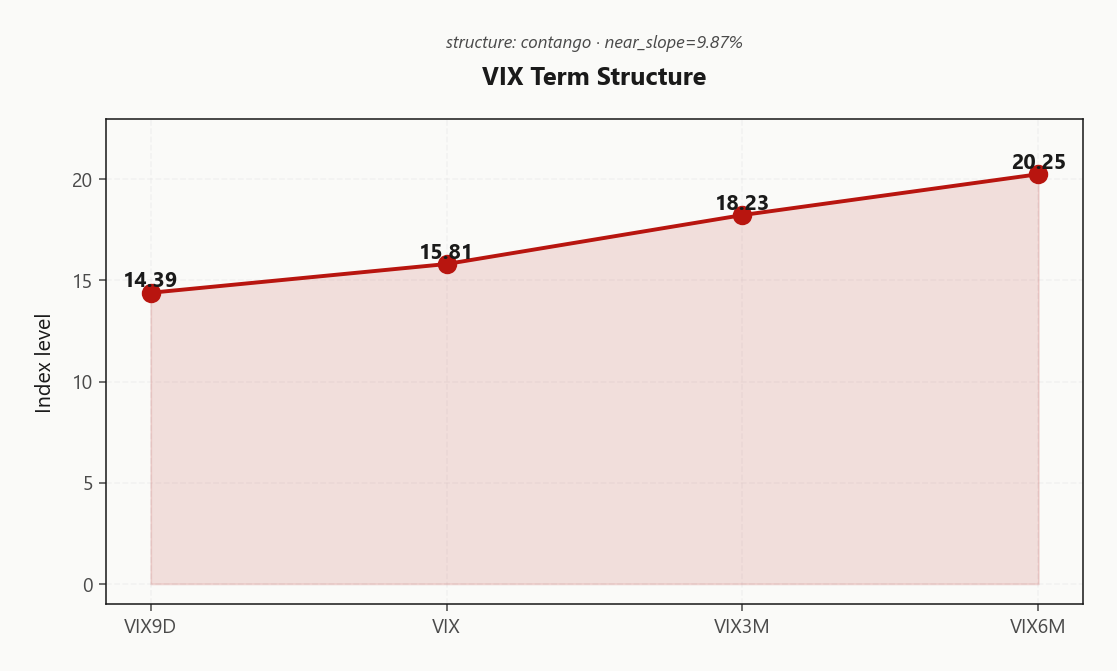
14.39 / 15.81 / 18.23 / 20.25
Steep contango
VVIX / VIX
5.65
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX at 15.97 - the state is Elevated, not panic, and the half-life of 15 sessions says this is a durable backdrop rather than a one-day shakeout. Signal color Yellow - watchful, not defensive.
Transition math backs the label: 5-session panic probability sits at 0.05, low enough that tail-risk pricing does not dominate structure selection, while the 10-session return-to-low probability of 0.45 keeps mean-reversion in play as the base case. The Aligned cross-asset picture confirms this is a regime-wide setting, not a single-index tell.
The wrinkle: MOVE at 101.82 up 6.06% lifts the tail-risk term even as VVIX at 90.17 holds normal. Trade the regime as elevated-carry, but keep wings on - bond vol is the leading indicator that could reprice the equity term inside the half-life window.
What it means for your trading
Regime is Elevated / Watchful and sticky at 15-session half-life - carry structures justified, but MOVE spike argues for wings, not naked short vol.
Trading readVIX contained, VVIX normal, SKEW elevated, MOVE spiking - three-of-four say calm, but MOVE is the outlier and historically the tell that leads equity vol by a few sessions.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
The long end keeps lifting: 3-month at 18.23 steps to 6-month 20.25, so the term premium is structural rather than event-driven. Forward 30-to-60 clears at 19.3266991491 - that's the bulge where sellers are paid without wearing near-term gamma risk.
Regime label Steep Contango confirms the seller bias, but contango depth argues calendars over outright short vol - the 9d-to-30d step is where any event premium would first appear, so structure trades to defend that segment while harvesting the 30-45 DTE window.
What it means for your trading
Steep contango with forward 30-to-60 at 19.3266991491 keeps vol sellers paid - watch the 9d-to-30d segment for the first sign of event-premium bid, and prefer calendars to outright short vol given the depth of the curve.
Trading readSteep contango says carry is the trade, front end reflects no immediate event pinch - vol sellers are paid but the slope also means any shock will crush 9d faster than 30d, so define risk with wings.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 12.12% against HV20 11.01 leaves a VRP of 1.11% - positive but skinny. Options carry works on paper, yet the premium doesn't compensate for the negative-gamma amplification risk underneath. Outright index short-vol is a marginal trade at these levels; the tape can spend the day chopping and still hand back the entire IV-RV cushion in a single dealer-forced move.
The cleanest premium in the complex is IWM: ATM IV 18.59% against HV20 12.31 prints VRP 6.28% - the richest carry on the board and the natural vehicle for the harvest. QQQ VRP at 1.91% sits between the two with realized staying sticky against HV60 19.46, so mega-cap-heavy index vol has already been re-priced closer to fair.
Ignore the flagged VIX VRP 182.77% - a data artifact, not a tradeable signal. Bottom line: small-cap remains the preferred vehicle for premium harvest, and SPX index vol is best expressed via defined-risk structures rather than naked shorts.
What it means for your trading
IWM VRP at 6.28% is the fattest premium in the complex - favor small-cap wings on the Iron Condor, and treat SPY's 1.11% as too thin to justify naked index short-vol.
Skew Convexity
SPY quarter-delta skew prints 2.13% with a smile ratio of 1.15% - put wing bid but ordered, not panic. Downside IV at 16.45% versus upside 14.32% against ATM 15.14% confirms the asymmetry - the put side is paying, but the curve stays coherent with a Skew Steep read rather than a stress print.
Smile ratio above parity locks in downside convexity as the market's dominant bid, consistent with dealers pressed short-gamma below the flip at 768.22. QQQ quarter-delta skew at 1.65% sits between SPY and IWM, while IWM's shallower 1.02% makes small-cap wing hedges the cheaper relative buy - the tail is priced richer on the index than on the beta vehicle.
Route protection via put spreads, not naked puts: VRP at 1.11% is too thin to pay full theta on outright downside, and skew steepness already funds the offset leg. IWM condor wings capture the fatter 6.28% without importing SPY's convexity premium.
What it means for your trading
SPY quarter-delta skew at 2.13% and smile ratio 1.15% keep the put wing bid but orderly - spread put protection dominates naked longs given the thin 1.11%. IWM's flatter 1.02% makes small-cap the cleaner wing on any condor structure.
Vol-of-Vol Structure
VVIX sits at 90.17 against VIX at 15.97, putting the ratio at 5.65 - vol-of-vol reads Normal, well south of the jump-risk comfort zone. There is no bimodal-outcome premium embedded in the vol surface; the market is not paying up for a shock it can already smell.
Sizing guidance comes back Standard Size - full-size premium selling is justified rather than defensive trimming. The coherent VVIX-VIX relationship confirms a single-regime tape: vol is elevated but stable in character, not fragile in character, and that distinction is what separates carry trades that work from carry trades that get run over.
The caveat is cross-asset. MOVE at 101.82 spiked 6.06% overnight while VVIX stayed pinned - bond vol is leading, equity vol-of-vol is lagging. Historically that gap closes, not the other way around. Size Standard Size today, but keep the wings on and don't add on any VVIX drift toward the upper band.
What it means for your trading
Vol-of-vol at Normal with VVIX/VIX ratio 5.65 greenlights Standard Size premium selling - but MOVE at 101.82 is the cross-asset tell that VVIX may catch up, so keep structures defined-risk, not naked.
Dispersion Spread
Index vol prints 12.12% ATM against a mega-cap tape that spent the overnight session repairing gamma - NVDA, META, and MSFT all logged positive GEX shifts, meaning the idiosyncratic weight is concentrated in three names carrying the QQQ complex. Dispersion signal reads Moderate, not extreme - the SPY-to-single-name IV differential is compressing, but the correlation trade isn't priced for a break.
QQQ ATM IV at 17.93% carries the mega-cap idiosyncratic premium; the tech-heavy index is effectively a levered NVDA/META/MSFT expression right now, and basket vol sellers get whipsawed if any of the three loses its positive-gamma anchor. IWM at 18.59% stays the clean small-cap beta - no single-name concentration risk, just broad negative-gamma tape.
Prefer SPX vol selling over dispersed basket structures in this regime - index premium harvests correlation without paying single-name concentration risk, and IWM wings remain the richer premium leg. Dispersion trades are a fade here, not an entry.
What it means for your trading
Dispersion signal reads Moderate - mega-cap gamma repair concentrates idiosyncratic risk in NVDA/META/MSFT, arguing for SPX-level vol selling over baskets and IWM wings for the richer VRP capture.
Liquidity & Microstructure
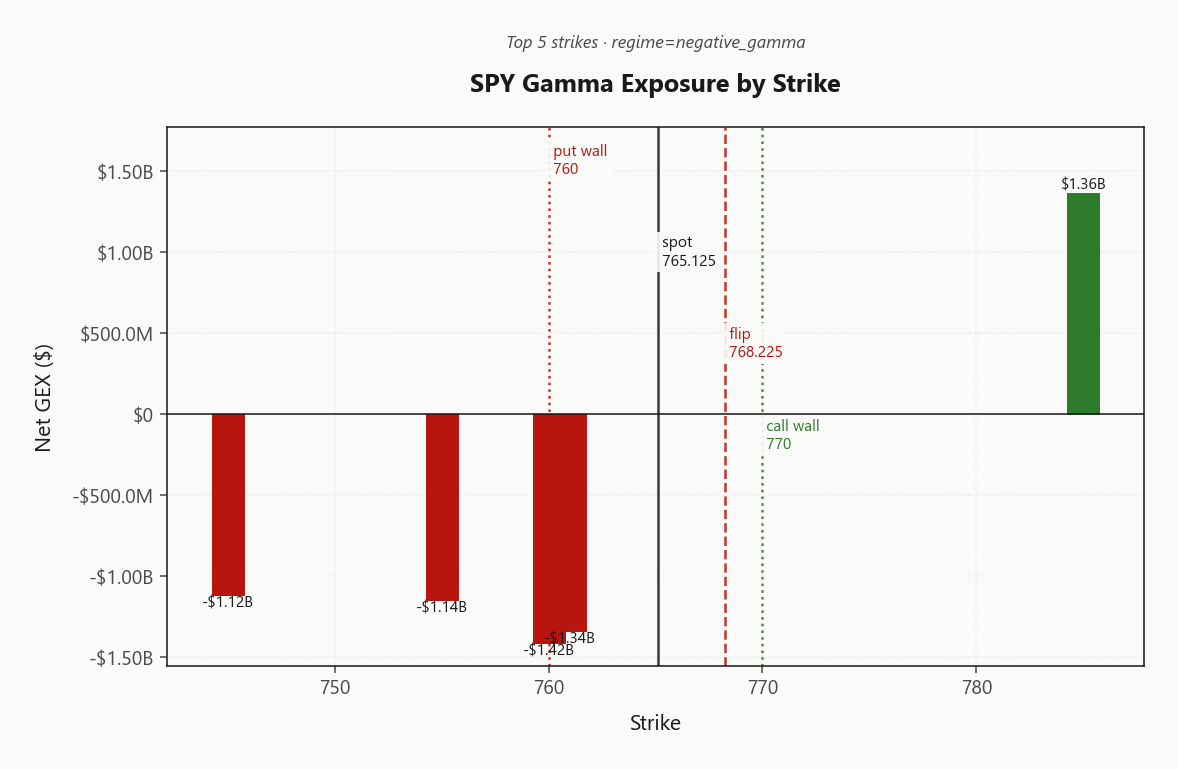
SPY's OI stack anchors at 700, a long-dated put cluster that magnets the tape and defines the downside gravity well below current spot. The gamma flip at 768.22 is the level of the session - spot sits below it by 0.4051050868%, keeping dealer flow in Destabilizing mode where every push gets amplified rather than absorbed.
The call wall at 770.00 caps upside pressure and the put wall at 760.00 acts as the pin magnet, but the amplifier lives at 760.00 - carrying -$1.42B in negative gamma, that strike is where dealer hedging turns violent if spot walks into it. QQQ's OI-weighted DTE at 124.1 sessions confirms the positioning is medium-term structural, not an intraday chase - the book is built to persist.
Book depth reads Deep, but depth cuts both ways below the flip: liquidity provides the runway for trend continuation as much as it provides the ballast for a reversal. Reclaiming 768.22 flips the regime supportive; failing keeps the amplifier live.
What it means for your trading
SPY's microstructure is anchored by the 700 OI cluster with the gamma flip at 768.22 defining destabilizing versus supportive dealer flow. Spot below the pivot leaves the 760.00 negative-gamma strike as the amplifier to watch.
Trading readDeep negative gamma below spot means every push lower gets amplified by dealer selling - fade rallies into 770.00, respect the 760.00 magnet, and treat 768.22 as the single line separating destabilizing from supportive flow.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna prints -$73.93B - dealers are structurally short vega, so any vol expansion forces incremental delta selling and hardwires a negative feedback loop into the tape. Net charm at $229.9K is positive but modest, offering a mild close-supportive bid rather than a genuine offset. The two Greeks disagree in direction but agree in magnitude - charm cannot outrun vanna if VIX lifts intraday.
The charm pivot sits at 768.2245602956, the single line separating stabilizing from destabilizing dealer flow. Spot trades 0.4051050868 below it, leaving current bias Destabilizing - every bid gets faded until reclaimed, and every push lower recruits fresh dealer supply via vanna.
Reclaim 768.2245602956 and the regime flips supportive as vanna hedging reverses; fail it and dealer flow keeps amplifying the range. Trade the pivot, not the price.
What it means for your trading
Vanna at -$73.93B makes vol-up a downside accelerant while charm at $229.9K offers only a thin close bid - the 768.2245602956 pivot is the regime switch, and spot sits Destabilizing below it.
Cross-Asset Confirmation
MOVE at 101.82 jumped 6.06%% overnight while VIX sits contained at 15.97 - this is a credit and rates story, not equity panic. The divergence matters: bond vol has historically led equity vol by a handful of sessions, and today's tape is pricing that lag as calm rather than a warning. Fear & Greed at 34 reading Fear confirms defensive positioning is already in place, which sets up a contrarian rebound only once spot reclaims the pivot at 768.2245602956.
Cross-asset regime is Aligned - SPY, QQQ at 736.80, and IWM at 280.45 all sit in negative-gamma below their respective flips. There is no divergence to fade, no relative-value crack to trade; the fragility is regime-wide.
The actionable read: bond-vol contagion is the tail-risk term to price, not the base case. Keep condor wings wide enough to survive a MOVE-led vol expansion that catches VVIX offside.
What it means for your trading
Bond vol at 101.82 is the day's tell against a Aligned negative-gamma equity complex - no cross-asset divergence to trade, but tail-risk pricing must respect the MOVE spike even with VIX contained.
Scenario EV
Recommended structure: Iron Condor in the 30-45 DTE window. The setup is coherent - VIX term structure in Contango with near-slope 9.87%, vol-of-vol Normal at ratio 5.65, and a thin but positive VRP - argues carry over convexity. Condor scores 40 versus the put-spread at 28, so the balanced structure wins on the tape.
Wing selection matters here. SPY VRP at 1.11% is skinny; IWM at 6.28% carries the richer premium, making small-cap the preferred wing for harvest. The 30-to-45 DTE window sidesteps near-term gamma risk while sitting on the fat part of the forward curve - forward 30-to-60 vol prints 19.3266991491, exactly where premium sellers get paid without eating the front-end kink.
Sizing stays Standard Size - no jump-risk premium to defend against. But respect the negative-gamma regime: define wings tightly, avoid naked short vol, and treat 768.2245602956 as the pivot that would force a re-underwrite of the structure.
What it means for your trading
Iron condor at 30-45 DTE is the trade - carry regime intact, IWM the preferred wing for VRP, sizing Standard Size, VRP read Unknown. Respect 768.2245602956 as the pivot that flips the structural thesis.
Actionable Summary
Bottom line: deploy Iron Condor in the 30-45 DTE window, favor IWM wings where VRP at 6.28% pays richer than SPY's 1.11%, and size standard per Standard Size. The trade is carry, not convexity - VIX Contango with near-slope 9.87% keeps sellers paid, and VVIX/VIX at 5.65 confirms no jump-risk premium to defend against.
Watch the charm pivot at 768.2245602956 - spot sits 0.4051050868 below with bias Destabilizing; reclaim flips dealer flow supportive, failure keeps the tape amplifying moves into 760.00. MOVE at 101.82 up 6.06% is the day's cross-asset tell - bond vol leads equity vol by a few sessions and argues for tail hedges alongside the carry book.
Avoid naked short vol in the Elevated / Watchful regime, especially 0DTE where negative-gamma amplification hits hardest. Hedge via put spreads over naked puts - skew at 2.13% already prices the tail and outright puts bleed theta into a sticky regime with half-life 15 sessions.
What it means for your trading
Iron condor 30-45 DTE with IWM wings is the trade; the single line to watch is 768.2245602956 - below keeps dealer flow destabilizing, reclaim flips the tape supportive.
10-year stocks-minus-bonds return near record - signals mean-reversion setup for the bond allocation, relevant given today's MOVE spike raising real yields.
UK airbase incident tied to a foreign state - geopolitical tail risk, exactly the kind of event that pushes MOVE higher without moving VIX and explains today's cross-asset divergence.
Dollar near two-month peak on rising yields, jobs data ahead - creates event risk into end of week and validates VIX term-structure event premium if it materializes.
Stocks fell overnight on higher oil and yields - sets up today's negative-gamma tape as a continuation, not a reversal.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.97 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.22 against a spot of 765.13. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.12% with a volatility risk premium of 1.11%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.97. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime