Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 763.42 sits in negative gamma with net GEX at -$9.76B - dealers short gamma, moves get amplified below the flip. Key levels: gamma flip at 767.51, call wall 785.00, put wall 760.00 - spot is currently pinned right at the put wall, meaning we're at the tripwire between charm-supported grind and reflexive selloff. Dealer vanna is hostile (vol up = dealers sell delta) while charm is still supportive into close - that tension resolves at the 760 pivot. VIX at 16.18 with term structure in Steep Contango - front-month VRP is 1.3% vol points, carry is there but not screaming rich. MOVE at 101.82 jumped 6.06%% - rates market is quietly hedging while equity vol sleeps. Bottom line: iron condor 30-45 DTE is the recommended structure (Iron Condor, score 41), avoid naked short puts until we reclaim the flip, and treat 760.00 as the line where the whole thesis flips.
Negative gamma across index complex with SPY at 760 pivot; contango carry favors 30-45 DTE condors.
Index complex sits in aligned negative gamma with SPY pinned near 760 put wall, meaning any breach below flips dealer flow from supportive charm to reflexive selling. VIX term structure remains in steep contango at Steep Contango with VVIX comfortably normal, so vol sellers are paid to carry - but the elevated MOVE and Fear rating say the tape is quietly hedging credit and rate risk. Optimal expression is the iron condor at 30-45 DTE, sized standard, with the put wall as the tripwire.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
763.42
767.51
-0.53%
785
760
770
-$9.76B
Short gamma
QQQ
737.28
737.75
-0.06%
740
735
725
-$1.39B
Short gamma
IWM
277.91
290.65
-4.38%
285
275
285
-$5.41B
Short gamma
VIX
16.17
16.20
-0.16%
20
16
19
-$25.69M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.34
11.04
+1.30
1.78
2.02
0.98
QQQ
17.71
16.02
+1.69
2.39
1.42
1.08
IWM
18.89
12.31
+6.58
1.51
2.31
1.47
VIX
277.34
102.26
+175.08
-117.38
0.31
0.45
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
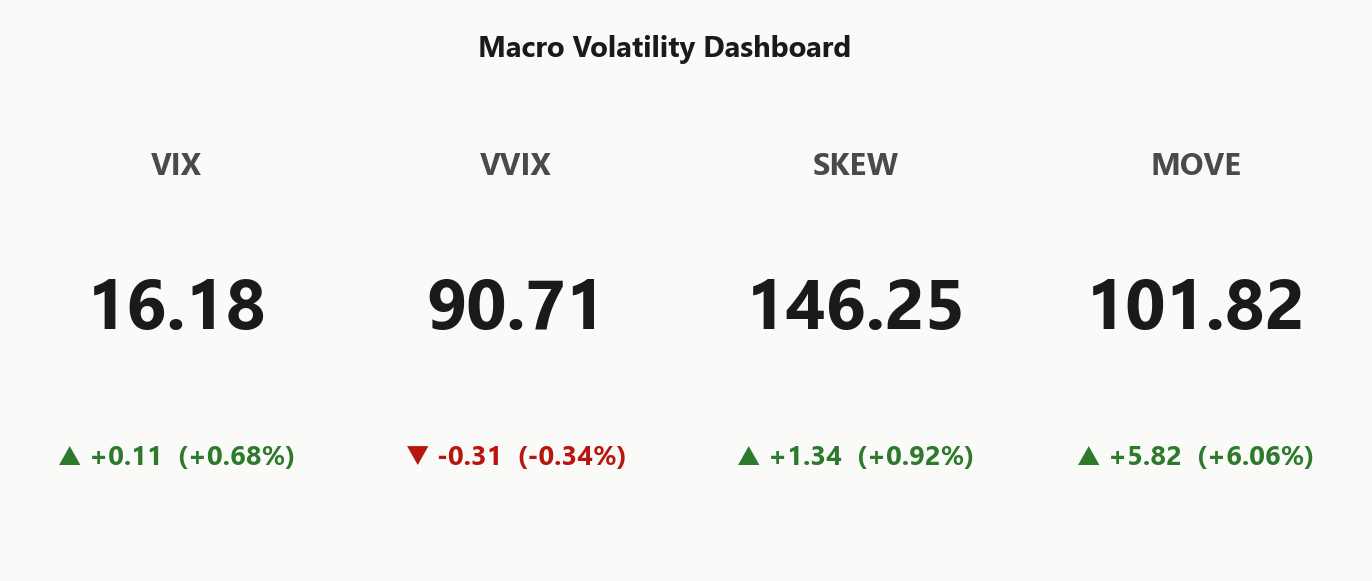
16.18
+0.68%
VVIX
90.71
-0.34%
SPX
7,664.35
-0.25%
SKEW index
146.25
+0.92%
MOVE (bond vol)
101.82
+6.06%
VIX term (9d/30d/3m/6m)
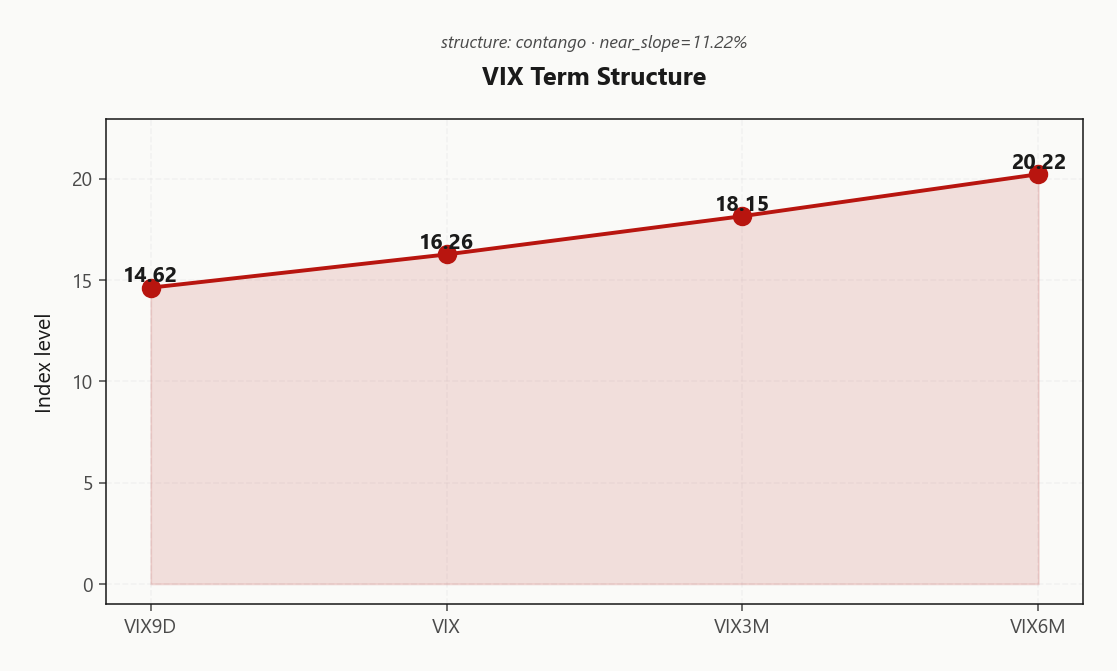
14.62 / 16.26 / 18.15 / 20.22
Steep contango
VVIX / VIX
5.61
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in Elevated / Watchful territory with VIX anchored at 16.18 - elevated enough that hedges are on the sheet, calm enough that carry still compounds. This is not a panic setup; it is a watchful carry regime where the crowd has already paid for insurance and dealers are grinding against it.
The transition math favors mean-reversion: probability of moving to a low-vol regime over ten sessions runs 0.45, while the tail-risk path to panic over five sessions sits at 0.05 - low but non-zero, and not a number to structure trades against. Regime half-life is 15 sessions, meaning this state is medium-sticky, not hair-trigger.
Practical read: the base case is drift toward low-vol, not spike to panic. Structure for the carry, not the tail - trades that need a panic to pay are wrong-way today.
What it means for your trading
Regime is Elevated / Watchful with a 0.45 base case toward low-vol over ten sessions and only 0.05 probability of panic in five - sell the carry, not the tail.
Trading readVIX modest, VVIX normal, SKEW elevated at 146.25, MOVE popping - the divergence is MOVE leading. Rates vol is hedging first, and historically that precedes equity vol catching up within a week or two.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve sits in Steep Contango - Steep contango - vol sellers favored - with VIX9D at 14.62, spot VIX at 16.26, VIX3M at 18.15, and VIX6M at 20.22. Structural carry is intact and no event premium is being paid in the belly - the term structure is doing the classic Contango roll that rewards sellers who hold and let time work.
Front-week IV is being crushed by charm, so naked strangles in the near-DTE bucket pay less than they cost in gamma noise. The belly is where the edge lives: 30-45 DTE captures the steepest part of the roll-down without eating terminal-week gamma or reflexive vanna. Calendars work on the front, but outright short-vol structures should be pushed out.
Per scenario_ev, the sweet spot is unambiguous - 30-45 DTE at a Iron Condor score of 41, standard size. Sell the belly, avoid the front, let the curve pay you the roll.
What it means for your trading
Steep contango with no event premium means the 30-45 DTE belly offers the cleanest short-vol carry - front-week IV is charm-compressed and terminal-week gamma is punitive, so the middle of the curve wins on risk-adjusted roll-down.
Trading readContango slope 11.22%% with VIX9D well below VIX3M - vol sellers get paid the roll, no event premium priced. This is a boring-but-profitable carry regime unless MOVE keeps ramping.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 12.34% against HV20 of 11.04 leaves a thin VRP of 1.3% vol points - options are cheap by historical standards but nowhere near giveaway. HV60 at 11.17 confirms realized has tracked consistently below implied, which supports a short-vol tilt without demanding a fire-sale entry. This is a carry environment: quality over quantity for index premium sellers.
The standout is IWM, where VRP prints 6.58% vol points - an order of magnitude richer than SPY on a per-unit-of-delta basis. That is where the premium lives, and where 30-45 DTE structures earn their keep. Small-cap dispersion is not being masked by index hedges; the wing is doing real work and the carry is measurable rather than aspirational.
Bottom line: sell IWM vol as the primary expression, use SPY as the cleaner but thinner secondary carry, and treat the persistent realized-below-implied print as the underwriting thesis - not the trade itself.
What it means for your trading
Realized has hugged below implied across the SPY vol cone, but the SPY VRP at 1.3% is a carry trade, not a mispricing - the richer edge is IWM at 6.58%, where the premium per unit of risk is materially fatter.
Skew Convexity
The 1.78% vol-point put-call spread at the quarter-delta with a smile ratio of 1.12% paints a wing that is bid but ordered - put IV at 16.33% against ATM 15.36% is a systematic hedge, not a capitulation grab. This is the shape of a book that has already bought its protection, not one scrambling for it.
The upside tells the more interesting story: call quarter-delta IV at 14.55% prints below ATM - the smile is inverted on the right side and there is zero premium being paid for a chase higher. Covered calls and call-spread overwrites are cheap financing here; nobody is bidding the upside wing.
Structure accordingly: put spreads over naked short puts, because the wing is doing real work and selling it naked forfeits the convexity you already paid for. Pair with call-side overwrites to harvest the flat right side - the two-sided expression is the iron condor at 30-45 DTE, which is exactly what scenario EV ranks first.
What it means for your trading
Skew is defensively hedged, not panicked - put wing bid at 1.78% vol points while the call side sits inverted, meaning the market is paying for downside and giving away upside. Spread the puts, overwrite the calls, and let the condor at 30-45 DTE carry the tape.
Vol-of-Vol Structure
VVIX prints 90.71 against VIX at 16.18, pinning the ratio at 5.61 - squarely Normal. No jump premium being paid, no bimodal tail being hedged. The vol-of-vol tape is telling you the market has already digested the negative-gamma regime and isn't bracing for a convexity event on top of it.
That reads through directly to sizing: guidance is Standard Size. No reason to trim condors, no reason to half-clip the short strangle wings against a phantom vol-of-vol spike. When VVIX/VIX sits in its normal band, the distribution of vol outcomes is well-behaved and standard notional carries its own weight without a haircut.
This is the boring middle where carry compounds cleanly - the setup rewards discipline, not defensive posturing. Sell the belly, roll the theta, and let the ratio stay where it is.
What it means for your trading
VVIX/VIX at 5.61 is Normal - no convexity premium, no reason to shrink size. Standard notional on 30-45 DTE condors is the base case until the ratio pushes out of range.
Dispersion Spread
Index vol is moderate but the cross-section is wide: SPY ATM at 12.34% against IWM at 18.89%, with QQQ in the middle at 17.71%. That gap is not being masked by index hedges - small-cap idiosyncratic risk is being priced separately from the mega-cap complex, and the dispersion premium is living in IWM single names, not in the SPX sheet.
The cleaner carry vehicle is the index. SPY vol selling gets you diversified beta with dealer positioning aligned across the complex (Aligned), whereas single-name premium in small-caps carries genuine name-specific tail. Correlation regime says an index hedge will not cover an IWM component blow-up - sell SPX/SPY vol against the basket, don't chase individual name premium to harvest the spread.
What it means for your trading
Wide IV dispersion between SPY at 12.34% and IWM at 18.89% favors index vol selling over single-name premium - the correlation setup means index hedges won't offset small-cap idiosyncratic risk.
Liquidity & Microstructure
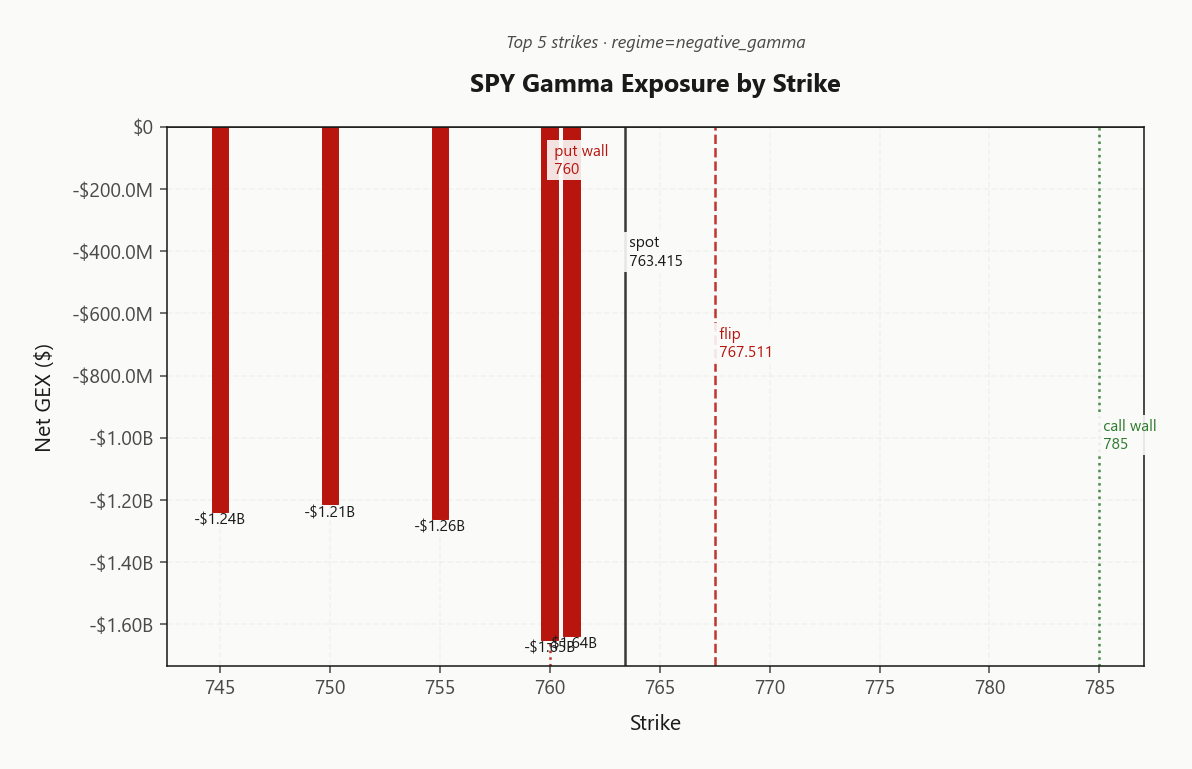
The book is anchored by an OI magnet at 700, but that strike is scenery - the live battle sits in the 760.00 - 785.00 band with spot pinned directly on the put wall. Top-strike net GEX of -$1.65B at 760.00 concentrates dealer inventory exactly where price is trading, turning the wall into the trip-wire rather than a cushion.
With the gamma flip at 767.51 and spot below it, dealer hedging is reflexive, not stabilizing - any breach lower forces sellers into weakness instead of catching it. The regime read is Negative Gamma and the pivot bias is Neutral at 760, which is the same put wall in a different costume.
Pin risk toward 700 is distant enough to ignore near-term; the actionable level is 760.00, full stop. Hold it and charm carries the tape; lose it and dealer flow ignites into 767.51.
What it means for your trading
Spot on the put wall with dealer flow reflexive below the flip means 760.00 is the single level where the whole liquidity picture inverts - above it, boring carry; below it, amplified selling into 767.51.
Trading readMassive negative gamma stacked at the 760.00-785.00 band with spot pinned right at the put wall - dealers amplify any breach below, and the only cushion is a distant OI magnet at 700. Fade strength into the call wall, treat the put wall as the tripwire.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna sits at -$58.92B against net charm of $3M - a hostile-vanna, supportive-charm split that defines the entire close. Any VIX spike forces dealers to sell delta into weakness; absent that spike, charm decay quietly pins the tape toward settlement. The two forces are pulling in opposite directions, and the resolution level is not ambiguous.
The pivot is 760 - the Put Wall - with current bias reading Neutral. Above that line, charm carries the tape into the bell and the boring-carry thesis holds. Below it, vanna dominates and every uptick in 16.18 translates directly into reflexive dealer selling. This is a single-level trigger, not a zone.
Structure trades around the pivot, not around a directional view. Sell premium above; stand down below. The vanna asymmetry means the cost of being wrong on a breach is materially higher than the cost of missing the grind.
What it means for your trading
Vanna hostile, charm supportive - the tension resolves at 760, and every thesis inverts on a breach of that Put Wall.
Cross-Asset Confirmation
The tell today isn't in equity vol - it's in rates. MOVE at 101.82 jumped 6.06%% while VIX barely twitched, and that divergence is the kind of quiet repricing that historically front-runs equity vol by a session or two. Rates desks are hedging first; equity desks are still collecting carry. Fear & Greed sits at Fear with a score of 32 - the crowd is already defensively positioned even as spot vol sleeps, which is a positioning tell, not a sentiment one.
Across the index complex, QQQ at 737.28 and IWM at 277.91 sit in the same negative-gamma regime as SPY - Aligned, no arb to short between them. When the complex moves as one bloc, the trade is magnitude, not rotation: IWM breaks its flip first if the tape rolls, and the MOVE-led hedging bid is the pre-position for that scenario.
What it means for your trading
MOVE leading VIX with F&G at Fear is a credit/rates hedge signal, not an equity capitulation signal - carry the condors, but keep the put wall as the tripwire because the aligned negative-gamma complex means one break drags the whole bloc.
Scenario EV
The scoreboard is unambiguous: Iron Condor prints at 41 against the put spread at 28 - a spread wide enough that the structure choice is not a coin flip. Contango carry at Steep Contango, VVIX squarely Normal, and a modest but persistent VRP combine into the textbook condor setup: two-sided premium capture with no jump premium to underwrite and no vol-of-vol tax on sizing.
Optimal window is 30-45 DTE. Near-dated structures get shredded by charm crush inside the terminal week, and the front-belly captures the cleanest roll-down before gamma turns reflexive. Sizing guidance from the vol-of-vol read is Standard Size - no need to trim for a binary that isn't being priced.
Bias: sell the belly, spread the wings outside 785.00 and 760.00, and treat the pivot at 760 as the kill switch.
What it means for your trading
Iron condor at 30-45 DTE is the highest EV/risk expression today, beating the put spread by a decisive score margin with standard sizing supported by Normal vol-of-vol.
Do: prefer put spreads over naked short puts - the wing is bid (25d skew 1.78%) and doing real work. IWM carries the richest premium at 6.58% vs SPY 1.3% - size for the beta but that's where the condor pays. Don't: chase upside (call skew flat, zero conviction priced) or touch near-DTE structures where charm crush and reflexive vanna dominate. Avoid single-name premium - the index is the cleaner carry vehicle with dispersion this wide.
Watch:760 is the tripwire - spot is sitting on the put wall and every thesis inverts below it. Above pivot, charm carries the tape into close; below, vanna dominates and the 767.51 flip becomes the next domino. MOVE at 101.82 is the tell to monitor - rates vol leading equity vol is the divergence that ends this carry regime.
What it means for your trading
Iron condor at 30-45 DTE is the recommended expression (score 41 vs put spread 28) in a Elevated / Watchful regime. Treat 760 as the single level where the entire structure flips from charm-supported carry to reflexive vanna-driven acceleration.
AI labor-market anxiety from a former Commerce Sec is exactly the kind of narrative that seeds put buying in mega-cap tech - worth watching against META and NVDA flow.
A call that bonds are the best buying opportunity in decades is macro-relevant because it validates the MOVE-index tension we're already seeing today; if bonds bid, equity vol has cover to keep drifting.
Anthropic IPO filing and OpenAI pulling a model over safety signal that AI supply-side news is back on the front page - expect single-name IV bumps in the AI complex.
Rubio confirming foreign-state involvement in a UK airbase incident is a live tail-risk headline that the MOVE index is likely already partially pricing.
Trump-Iran sanctions denial with Tehran signaling talks is the kind of headline that can whipsaw oil and by extension energy-weighted small-caps in IWM.
A framing piece on bonds entering a new rate era matters because it sets the narrative backdrop for why MOVE is bid even as VIX sleeps.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.17 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.51 against a spot of 763.42. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.34% with a volatility risk premium of 1.3%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.18. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime