Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed at 764.65 in Negative Gamma with net GEX -$7.24B - dealers short gamma, moves amplified. Gamma flip sits at 768.63 with spot below; call wall 785.00, put wall 760.00, high-OI magnet at 700. Dealer positioning is destabilizing: net VEX -$78.05B means a vol spike forces dealers to sell delta, and charm at -$1.2M adds pressure into close. VIX at 16.02 sits in Steep Contango versus VIX3M 18.15; VVIX 90.06 keeps sizing standard while MOVE at 106.60 runs hot - the bond-vol/equity-vol gap is the lead risk. SPY VRP 1.12% is thin but IWM VRP 5.97% pays for structured shorts. Bottom line: Iron Condor at 30-45 DTE, IWM-weighted, and stand down risk if SPY reclaims 768.63 or MOVE breaks higher.
SPY negative gamma pinned below flip at 768.63; iron condor 30-45 DTE optimal in Steep Contango
SPY closed the session in Negative Gamma with spot pinned below the gamma flip at 768.63, keeping dealer flow destabilizing into tomorrow's open. Vol structure is in Steep Contango with VVIX at 90.06 still normal, but MOVE reaccelerated to 106.60 while VIX at 16.02 barely moved - bond vol is the tell. IWM VRP at 5.97% vs SPY 1.12% keeps small-cap the preferred vol-sell venue for the recommended Iron Condor at 30-45 DTE.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
764.65
768.63
-0.52%
785
760
760
-$7.24B
Short gamma
QQQ
738.32
-
-
740
730
725
$1.20B
-
IWM
279.12
290.33
-3.86%
285
275
285
-$5.09B
Short gamma
VIX
16.03
16.03
-0.02%
20
16
19
-$19.28M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.15
11.03
+1.12
1.55
2.26
0.97
QQQ
17.62
16.02
+1.60
2.27
1.42
1.08
IWM
18.23
12.26
+5.97
1.56
2.31
1.28
VIX
284.68
102.13
+182.55
-122.60
0.31
0.44
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
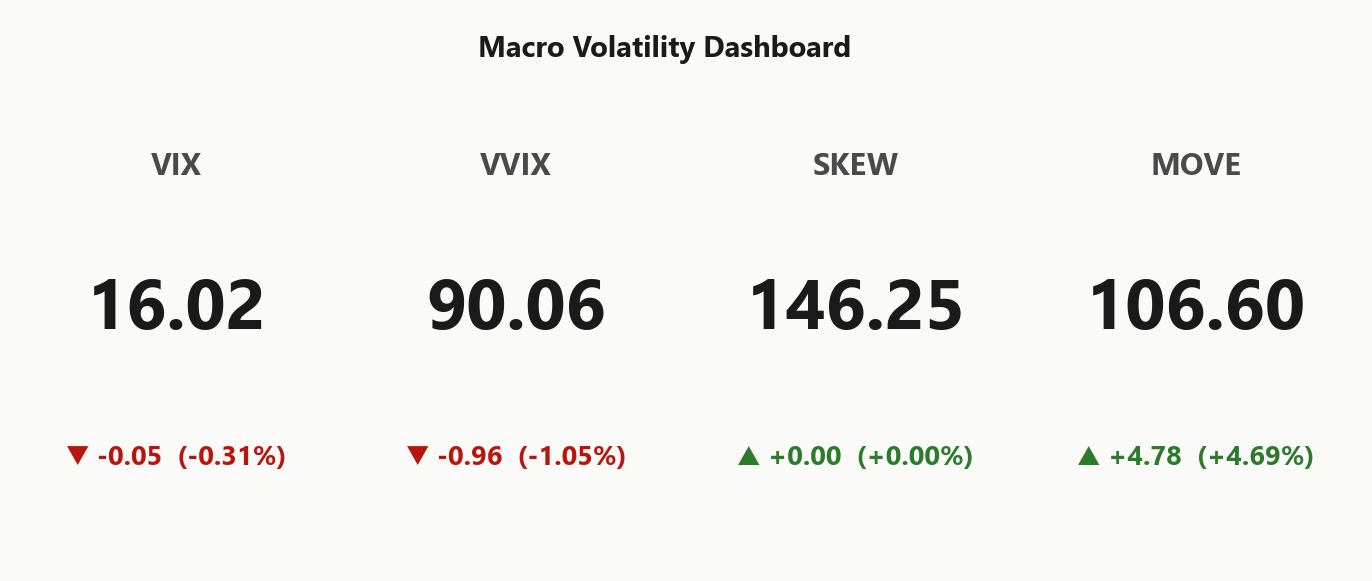
16.02
-0.31%
VVIX
90.06
-1.05%
SPX
7,670.84
-0.17%
SKEW index
146.25
0.00%
MOVE (bond vol)
106.60
+4.69%
VIX term (9d/30d/3m/6m)
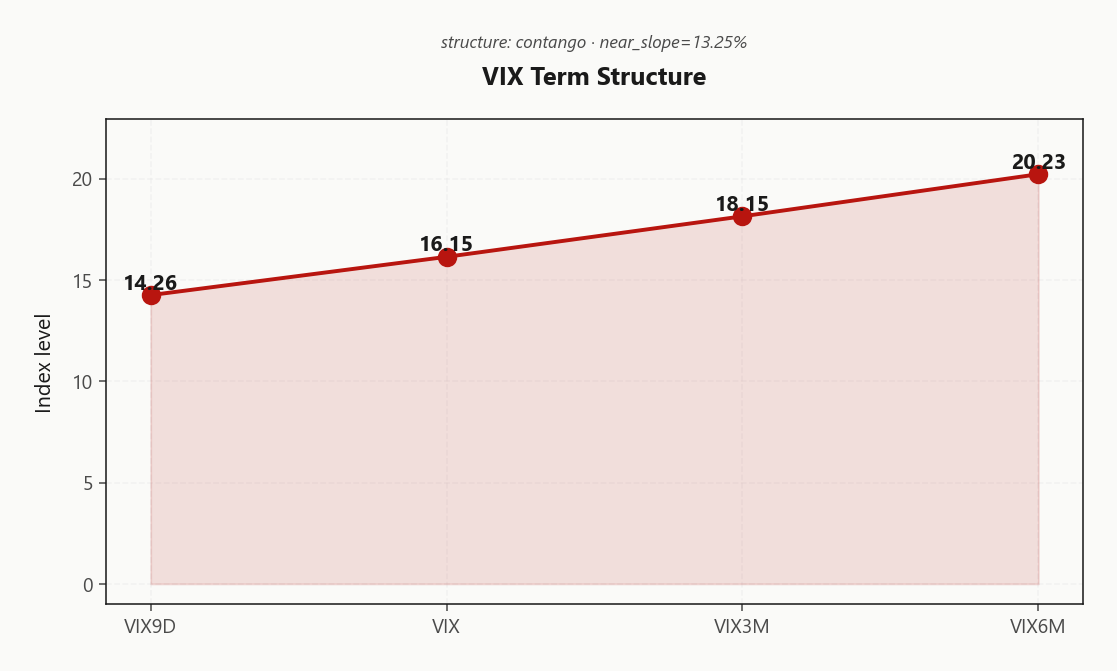
14.26 / 16.15 / 18.15 / 20.23
Steep contango
VVIX / VIX
5.62
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in an Elevated / Watchful regime with VIX anchored at 16.02 and a half-life of 15 sessions - sticky enough to run the carry, fragile enough to respect. The transition matrix keeps panic escalation at 0.05 over the next five sessions - low, but not a zero to ignore when MOVE is reaccelerating and SPY closes below the flip.
The modal path is decay lower: 0.45 probability of transitioning to a low-vol regime over ten sessions if MOVE settles and the term structure holds Steep Contango. That's the base case the Iron Condor at 30-45 DTE is priced against - sticky elevated vol that grinds toward the lower state without a shock in between.
Trade the persistence, not the tail. Don't fade a 15-session regime prematurely, but treat a MOVE breakout or a reclaim of 768.6269976231 as the two signals that flip the playbook - the first accelerates toward panic, the second collapses toward the low-vol modal path early.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - carry the sticky state via the recommended structure, but treat MOVE breakouts and a gamma-flip reclaim as the binary regime-change triggers.
Trading readVIX and VVIX are calm while MOVE and SKEW carry the stress signal - this is a classic bond-vol leads equity-vol setup, and the divergence usually resolves with equity vol catching up, not the other way around.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX complex prints textbook Contango with 14.26 under 16.15 under 18.15 under 20.23 - a clean upward slope that pays the carry trade without pricing any near-term event stress. Near slope at 13.25%% and futures basis at 12.38%% both confirm the structural roll-down is intact, and the curve reads Steep Contango rather than complacent.
The richest carry-to-realized bucket sits in the belly: forward 30→60 implied at 19.0715101657 is where the recommended Iron Condor lives, and it prices well above front vol without demanding you sit through a 9D collapse. If the near end breaks lower and the 9D-to-3M section flattens, pull DTE forward and take the carry earlier rather than defending a stale slope.
Signal color reads Green - sellers favored while the curve holds shape. Any flip toward backwardation or a compression in the front two tenors kills the trade cleanly; treat that as the exit trigger, not the entry retest.
What it means for your trading
Steep Contango from 14.26 through 20.23 pays the Iron Condor carry, with forward 30→60 at 19.0715101657 anchoring the sweet spot. Backwardation flip or front-tenor compression is the immediate stand-down.
Trading readSteep contango pays the carry trade and confirms no near-term event stress being priced - vol sellers get the slope, but any flattening in the 9D-to-3M section is the first sign the trade has to come off.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM implied at 12.15% pays only a thin cushion over trailing realized at 11.03, with 5-session realized at 8.45 confirming the tape has already decelerated. The IV/RV spread reads Thin Premium - enough carry to justify defined-risk shorts on the index leg, but not enough to naked-sell aggregate vol without a wing bias.
The premium sits offshore of SPY. IWM VRP at 5.97% against SPY VRP at 1.12% is a rare small-cap-rich spread, and it's the single reason the ScenarioEV engine tilts the recommended Iron Condor toward IWM wings at 30-45 DTE. Rank structured shorts by index-specific VRP, not aggregate - that's where the mispricing lives.
Supporting the carry: HV60 at 11.17 sits above HV20 at 11.03, so realized is decelerating into the print - a friendly backdrop for short-vol structures as long as MOVE doesn't force equity vol to catch up.
What it means for your trading
Sell IWM vol over SPY: small-cap VRP at 5.97% is where the premium concentrates while SPY at 1.12% offers only a Thin Premium. Decelerating realized supports the carry, but rank by index-specific VRP, not the aggregate read.
Skew Convexity
SPY quarter-delta put IV at 14.56% prices a clean premium over ATM at 13.38%, printing a downside skew of 1.55%. Smile ratio at 1.12% tells the real story - demand for downside is ordered, not panicked. This is protection buying by the book, not tail chasing, and it's the signature of a market pricing risk without capitulating to it.
Quarter-delta call IV at 13.01% sits flat to ATM - no upside conviction being paid for anywhere on the surface. Combined with the section signal at Yellow, the geometry favors spreading the protection: put debit verticals capture the skew premium sold to you by the wing bid, while naked long puts overpay for convexity that isn't accelerating. Ratio structures also work here - sell the fat wing, own the ATM.
Bottom line: skew is bid enough to reward sellers of the wing, tame enough that convexity chasers get bled by theta. Spread the protection, don't buy it outright.
What it means for your trading
Ordered put skew at 1.55% with a smile ratio of 1.12% signals structured hedging demand, not tail panic - vertical put spreads dominate naked wings while flat call skew rules out upside convexity trades.
Vol-of-Vol Structure
VVIX at 90.06 against VIX 16.02 puts the vol-of-vol ratio at 5.62 - elevated relative to a quiet-tape baseline but nowhere near the panic band. The level classifies as Normal, and the sizing rulebook holds at Standard Size. Jump risk is priced, not screaming.
Translation for the desk: run the Iron Condor at 30-45 DTE at book size, no forced haircut. Signal color Green means tail hedges stay cheap-and-cheerful - long-dated wings and defined-risk collars - not weaponized convexity. Buying VVIX up here pays for a move that isn't in the tape yet.
The line to watch is a VVIX push through the triple-digit handle with VIX at 16.02 refusing to follow. That divergence is the binary-outcome tell - the market pricing gamma without spot vol - and it collapses the carry trade before the term structure even flinches. Until then, standard size, structured shorts, IWM wing bias intact.
What it means for your trading
Vol-of-vol sits at Normal with ratio 5.62 - run Standard Size on structured shorts and keep tail hedges defined-risk. A VVIX breakout with VIX flat is the single condition that flips this from carry-friendly to stand-down.
Dispersion Spread
Dispersion signal reads Moderate with index correlations elevated enough to keep spread trades cautious - the gamma concentration cluster in META, NVDA, and MSFT is doing the structural work, which means index vol is systematically underpricing single-name idiosyncratic risk.
SPY ATM IV at 12.15% anchors the index leg while cross-strike dispersion runs 57.63 against cross-expiry at 2.54 - the smile is where the reprice lives, not the term. Single-name earnings tape is where dispersion actually pays, but with mega-cap gamma this concentrated, the correlation floor is too high to run classic short-correlation books cleanly.
Preferred expression: sell SPX/SPY vol over single-name exposure rather than hedging index shorts with QQQ. The mega-cap cluster keeps QQQ artificially tethered, and idiosyncratic tape in META or NVDA blows up dispersion books before the correlation trade converges.
What it means for your trading
Dispersion at Moderate with mega-cap gamma concentrating in META/NVDA/MSFT - sell index vol over single-name, don't hedge with QQQ.
Liquidity & Microstructure
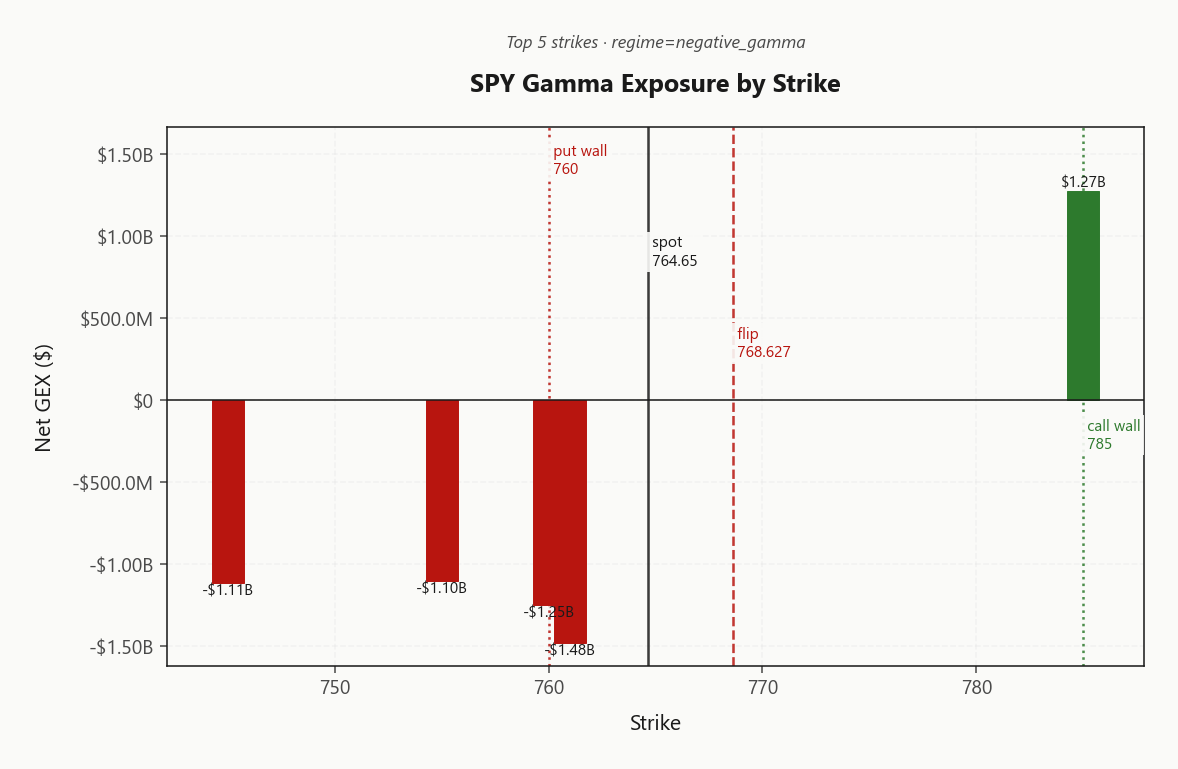
The order book anchors below spot with the gamma flip at 768.63 sitting immediately overhead of 764.65 - that single level is tomorrow's regime switch. Reclaim it and dealer flow flips from selling rallies to buying dips; fail it and the destabilizing bias carries into the next session.
OI concentrates around the 700 magnet with the call wall pinned at 785.00 and the put wall at 760.00, framing a wide but well-defined corridor. The dominant strike-level pull sits at 761.00 carrying net GEX -$1.48B - that's the magnet doing the real work, and it's exactly where charm and vanna reinforce the pin.
Trade the regime, not the strike: below the flip, expect trend continuation on breaks and gap-and-go behavior into levels; above it, mean-reversion returns and dealer flow damps the tape.
What it means for your trading
The gamma flip at 768.63 is the only level that matters into tomorrow's open - reclaim flips dealer flow supportive, failure keeps the destabilizing bias intact around the 761.00 magnet.
Trading readDeep negative-gamma cluster below spot with the flip level immediately overhead - dealers sell into weakness under the flip and buy dips above it, so tomorrow's key line is a single reclaim, not a range.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer second-order Greeks are the highest-conviction risk flag on the page. Net VEX at -$78.05B means any vol spike forces dealers to hedge by selling delta into weakness - the classic negative-vanna feedback loop that turns a routine repricing into a trend day. Net CHEX at -$1.2M confirms the charm bleed: Time decay pushing dealers to sell - pressure into close.
The single number that flips the whole complex is the charm pivot at 768.6269976231, sitting 0.5201069278 above spot. Bias currently reads Destabilizing - dealer flow amplifies weakness under it, dampens it above. Reclaim the pivot and the regime rotates; fail it and the vanna/charm stack keeps pressing.
Section signal Red. Keep structured shorts defined-risk, size wings against the pivot, and treat any MOVE-led vol expansion as the trigger that activates the negative-vanna cascade.
What it means for your trading
Vanna and charm are pulling the same destabilizing direction below the pivot at 768.6269976231, so a vol spike here is amplified - not absorbed - by dealer hedging. Trade defined-risk, and treat a reclaim of the pivot as the single regime-change trigger for the whole book.
Cross-Asset Confirmation
Bond vol is doing the talking today. MOVE ripped to 106.60, up 4.69%%, while VIX at 16.02 drifted lower into the close - a textbook bond-vol-leads-equity-vol divergence that historically resolves with the equity complex catching up, not the other way around. Fear & Greed printed 32 in Fear despite a suppressed VIX tape, confirming defensive positioning is running under the calm surface.
The cap divergence stays live: QQQ at 738.32 holds up on mega-cap gamma concentration while IWM at 279.12 trades the fragile leg, with the SPY/QQQ regime split registering True. QQQ is the only stable pillar - a crack in the top-mover gamma cluster and the whole divergence closes fast.
This is not a credit shock - it's geopolitical/rate-driven, and mean-reversion still owns the base case. Cut risk on a MOVE breakout above the 110 handle; that's where cross-asset stress converts to equity vol.
What it means for your trading
MOVE at 106.60 leading a suppressed VIX at 16.02, with F&G stuck in Fear, is the tell that positioning is defensive even as the tape looks calm. Stay long the carry trade while QQQ holds, but the mega-cap gamma cluster is the single point of failure for the whole cross-asset picture.
Scenario EV
The ScenarioEV engine ranks Iron Condor at score 40 against put spread 27 - a decisive gap driven by Steep Contango carry, VVIX parked at 90.06 in the normal band, and IWM VRP dominance. The structure trades against index mean-reversion in Negative Gamma while keeping wings defined, which is the right shape when charm sits Destabilizing and MOVE at 106.60 is the day's lead risk.
Optimal DTE lands in the 30-45 bucket, where forward 30→60 at 19.0715101657 pays the richest carry-to-realized ratio without stretching into event-heavy tenors. VRP assessment reads Unknown at the aggregate line, but that masks the trade: IWM VRP at 5.97% versus SPY at 1.12% is where the premium actually lives, so wings tilt IWM-weighted with SPY as the anchor leg.
Stand down if SPY reclaims 768.6269976231 - the regime flip kills the short-vol edge - or if VVIX pushes through the jump-risk threshold and forces sizing down.
What it means for your trading
Iron Condor at 30-45 DTE with IWM wing bias is the highest-EV structure while contango holds and VVIX stays normal. Cut the trade on a gamma-flip reclaim at 768.6269976231 or a MOVE breakout.
Actionable Summary
Bottom line: run Iron Condor at 30-45 DTE with IWM wing bias - IWM VRP at 5.97% vs SPY 1.12% is where the premium lives, and the contango carry through 14.26 to 20.23 pays the trade while VVIX at 90.06 keeps sizing standard.
Watch the gamma flip at 768.6269976231 as the single regime-change trigger - SPY closed Destabilizing below it, so a reclaim flips dealer flow from sell-into-weakness to buy-the-dip. Avoid naked long vol, single-name dispersion shorts, and any chase above 785.00.
Stand down if MOVE breaks through structural resistance or VVIX pushes through the elevated band - either kills the carry. Regime reads Elevated / Watchful with a 15-session half-life: sticky enough to run, fragile enough to respect.
Iran sanctions expansion keeps geopolitical tail risk live and directly feeds the MOVE-index divergence - bond vol reacts to policy risk while equity vol shrugs, which is exactly the pattern in today's tape.
Prediction-market NFP whisper above consensus sets up a rate-vol event risk for the Friday print - the term structure's forward 30→60 kink is already pricing part of this, and a hot number reprices the whole VIX complex.
SPR oil-loan drawdown pressures the crude-vol/bond-vol linkage - energy is the underappreciated transmission channel for MOVE breakouts, and this is a supply-side tell that matters for the cross-asset read.
AI layoff wave commentary from Raimondo touches the mega-cap concentration story directly - if the narrative shifts on AI capex, the top-mover gamma cluster (META, NVDA, MSFT) unwinds and QQQ regime stability breaks.
Bond-vs-stock diversification opportunity call lands on the same day MOVE reaccelerates - reinforces that fixed-income vol is where the marginal reprice is happening, and validates the cross-asset lead-indicator thesis.
Anthropic IPO filing and OpenAI safety-driven model pull are the AI-capex tail risks that would break the mega-cap gamma cluster - watch for follow-through in dispersion signals if the AI narrative starts to wobble.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.03 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.63 against a spot of 764.65. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.15% with a volatility risk premium of 1.12%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.02. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime