Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 767.60 sits just under the gamma flip 769.42 with net GEX -$4.23B - regime is Negative Gamma, meaning dealers amplify moves both ways until spot reclaims the flip. Call wall 785.00 caps the upside, put wall 765.00 is the first air-pocket if it breaks; max pain 770.00 sits between and acts as the magnet if we chop. Dealer positioning: net vex -$72.52B and charm $925.2K - vanna is destabilizing as vol rises, charm mildly supportive into close. Vol read: VIX 16.07 up 8%%, VIX9D 12.76 vs VIX3M 17.93 = steep contango, near-slope 25.55%% keeps VRP 1.06% live. Bottom line: fade rallies into 785.00, watch 765.00 as the pivot - iron condor in 30-45 DTE is the highest-scoring structure while VVIX stays in Normal range.
SPY at 767.60 trades just below the gamma flip at 769.42 with net GEX -$4.23B - dealers are short gamma and will amplify moves in either direction. VIX 16.07 in steep contango (Steep Contango) alongside softening MOVE 96.00 says the tape is pricing an equity-specific wobble, not a credit shock. Iron condor in the 30-45 window screens best while VVIX 92.03 stays in Normal territory.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
767.60
769.42
-0.24%
785
765
770
-$4.23B
Short gamma
QQQ
737.94
738.70
-0.10%
740
730
725
-$2.65B
Short gamma
IWM
280.10
291.73
-3.99%
285
280
285
-$4.63B
-
VIX
16.07
16.08
-0.05%
20
16
19
-$17.15M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.95
10.89
+1.06
1.94
2.00
1.38
QQQ
17.41
15.77
+1.64
1.84
1.40
1.28
IWM
18.28
12.31
+5.97
2.28
2.31
1.42
VIX
272.88
106.92
+165.96
-126.38
0.31
2.37
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
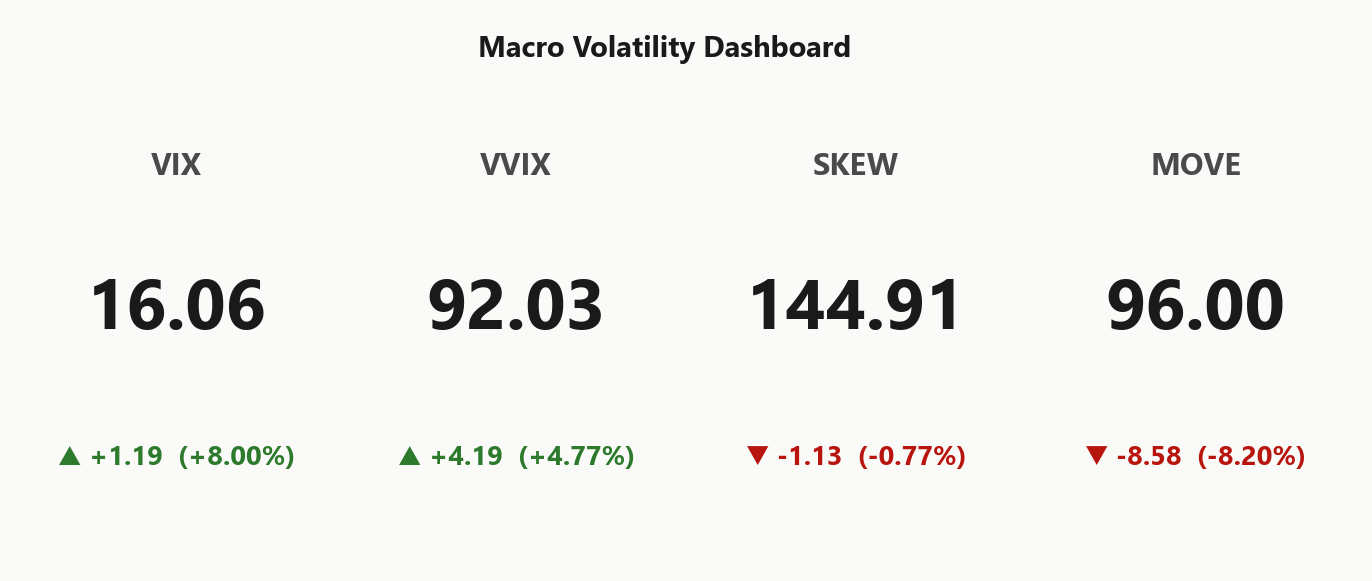
VIX
16.06
+8.00%
VVIX
92.03
+4.77%
SPX
7,702.57
-0.53%
SKEW index
144.91
-0.77%
MOVE (bond vol)
96.00
-8.20%
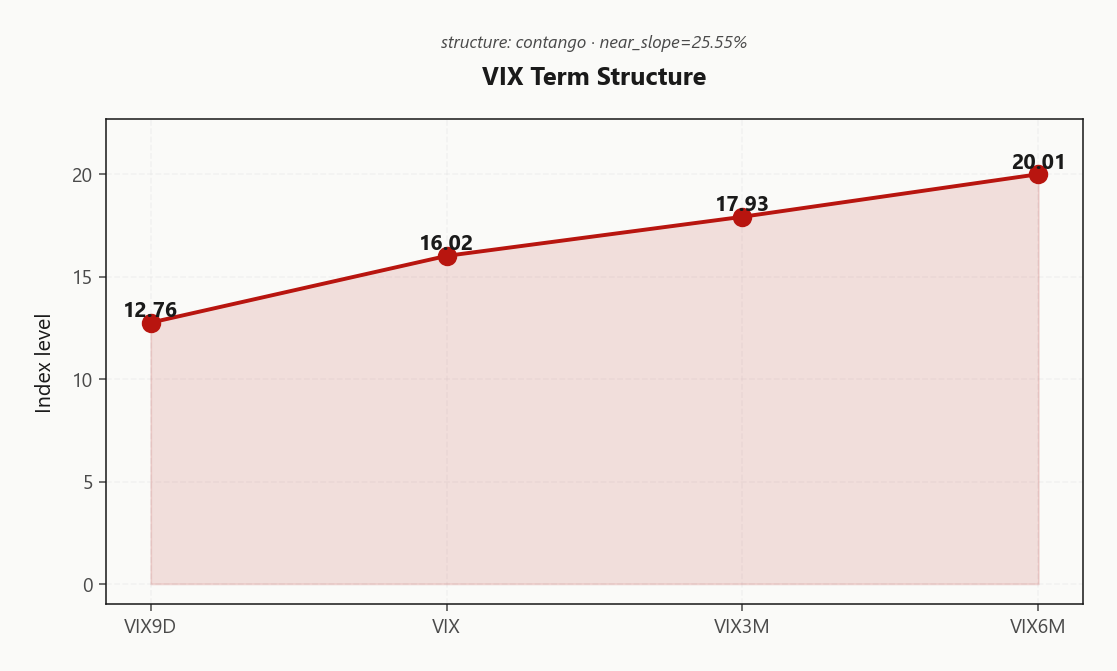
VIX term (9d/30d/3m/6m)
12.76 / 16.02 / 17.93 / 20.01
Steep contango
VVIX / VIX
5.73
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with the current state tagged Elevated and VIX at 16.06 - firmly above the calm-zone threshold but nowhere near a panic print. This is the sticky middle: not the environment to press directional risk, not the environment to abandon vol selling either.
Transition probabilities frame the tape cleanly. P(panic within five sessions) prints at 0.05 - low but not negligible, enough to keep tail hedges on. P(low regime within ten sessions) sits at 0.45, giving the mean-reversion case moderate odds. Half-life of 15 sessions confirms the operative expectation: this regime persists rather than resolves quickly.
Playbook flows from the half-life read - size for a regime that sticks, not one that snaps. Iron condor in 30-45 DTE remains the highest-scoring structure at Elevated / Watchful; escalation risk gets managed with wing overlays, not by de-grossing the carry trade.
What it means for your trading
Regime tags Elevated / Watchful at VIX 16.06 with a 15-session half-life - expect stickiness, size the carry trade for persistence, keep wings on for the low-probability escalation tail.
Trading readVIX firming, VVIX in normal, SKEW elevated, MOVE softening - the divergence signal is real: equity vol is playing catch-up while rate vol relaxes. Regime tilt is toward equity-specific rather than macro-wide.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is in Contango with VIX9D at 12.76 sitting well below spot VIX at 16.02 - the front-end kink is minor and the curve stays orderly, not stressed. VIX3M at 17.93 and VIX6M at 20.01 anchor the long end with no term-structure inversion signal, so the market is pricing near-term jump risk on the oil catalyst rather than sustained regime stress.
Near-slope of 25.55%% is steep enough to reward vol sellers with clean roll-down carry while imposing negative carry on hedgers. Forward 30-to-60 vol prints 18.8124200995, the structural sweet spot where roll-down is steepest and gamma least punishing.
Regime label Steep Contango - the geometry favors the vol seller, not the buyer. The 30-45 DTE bucket is where the carry lives.
What it means for your trading
Curve geometry is unambiguously seller-friendly - Steep Contango with a 25.55%% near-slope funds the iron-condor thesis in the 30-45 window. Roll positions past the front headline print to keep the roll-down working for you rather than against.
Trading readSteep contango, front-end sub-VIX, near-slope 25.55%% - vol carry trade rewarded, but the market is pricing near-term jump risk on the oil catalyst. Roll positions past the front headline window.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV at 11.95% prints a clean premium over trailing realized - HV20 at 10.89 and HV5 at 7.8 confirm the tape has actually delivered less than what the belly is charging. The gap isn't a broken regime signal; it's the oil-shock event premium being paid up front.
VRP at 1.06% is live but not extreme, and the IV-RV read comes in Thin Premium - sellers still get paid to underwrite, but the edge is being priced, not gifted. HV5 running below HV20 says realized is decelerating, not accelerating into the print - the amplification risk sits in dealer positioning, not in what the tape has actually done.
Cross-check across the complex: IWM VRP at 5.97% is the outlier - small-cap premium is the richest carry in the book, but respect the wider expected move. SPY remains the cleaner-carry vehicle for defined-risk premium collection while the belly stays this rich to trailing tape.
What it means for your trading
Options are rich to what the tape has actually delivered - VRP 1.06% and a Thin Premium IV-RV read say sellers are still paid, but the premium is compensation for oil-shock event risk, not a broken regime.
Skew Convexity
Put wing bids while calls stay flat - 14.51% on the 14.51% put quarter-delta versus 12.57% on the call side, anchored by ATM at 12.89%. The 1.94% quarter-delta skew reads steep but ordered; downside is bid because oil is bid, not because tails are being panic-hoarded.
Smile ratio at 1.15% confirms controlled convexity - no bimodal pricing, no barbell distortion. The call side going flat is the tell: flow has zero upside conviction into the 785.00 wall, and dealers aren't paying up for right-tail lottery tickets. Section signal Skew Steep - steep, not panicked.
Actionable read: put spreads dominate naked puts here. Wings are fairly priced, not overpaid, so financed downside beats the outright hedge. Combine with the iron condor in the 30-45 window - sell the flat call side, buy back the steep put wing as a spread. That is the skew geometry paying you today.
What it means for your trading
Skew is steep but ordered - put spreads over naked puts, and the flat call side is where the iron condor's short strike lives. No panic in the wings, only oil-catalyst downside being bid at 1.94%.
Vol-of-Vol Structure
VVIX prints 92.03 against VIX 16.06 - the ratio sits at 5.73, proportional and well below the extreme threshold. The tail is being priced calmly; there is no binary-outcome premium embedded in the vol-of-vol surface today.
Level flag reads Normal and sizing guidance holds at Standard Size - full clip on high-conviction structures, no defensive cut. VVIX is up 4.77% on the session but the absolute level stays in the calm zone, so the oil-catalyst pop hasn't tipped the regime into jump-risk pricing.
Trade implication: the vol-selling geometry is intact. Iron condor scoring at 42 in the 30-45 DTE window sizes normally here. Watch VVIX reclaiming the extreme threshold as the trigger to halve clip - until then, standard size is the correct book.
What it means for your trading
VVIX at 92.03 keeps vol-of-vol in Normal territory - size vol-selling structures at Standard Size and stay full clip until the ratio breaks proportionality.
Dispersion Spread
Index vol is not clearing single-name risk today. SPY ATM prints 11.95% against QQQ at 17.41% - the mega-cap complex is carrying a live premium the index tape isn't fully absorbing. IWM sits further out at 18.28%, layering a small-cap vol charge on top of the index-level read. Cross-strike dispersion at 67.32 and cross-expiry at 43.64 confirm the smile is doing real work.
Section signal reads Moderate - dispersion is live but not extreme, which is exactly the window where index vol selling gets paid without single-name shorts blowing up. Trade construction bias: sell SPX/SPY vol, avoid single-name short vol. NVDA and AAPL buyback flow plus tech mega-cap earnings gravity mean idiosyncratic upside vol won't be rescued by index softening - the wrong side of a dispersion trade this week is the short single-name leg.
What it means for your trading
Dispersion is Moderate with QQQ ATM 17.41% pricing above SPY 11.95% - sell index vol, keep single names off the short book.
Liquidity & Microstructure
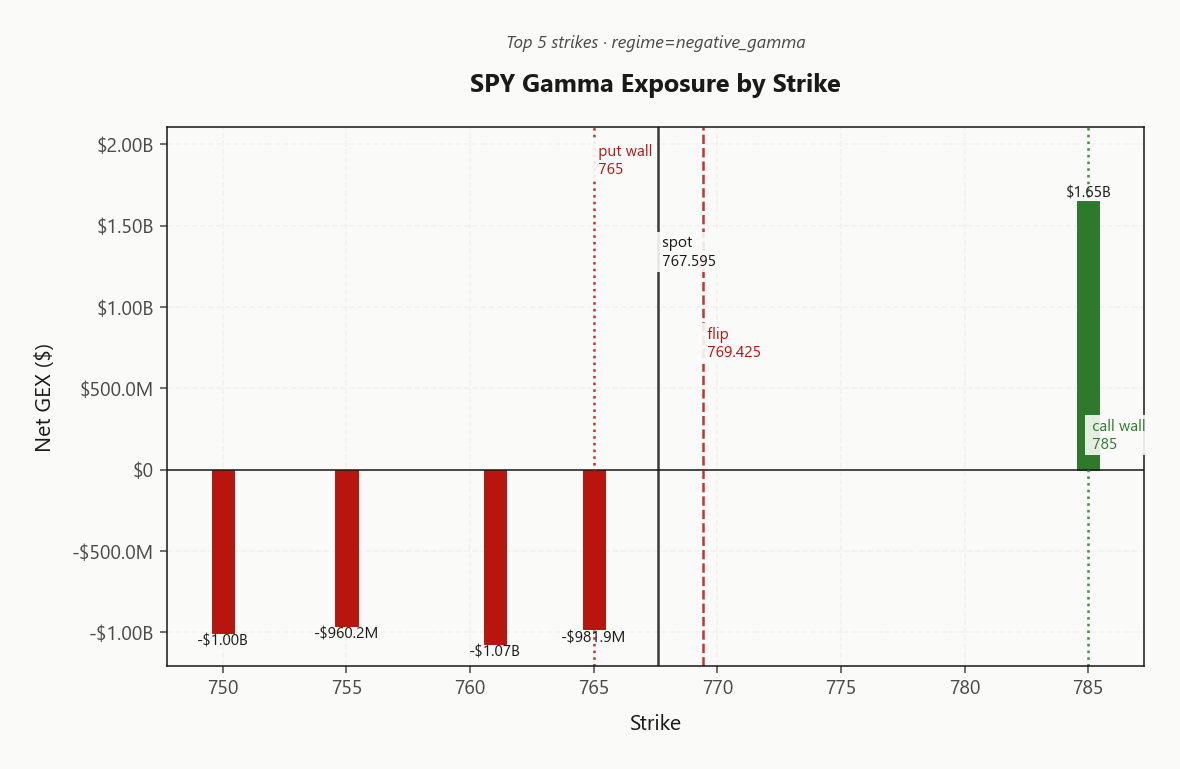
Open interest still clusters at 500 - a legacy structural anchor sitting well below spot and largely inert to today's tape. The live magnet is the gamma flip at 769.42, the single level that decides whether dealers dampen or amplify. Spot below it puts the book in Negative Gamma - sellers get chased down, buyers get chased up until the flip is reclaimed.
Between the walls, 785.00 caps rallies and 765.00 marks the first air-pocket on a break. The top strike at 785.00 carries net GEX of $1.65B - a heavy positive-gamma ceiling that reinforces the call wall as a genuine supply zone, not a cosmetic level.
Zero-DTE net GEX prints -$1.12B, or 26.5% of total - meaningful for intraday chop but not dominant. Real trend fuel still lives in longer-dated flow; the flip, not the 0DTE book, is what changes the regime.
What it means for your trading
Book is structurally deep but tactically pinned below the flip at 769.42 - reclaim it and dealer flow flips from accelerant to stabilizer; lose 765.00 and the air-pocket opens before the next OI shelf catches.
Trading readSpot sits below the gamma flip in a Negative Gamma regime - dealer flow amplifies moves both ways until spot reclaims 769.42. Fade rallies into the call wall, respect the put wall as the air-pocket line.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
The single pivot is the gamma flip at 769.4245106129 - current bias Destabilizing. Reclaim it and vanna flips from accelerant to stabilizer; hold below and every vol tick compounds the downside. That is the one number that swings the day's regime.
What it means for your trading
Vanna is destabilizing while spot trades under 769.4245106129; charm bid into the close only partially offsets the vex-driven accelerant. The pivot reclaim is the trigger - until then, size defined-risk and treat rallies as fadeable.
Cross-Asset Confirmation
MOVE at 96.00 is softer, not spiking - bond vol is relaxing while equity vol firms. That divergence is the tell: this is an equity-flavored oil-catalyst wobble, not a credit or rates shock. Rate desks aren't hedging a macro reset; the premium is being paid in equity land.
Fear-and-Greed prints 37 at Fear - defensive positioning, nowhere near capitulation. QQQ mid 737.94 and IWM mid 280.10 both sit under their flips alongside SPY; small caps carry the richest vol premium in the complex. Cross-asset tone reads Unknown with regime divergence Aligned - no dislocation to fade.
Read: mean-reversion stays the base case once the flip reclaims. Below it, respect the destabilizing bid without pricing in a broader risk-off.
What it means for your trading
Softer MOVE at 96.00 against firming equity vol and Fear sentiment says this is an equity-specific catalyst wobble, not a macro shock. Cross-asset regime is Aligned - no divergence to trade against.
Scenario EV
The Iron Condor screens as the highest-conviction structure at a composite score of 42, with steep contango (Steep Contango), a live VRP of 1.06%, ordered skew at 1.94%, and VVIX sitting in Normal range all pulling in the same direction. Sell the wings around 785.00 and 765.00 in the 30-45 DTE window, where roll-down carry is steepest and gamma least punishing on a spot excursion.
Put spread scores second at 29 and is the preferred overlay if the book is long delta — skew is bid but not panicked, so wing pricing is fair rather than overpaid. Calendars get skipped: the front-end kink exists but the curve is orderly enough that the edge is thin against a shock-to-realized risk. With VVIX in Normal territory, sizing guidance is Standard Size — no need to defensively cut clip until VVIX pushes through the elevated threshold.
What it means for your trading
Iron condor in 30-45 DTE with wings framed by 765.00 and 785.00 is the highest-scoring structure; put spread overlay is the hedge of choice if long delta.
Actionable Summary
Playbook: sell 30-45 DTE iron condor with wings anchored at the 785.00 call wall and 765.00 put wall - you collect VRP 1.06% against a Steep Contango curve, ordered skew at 1.94%, and VVIX in Normal territory at 92.03. Sizing guidance stays Standard Size while the vol-of-vol regime holds.
Hedge and avoid: overlay put spreads rather than naked wings - ordered convexity makes the tail fairly priced, not overpaid. Steer clear of short single-name vol into the mega-cap dispersion print and naked short puts while spot sits below the flip. The one number that flips the regime is the gamma pivot at 769.4245106129; reclaim it and dealer flow rotates from Destabilizing back to supportive, current bias reads Destabilizing.
Triggers to watch: a VIX print through the mid-teens or VVIX pressing toward the elevated threshold tips sizing to half-clip; regime label sits at Elevated / Watchful with a 15-session half-life, so the tape stays sticky rather than binary.
Gold down more than 2% on US rate-hike bets confirms the tape isn't reading this as broad risk-off - it's oil-plus-hawkish-Fed, not a flight to safety.
Post-Iran strategy rethink for oil majors is the sector rotation angle - energy trades on this narrative regardless of the intraday SPX print.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.07 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 769.42 against a spot of 767.60. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.95% with a volatility risk premium of 1.06%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.06. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime