Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
Negative-gamma across index complex with SPY pinned 0.1051201475 below flip, VIX contango intact
SPY at 768.59 is trading fractionally below the 769.40 flip, keeping dealers short gamma across the index complex while VIX 15.77 rises inside a still-contango term structure. Vol-of-vol at 5.69x stays contained, so the tape is jittery, not panicked. Best structure remains Iron Condor in the 30-45 DTE window with sizing at Standard Size.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
768.59
769.40
-0.11%
785
765
770
-$2.28B
Short gamma
QQQ
739.26
739.47
-0.03%
740
730
725
-$1.76B
Short gamma
IWM
281.08
292.96
-4.05%
285
280
285
-$4.27B
Short gamma
VIX
15.77
16.22
-2.79%
20
15
19
-$19.13M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
12.02
11.07
+0.95
1.30
2.00
1.19
QQQ
17.63
16.32
+1.31
0.83
1.40
1.15
IWM
18.11
12.56
+5.55
0.58
2.31
1.89
VIX
286.38
108.80
+177.58
-125.92
0.31
0.85
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.77
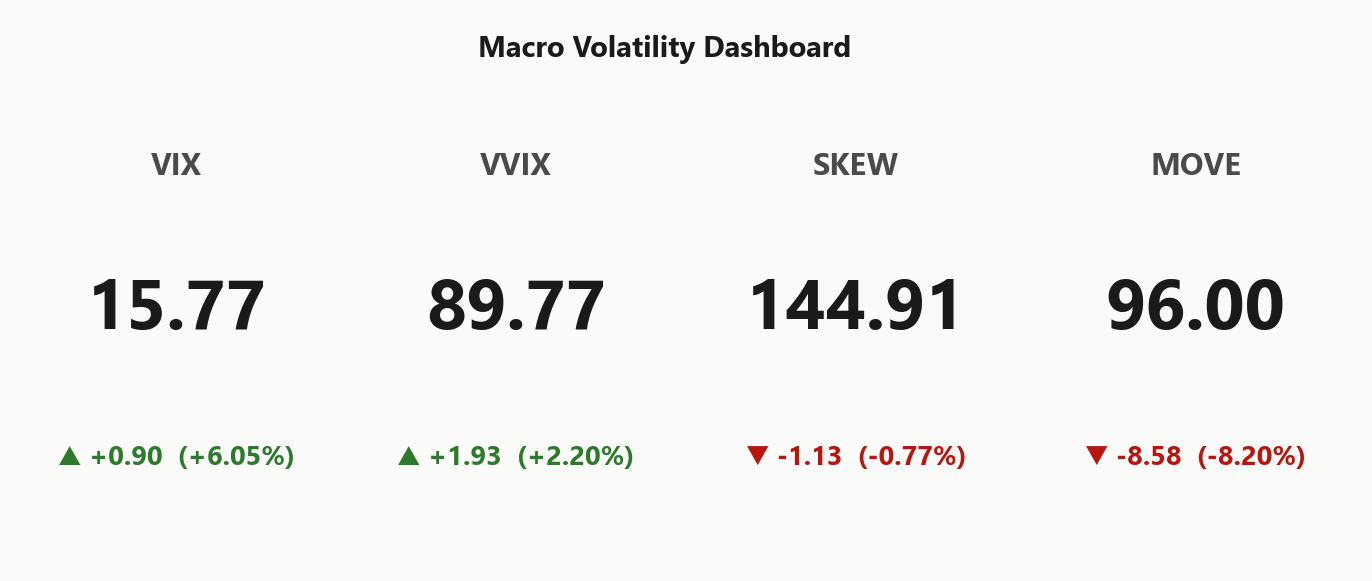
+6.05%
VVIX
89.77
+2.20%
SPX
7,716.66
-0.35%
SKEW index
144.91
-0.77%
MOVE (bond vol)
96.00
-8.20%
VIX term (9d/30d/3m/6m)
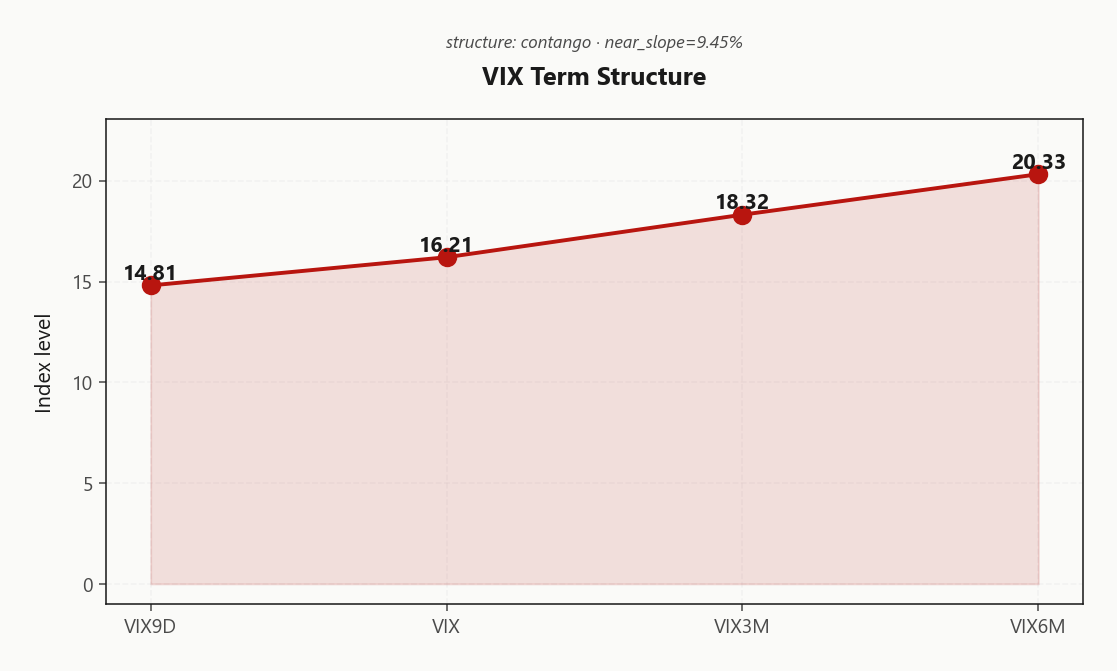
14.81 / 16.21 / 18.32 / 20.33
Steep contango
VVIX / VIX
5.69
Low
Regime
Elevated / Watchful
Regime Assessment
Regime tape reads Elevated / Watchful - the current print is Elevated with VIX anchored at 15.77. That is meaningful but not panic; the market is on watch, not on the mat.
Transition math backs the label. Probability of migrating to panic across the next five sessions sits at 0.05, while probability of decaying back to low over ten sessions runs at 0.45 - the base case is chop-and-drain, not escalation. VVIX/VIX at 5.69x keeps jump risk contained, so sizing stays at Standard Size.
Half-life is the punchline: 15 sessions. Regimes at this level are sticky - do not fade the state on day one. Size trades to hold through the window, not to flip on the first vol tick.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - trade for persistence, not reversal, and keep Standard Size sizing until VVIX/VIX rerates.
Trading readVIX up, VVIX contained, SKEW mid-range, MOVE falling - the four are not confirming a stress regime, so treat today's risk-off as headline-driven not structural.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints clean Contango with 14.81 anchoring the front, spot VIX at 16.21, 18.32 stacked above, and 20.33 completing the ladder - no event kink, no backwardated pocket forcing a defensive tilt. The near-slope reads 9.45%%, positive and orderly, which keeps structural carry live for vol sellers rolling down the curve.
Best edge sits in the 30-45 DTE window: roll-down is steepest there, and with vol-of-vol classified Low at a 5.69x ratio, mark-to-market drift on short-vol books stays contained. Front-week is too gamma-sensitive under the negative-gamma spot regime; past 45 DTE surrenders the carry.
What it means for your trading
Contango is intact and orderly with near-slope at 9.45%% - vol sellers keep structural carry, and the 30-45 DTE window is where the roll-down pays without over-exposing to front-end gamma.
Trading readContango with near-slope 9.45%% - vol carry is intact, market does not yet expect stress to spread out along the curve.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied is trading above trailing realized across the index complex, but the cushion is uneven. SPY ATM at 12.02% against HV20 11.07 and HV60 11.3 leaves VRP at 0.95% - sellers get paid, but thinly. QQQ carries a richer cushion at 1.31%, and IWM is the clear outlier with VRP at 5.55%.
The small-cap premium is pricing a vol expansion that has not printed in the tape. There is no realized acceleration on the majors to justify buying vol here, and nothing on IWM's realized track to back up the implied bid either. Options are not obviously cheap-to-recent-moves anywhere in the complex.
Preferred routing: harvest premium via defined-risk on IWM first, where the cushion is fattest, before reaching for naked strangles on SPY or QQQ where the paid-to-wait is thin.
What it means for your trading
IWM's VRP at 5.55% is the fat pitch versus SPY's thin 0.95% - tilt short-vol flow toward small caps with defined-risk structures rather than chase naked index premium.
Skew Convexity
SPY quarter-delta skew at 1.3% with a smile ratio of 1.09% prints as ordered downside demand - puts bid over calls, but nothing that looks like a tail grab. Put-25d IV runs 15.37% against ATM 14.39% and call-25d 14.07%; the right wing is essentially flat to ATM, so upside conviction is absent from the surface even as spot chops beneath the flip.
IWM tells the same story with less drama - quarter-delta skew at 0.58% is flatter still, single-name vol priced for symmetry rather than crash. That combination - orderly put bid, flat call wing, small-cap surface even more balanced - argues against paying up for naked wings when the same downside can be financed inside a put spread and the same upside expressed through call spreads rather than outright calls.
Trade the structure the surface hands you: defined-risk downside via Iron Condor in the 30-45 DTE window captures the ordered skew without overpaying the tail that isn't bid.
What it means for your trading
Skew is bid but not panicked - put spreads price cheaper than the tape's mood suggests, and the flat call wing removes any reason to chase upside with naked premium.
Vol-of-Vol Structure
VVIX prints 89.77 against a VIX of 15.77, a ratio of 5.69x that classifies as Low. Jump-risk premium is contained, the wing on vol itself is not being lifted, and no bimodal outcome is being priced into the front. The tape is jittery on spot but the vol surface is not braced for a discontinuity.
Sizing guidance reads Standard Size - no reason to trim gross for jump risk here. Short-vol structures in the 30-45 DTE window can run at full clip; the vol-of-vol tax that would force a half-size stance is simply not being charged.
Trigger to flip the posture: a VVIX print through 100 with VIX unchanged. That divergence flags a jump-risk regime shift before it shows up in spot vol, and is the cleanest early tell to cut gross ahead of the move. Until then, the vol-of-vol channel is green and premium harvest keeps its edge.
What it means for your trading
With VVIX at 89.77 and the VVIX/VIX ratio at 5.69x (Low), the jump-risk tax is off - carry Standard Size in the 30-45 DTE window and only halve if VVIX clears 100 with VIX flat.
Dispersion Spread
Index-level vol sits notably below the single-name complex: SPY ATM prints 12.02% against QQQ at 17.63% and IWM at 18.11%. The spread argues that idiosyncratic risk is being priced into names while the index basket digests it through correlation compression - a classic dispersion setup where the whole trades tighter than the sum of its parts.
Implied correlation embedded in that gap keeps index puts a poor hedge for single-name exposure: shorting SPX/SPY vol against long single names bleeds carry without capturing the actual risk being priced. VRP tells the same story from the other side - SPY at 0.95% is thin, IWM at 5.55% is the fat pitch, with QQQ at 1.31% in between.
Routing: keep short-vol expressions on SPX/SPY where correlation carry works for you, and avoid the reflex of over-hedging single-name books with index puts - the geometry does not pay. Dispersion-flavored trades belong in the 30-45 DTE window alongside the Iron Condor.
What it means for your trading
Index IV at 12.02% running well under QQQ 17.63% and IWM 18.11% signals a dispersion regime where single-name risk is priced but not confirmed in realized. Sell vol at the index level, hedge names with names.
Liquidity & Microstructure
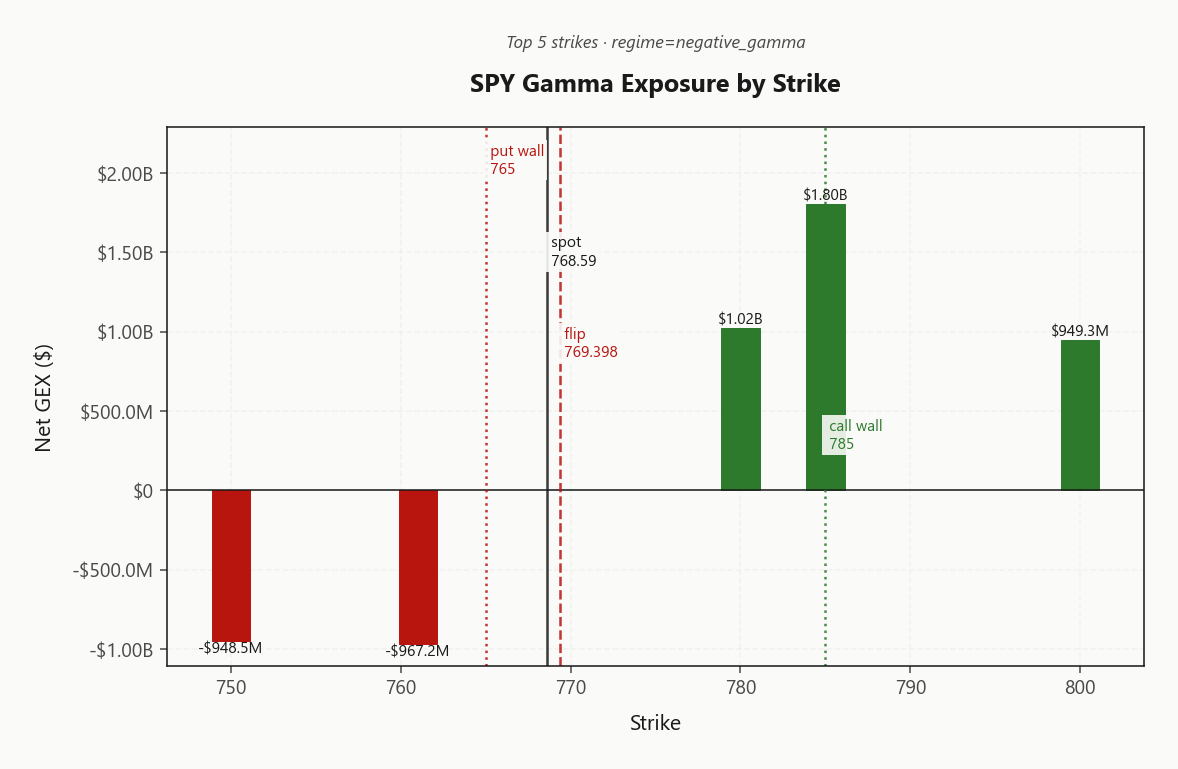
SPY's open-interest mass anchors at 500, but the live gamma battle is being fought in a tighter corridor bounded by the 765.00 put wall and the 785.00 call wall. The flip level at 769.40 is the single line that decides whether dealer flow adds fuel to moves or drains it - and spot at 768.59 is sitting inches below it.
The heaviest strike carries net GEX of $1.8B at 785.00, a magnet for pin action if spot reclaims the flip. Until then, Negative Gamma mechanics dominate: each dip forces dealer selling, each pop forces dealer buying, and the tape chops inside the corridor rather than trending through it.
Trade the range: fade extensions into 785.00 and 765.00, and treat a decisive reclaim of 769.40 as the flip-the-book signal that shifts dealer flow from destabilizing to supportive.
What it means for your trading
Spot sitting fractionally below 769.40 keeps dealer flow amplifying dips inside the 765.00 - 785.00 corridor; a clean reclaim flips the mechanics and rerates the book.
Trading readGamma clusters between the 765.00 put wall and 785.00 call wall with the flip perched at 769.40 - below is amplifier territory, above the tape gets its dealer bid back.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX prints -$84.07B - deeply negative, and that is the setup that matters. Any tick higher in vol forces dealers to sell delta into weakness; a tick lower buys strength back. Vanna is not neutral machinery today, it is an amplifier wired into the tape, and it fires hardest exactly where spot already sits.
Charm runs the other way. Net CHEX at $2.6M is positive, which pushes a mechanical buy bid into the close as time decay pulls short-dated deltas toward zero. Read it as an offset, not a cure - enough to blunt afternoon drift, not enough to override a vanna-driven flush if vol pops before the bell.
The pivot sits at 769.3979429414, with current bias flagged Destabilizing. Below that line dealer flow adds fuel to whichever direction the tape picks; a clean reclaim flips the same machinery supportive and shortens the leash on any downside extension. Trade the pivot, not the print.
What it means for your trading
Vanna is destabilizing at -$84.07B while charm at $2.6M quietly leans supportive into the close - the tug-of-war resolves at the 769.3979429414 pivot, which is the single level to trade around.
Cross-Asset Confirmation
MOVE prints 96.00, off -8.2%% on the session - rates vol is calming while equity vol ticks up, a signature that says headline shock, not credit event. If the Iran-oil bid were leaking into the funding stack, MOVE would be climbing with VIX; it isn't. Treat today's risk-off as isolated to equity beta and size the book accordingly.
Fear & Greed sits at 35 reading Fear - sentiment is lagging the geopolitical tape rather than leading it, and cross-asset regime reads Aligned across the index complex. No contrarian extreme yet, no divergence to fade; the tell is the alignment itself.
QQQ at 739.26 versus IWM at 281.08 - small caps carry the heavier vol premium (IWM VRP 5.55% vs SPY 0.95%). If credit joins the party via a MOVE turn higher, the IWM tail bid prints first - watch it as the leading indicator for a regime step-change.
What it means for your trading
Cross-asset tape confirms equity-only risk-off: MOVE at 96.00 down -8.2%% while VIX climbs, with Fear & Greed at Fear lagging the headline flow. IWM at 281.08 carries the fattest vol premium - a MOVE reversal higher is the first signal the shock is spreading beyond equities.
Scenario EV
The scorecard hands the session to Iron Condor at score 39, comfortably ahead of the put-spread read at 25. With SPY pinned below the 769.40 flip and VIX inside a Contango curve, there is no directional edge worth paying for over two-sided premium capture.
The DTE sweet spot is 30-45. Anything shorter runs into the Negative Gamma gamma amplifier, where dealer flow whipsaws the front book; anything past forty-five surrenders the contango roll-down that makes the trade pay in the first place. Vol-of-vol at 5.69x reads Low, so mark-to-market drift stays contained and sizing holds at Standard Size.
Route wings around the 765.00 to 785.00 corridor and let charm carry the book into the close. Reclaim of 769.3979429414 is the flip-the-bias trigger.
Bottom line: sell premium in a defined-risk Iron Condor inside the 765.00 - 785.00 corridor and let the flip at 769.3979429414 decide when to flip the book. With spot pinned below the pivot in Negative Gamma territory and vol-of-vol contained at 5.69x, defined-risk theta beats naked exposure on both wings.
Structure:Iron Condor in the 30-45 DTE window at standard size - the contango carry and Steep Contango curve favor the roll-down. Avoid: chasing upside into the 785.00 call wall and naked put shorts below 765.00 while the regime reads Elevated / Watchful. Watch: a clean reclaim of 769.3979429414 rotates dealer flow from destabilizing to supportive and re-rates room to add short vol.
Tail: a VVIX print above the century mark with VIX unchanged flags a jump-risk regime shift - cut size before it prints in vol itself. Until then, fade extensions inside the corridor and let theta do the work.
What it means for your trading
Sell defined-risk Iron Condor in the 30-45 DTE window between 765.00 and 785.00; a reclaim of 769.3979429414 is the trigger to add, a VVIX-led jump signal is the trigger to cut.
Nvidia buyback headline and its AI-safety talking point are the single biggest positioning signal for the tape today - mega-cap gamma and QQQ tone hinge on how the flow lands.
Direct US-Iran talks via mediators are the next binary event for the oil-and-risk trade - a positive readout can compress the vol bid, a walkout re-prices tails.
UK diesel prints a record on Iran-war impact - the first hard-data signal that geopolitical vol is bleeding into consumer prices, feeds back into rate-path uncertainty.
Wall St slipping as oil spikes on the rejected Iran peace proposal is the cleanest cause-and-effect narrative for today's risk-off - explains why VIX is bid without MOVE joining.
Cramer flagging relentless bond-yield climb and the Nvidia buyback captures the two dominant flows: rates pressure at the top of the cap stack and mega-cap self-bid underneath.
Indian equity selloff on the US-Iran deadlock confirms the risk-off is not US-idiosyncratic - global equity beta is priced in and any resolution unwinds broadly.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.77 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 769.40 against a spot of 768.59. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 12.02% with a volatility risk premium of 0.95%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.77. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime