Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 765.35 sits just below the gamma flip at 768.84 with net GEX at -$5.95B - dealers are short gamma and every tick gets amplified. Key levels: call wall at 785.00, put wall at 761.00, max pain at 770.00; a reclaim of the flip flips dealer flow from destabilizing to supportive. Dealer positioning is hostile - net VEX at -$61.42B means a vol spike forces further delta-selling, and charm at -$616.2K is bleeding hedges into close. Vol read: VIX at 16.19 up 8.88%%, term structure Contango at slope 10.96%%, VRP at 0.89% keeps sellers paid but VVIX/VIX ratio at 5.64 is only Normal. Bottom line: sell 30-45 DTE iron condors framed inside 761.00/785.00 walls at standard size; flip aggressive short-vol on a clean reclaim of 768.84.
SPY negative gamma below flip at 768.84; VIX contango, iron condor 30-45 DTE optimal.
SPY at 765.35 sits below the gamma flip at 768.84, keeping dealers short gamma and amplifying tape moves into the 785.00 call wall and 761.00 put wall. VIX at 16.19 with steep contango and VVIX at 91.34 keeps carry alive, but the SPY/QQQ regime divergence (True) says index dispersion is doing the work today. Iron condor 30-45 DTE remains the highest-scoring structure at 40.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
765.35
768.84
-0.45%
785
761
770
-$5.95B
Short gamma
QQQ
736.44
737.57
-0.15%
760
730
725
-$1.12B
-
IWM
280.10
290.76
-3.67%
285
280
285
-$4.44B
Short gamma
VIX
16.07
16.08
-0.04%
20
16
19
-$14.74M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.96
11.07
+0.89
1.39
2.00
1.12
QQQ
17.41
16.04
+1.37
2.75
1.40
1.11
IWM
18.42
12.28
+6.14
1.13
2.31
1.55
VIX
274.94
106.75
+168.19
-119.50
0.31
0.53
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
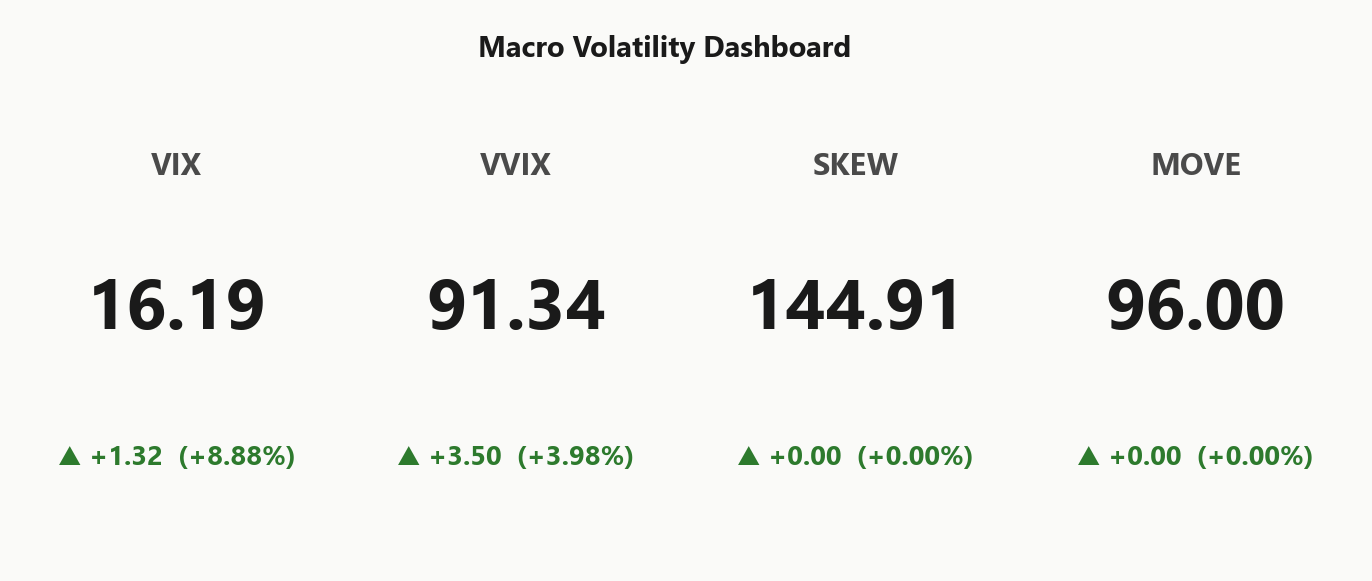
VIX
16.19
+8.88%
VVIX
91.34
+3.98%
SPX
7,683.69
-0.77%
SKEW index
144.91
0.00%
MOVE (bond vol)
96.00
0.00%
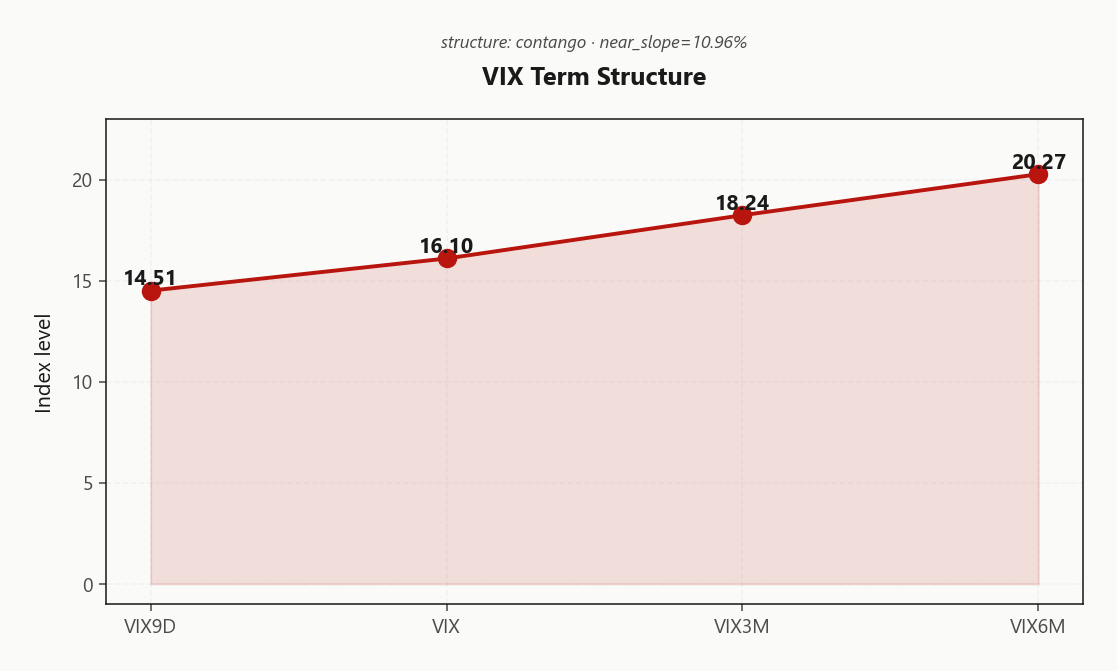
VIX term (9d/30d/3m/6m)
14.51 / 16.10 / 18.24 / 20.27
Steep contango
VVIX / VIX
5.64
Normal
Regime
Elevated / Watchful
Regime Assessment
Vol regime prints Elevated / Watchful with VIX at 16.19 - elevated enough to keep hedgers engaged, nowhere near panic. The transition matrix says 0.05 odds of a slide into panic across five sessions versus 0.45 odds of mean-reverting into a low-vol state over ten. Skew of outcomes favors compression, not escalation.
Half-life sits at 15 sessions, so the current condition is sticky - this is a watch-mode tape, not a transitional one. Structural carry stays alive under this label, and iron condors in the 30-45 DTE window are the regime's native trade.
Dealer flow at the microstructure level tells the tactical story - Destabilizing below the flip at 768.8413317428 - but the regime signal itself is a green light for premium sellers who frame risk inside 761.00/785.00.
What it means for your trading
Regime labelled Elevated / Watchful with sticky 15-session half-life and mean-reversion odds at 0.45 - size condors normally, do not chase long vol.
Trading readVIX and VVIX both up while MOVE stays calm and SKEW elevated - equity-vol concern without bond-vol confirmation is the classic dispersion signal, not a systemic warning.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward geometry stays convex: the 30-to-60 forward prints 19.2208584616 and the 60-to-90 extends to 22.1144342003. No event premium is pinned into the four-week window - the curve accretes smoothly rather than stepping around a known catalyst, which is the cleanest possible setup for calendar shorts.
Best edge sits in 30-45 DTE, where roll-down compounds without paying for tail insurance the term structure isn't demanding.
What it means for your trading
Steep contango with a 13.29% front-month basis and convex forwards through 22.1144342003 - sell 30-45 DTE structures where roll-down does the work.
Trading readSteep contango into 6-month says the vol-carry trade is intact and the market is not pricing a stress event - sellers of front-month vol collect roll-down; hedgers should extend duration on any tail protection.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.96% barely clears trailing realized at 11.07, leaving VRP at 0.89% - positive, but too thin to underwrite standalone index short-vol size. Implied is tracking realized almost tick-for-tick; the premium cushion that usually pays condor writers has been squeezed out of the front-month index tape.
The real premium lives down the cap curve. IWM VRP prints 6.14% against realized at 12.28 - small-cap options are richly bid relative to what the tape has actually delivered, a direct read on idiosyncratic dispersion and the Negative Gamma gamma backdrop. QQQ sits in the middle at 1.37% VRP with ATM IV 17.41%, moderate carry for tech dispersion into the Contango curve.
Route short-vol capital where premium is fattest: IWM condors carry the trade, QQQ works as a secondary vehicle, and SPY gets used for hedging rather than harvesting. The dispersion is doing the work - take it where it's paid.
What it means for your trading
SPY VRP at 0.89% is too thin to size into; IWM at 6.14% and QQQ at 1.37% are where the premium actually lives. Concentrate iron-condor risk in small-caps and tech, keep SPY for hedging.
Skew Convexity
SPY quarter-delta skew prints 1.39% vol points with the put wing at 13.63% against the call wing at 12.24% around an ATM of 12.75% - an ordered downside bid, not a panic. The smile ratio at 1.11% confirms the wing is bid but tail convexity stays contained, which keeps put-spread structures cheaper than naked puts on the index.
Across the complex, QQQ skew at 2.75% is the steepest - tech-tail hedges being bid harder as single-name dispersion pushes through the index - while IWM skew sits flat at 1.13%, small-cap put wing already saturated from prior stress. That is dispersion pressure, not systemic fear.
Trade the geometry: prefer put-spread protection over naked long puts where skew is steepest (QQQ first, SPY second), and monetize the flat IWM wing by selling put spreads rather than paying up for outright downside there.
What it means for your trading
Skew geometry reads ordered rather than panicked - QQQ carries the steepest tail bid at 2.75%, SPY smile ratio at 1.11% stays contained, and IWM at 1.13% is saturated. Route hedges as put spreads on QQQ/SPY and harvest the flat IWM wing rather than paying naked premium.
Vol-of-Vol Structure
VVIX at 91.34 against VIX at 16.19 puts the ratio at 5.64 - squarely in Normal territory. There is no bimodal jump premium being priced into VIX options; the vol-of-vol surface is behaving, and sellers get Standard Size clearance without the half-size penalty a stressed VVIX regime would impose.
That said, VVIX did pop 3.98%% intraday alongside VIX up 8.88%% - not enough to flip the regime, but enough to warrant a cheap far-OTM VIX-call overlay against the short-vol book. Watch the 100 handle on VVIX as the tripwire: a break above shifts sizing down and re-prices tail hedges.
Net: harvest premium at full size in 30-45 DTE condors - the vol-of-vol read is a green light, not an all-clear.
What it means for your trading
VVIX/VIX at 5.64 keeps the regime Normal - size condors normally, but overlay a cheap VIX-call tail given the intraday 3.98%% VVIX bump.
Dispersion Spread
Index-vs-single-name dispersion is wide. SPY ATM IV at 11.96% prints the lowest in the complex, while QQQ carries 17.41% and IWM sits richest at 18.42%. Index correlation is compressed even as small-cap and tech names bid on idiosyncratic risk - the classic dispersion tell.
The routing follows the pricing: SPY is the cheapest hedge in the book, not the richest premium. IWM VRP at 6.14% against SPY's thin 0.89% confirms the premium lives away from the index. QQQ dispersion at 17.41% reflects tech single-name convexity being bid harder than the ETF wrapper.
Prefer SPY/SPX short-vol as the harvest leg - carry is thinner but the wing is cleaner and dealer flow is deeper. Hedge single-name earners individually rather than layering broad index puts; blanket index protection over-pays for correlation that isn't there.
What it means for your trading
Wide index-vs-single-name dispersion with SPY at 11.96%, QQQ at 17.41%, IWM at 18.42% - sell index vol, harvest single-name premium separately, hedge earners one by one.
Liquidity & Microstructure
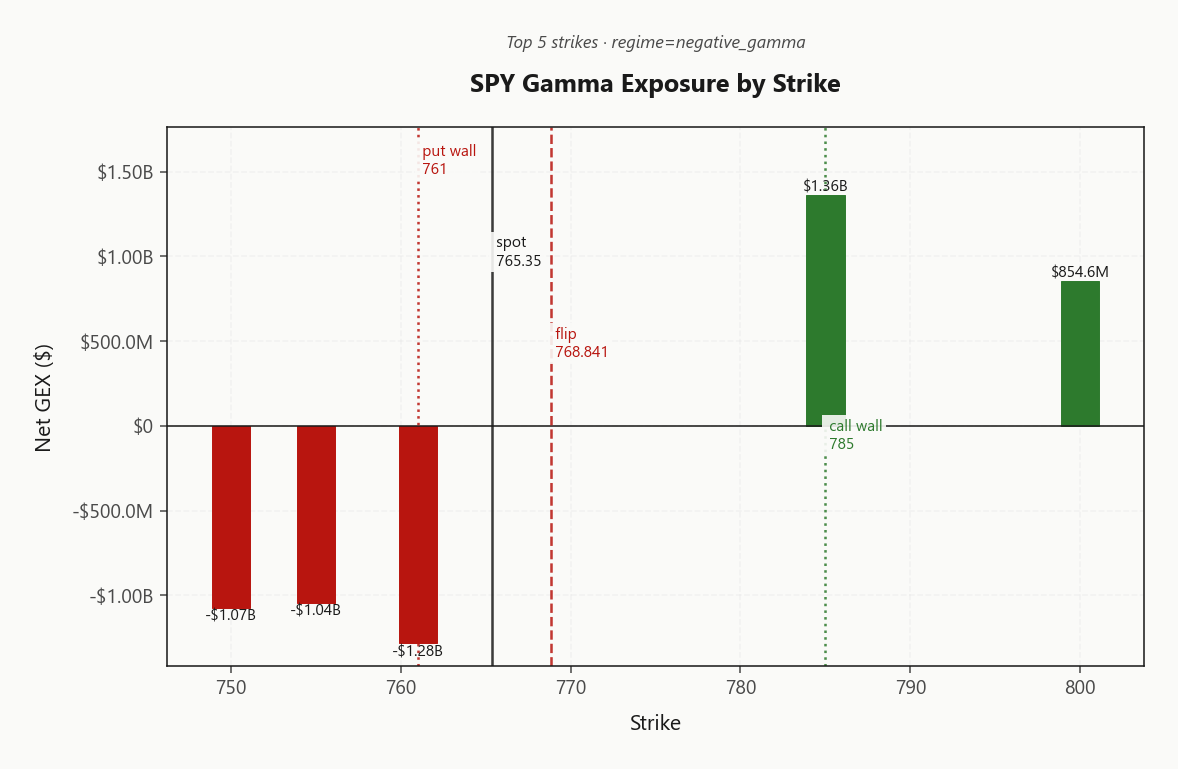
SPY's highest-OI strike at 500 is a LEAP anchor, not today's battle - the live book sits between the put wall at 761.00 and the call wall at 785.00. Spot at 765.35 trades below the gamma flip at 768.84, so dealer hedging amplifies every tick rather than dampens it.
The top-strike concentration at 785.00 carries $1.36B of net gamma - a magnet if spot works back up into the wall, and the pin candidate into expiry. Max pain at 770.00 sits inside the active zone, reinforcing the gravitational bid toward the middle of the book.
Trade the range, not the tails: fade approaches to 785.00, respect 761.00 as tape support, and treat a break of either wall as flow-accelerated continuation rather than noise. Reclaim of 768.84 is THE regime pivot.
What it means for your trading
Active structure is bounded by 761.00 and 785.00 with a gamma magnet at 785.00; a break of either wall unlocks amplified flow, while a reclaim of 768.84 flips the dealer bias from destabilizing to supportive.
Trading readThe heavy negative GEX cluster below spot at the put wall 761.00 says dealers amplify moves lower there - sit long the 785.00 call wall as a fade level, treat any push below the put wall as flow-accelerated continuation.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY sits 0.4561745271 below the gamma flip at 768.8413317428 with net VEX at -$61.42B - vanna is an accelerant, not a stabilizer. Any vol pop forces dealers to sell delta into the tape, and with spot pinned below the flip that flow lands one-directional: down. There is no offsetting greek to lean on here.
Charm reinforces the same vector. Net CHEX at -$616.2K is bleeding hedges into the close, meaning the passage of time itself pushes dealer flow against the tape rather than muting it. Current bias reads Destabilizing - expect amplified moves, not mean reversion, until spot proves otherwise.
The pivot is binary. Reclaim 768.8413317428 and dealer flow flips supportive as vanna/charm invert sign; hold below and the destabilizing regime extends into settlement. Trade the level, not the narrative.
What it means for your trading
Vanna and charm both cut against the tape while spot sits 0.4561745271 below the flip at 768.8413317428 - fade rallies into resistance, don't chase dips, and treat a clean reclaim of the pivot as the sole signal to flip short-vol aggressive.
Cross-Asset Confirmation
Cross-asset tape reads equity-vol event, not credit shock. MOVE at 96.00 sits calm while VIX at 16.19 runs elevated - bonds refuse to confirm the equity anxiety, which is the tell that rates desks aren't repricing risk. Fear & Greed at 34 reading Fear stacks contrarian bounce fuel underneath the tape, but sentiment alone doesn't reclaim the flip.
QQQ at 736.44 and IWM at 280.10 both trade weak, neither cracks. The regime split matters: SPY negative gamma with QQQ regime undetermined flags True divergence - that's dispersion, not systemic. Cross-asset tone reads Unknown, so trade the split rather than hedge the shock.
Implication: single-name convexity and index-vs-component dispersion setups pay here; blanket index tail hedges overpay while MOVE stays anchored.
What it means for your trading
MOVE at 96.00 refusing to confirm VIX at 16.19 says this is equity dispersion, not a credit event - trade the SPY/QQQ regime split via single-name convexity rather than buying index tails.
Scenario EV
The scoring engine returns Iron Condor at 40, beating the put-spread alternative at 27 - the premium and roll-carry stack favors two-sided premium collection over directional short-delta. Optimal window sits at 30-45 DTE, deep enough to capture VIX-Contango roll-down yet short enough to harvest the fat IWM VRP at 6.14% before it decays.
Sizing clears standard because VVIX/VIX at 5.64 registers Normal - no jump-premium penalty, no half-size haircut. Frame wings tight against the dealer scaffolding: put wall 761.00 and call wall 785.00 mark the flow-defended range where dealer hedging works with the structure rather than against it.
Preference within the complex tilts to IWM over SPY - small-cap VRP at 6.14% pays materially more per unit risk than SPY at 0.89%, and the richer smile absorbs wing widening without collapsing credit.
Trade: sell Iron Condor in 30-45 DTE with wings framed inside the 761.00 put wall and 785.00 call wall. Prefer IWM over SPY - VRP at 6.14% pays materially more than SPY's 0.89%, and the regime label Elevated / Watchful clears standard-size entries.
Avoid: naked long vol into Contango term structure, chasing SPY dips below the pivot at 768.8413317428, and single-name shorts into rich IWM VRP without an index hedge. Dealer bias reads Destabilizing below flip - fade only after reclaim, not into the break.
Watch: a reclaim of 768.8413317428 flips dealer flow from destabilizing to supportive and unlocks aggressive short-vol. VVIX break above the round-hundred level shifts sizing to half and warrants a far-OTM VIX-call tail overlay.
What it means for your trading
Sell 30-45 DTE Iron Condor preferentially in IWM, wings pinned to the 761.00/785.00 book. Two triggers change the trade: a reclaim of 768.8413317428 lets you press short-vol, a VVIX break higher forces down-sizing and a cheap tail.
US - Iran mediator talks scheduled for early next week is the single biggest known-unknown into midweek - a de-escalation headline collapses the crude/vol bid; a breakdown re-prices energy and equity tails higher.
Trump's public 'winning very soon' framing on the Iran conflict adds headline-risk convexity for vol sellers - geopolitical binary that keeps VIX bid despite the Contango term structure.
Wall Street lower with oil and yields firm - the classic bear-tape combo when growth stocks lose their rate cushion; keeps SPY pinned below the 768.84 flip.
Micron earnings Wednesday is the near-term single catalyst for the AI trade - an inline print keeps dealer positive-gamma add in mega-caps intact; a miss punches QQQ dispersion higher.
UK diesel at record highs from Iran-war supply strain confirms energy is now a live macro tail - feeds into MOVE at 96.00 staying watched, not calm, over the next two weeks.
Qatar LNG force-majeure extensions ripple into Europe/Asia energy risk - a slow-burn stagflation input that keeps commodities bid and rate-cut hopes on hold, marginally bearish for equity multiples.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.07 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.84 against a spot of 765.35. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.96% with a volatility risk premium of 0.89%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.19. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime