Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 769.53 sits right on top of the 770.00 call wall with net GEX at $4.72B - mean-reversion tape but no cushion. Key levels: call wall 770.00 caps upside, put wall 765.00 is the trapdoor, gamma flip status is Stored Sign Mismatch so treat the pivot as the wall itself. Dealer positioning: net VEX at -$93.79B means vol-up equals delta-sold - hostile if the tape turns. Vol read: VIX at 15.21 with term structure Contango and VVIX at 89.59 = sellers still paid the carry but MOVE at 104.58 is the outlier warning. IWM at 282.00 is negative gamma with VRP at 5%, QQQ at 744.24 is positive gamma with VRP at 1.55% - same regime, opposite dealer posture. Bottom line: route iron condors through IWM at 21-30 DTE, avoid naked SPY short vol against a thin 1.03% premium, watch 280.00 as the first flow-amplifier level.
Contango steady, VRP thin on SPY, fat on IWM - regime split, IWM route wins
SPY sits within a whisker of 770 in a positive-gamma-adjacent tape, with Steep contango - vol sellers favored and Low vol-of-vol keeping realized capped. QQQ confirms the mean-reversion regime but IWM diverges into negative gamma, so the day's edge is not in index premium - it's in small-cap where VRP is fat and dealer flow amplifies. MOVE printing a sharp jump against a quiet VIX is the tell: bond-vol contagion risk is the reason to size down, not up.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
769.53
-
-
770
765
760
$4.72B
-
QQQ
744.24
738.90
+0.72%
745
730
721
$5.94B
Long gamma
IWM
282
292.41
-3.56%
285
280
285
-$3.71B
Short gamma
VIX
15.21
15.18
+0.20%
20
15
19
$21.57M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.61
10.58
+1.03
1.51
2.23
0.68
QQQ
17.17
15.62
+1.55
1.91
1.41
0.74
IWM
17.86
12.86
+5.00
0.68
2.22
2.33
VIX
83.78
103.22
-19.44
-143.46
0.31
0.08
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
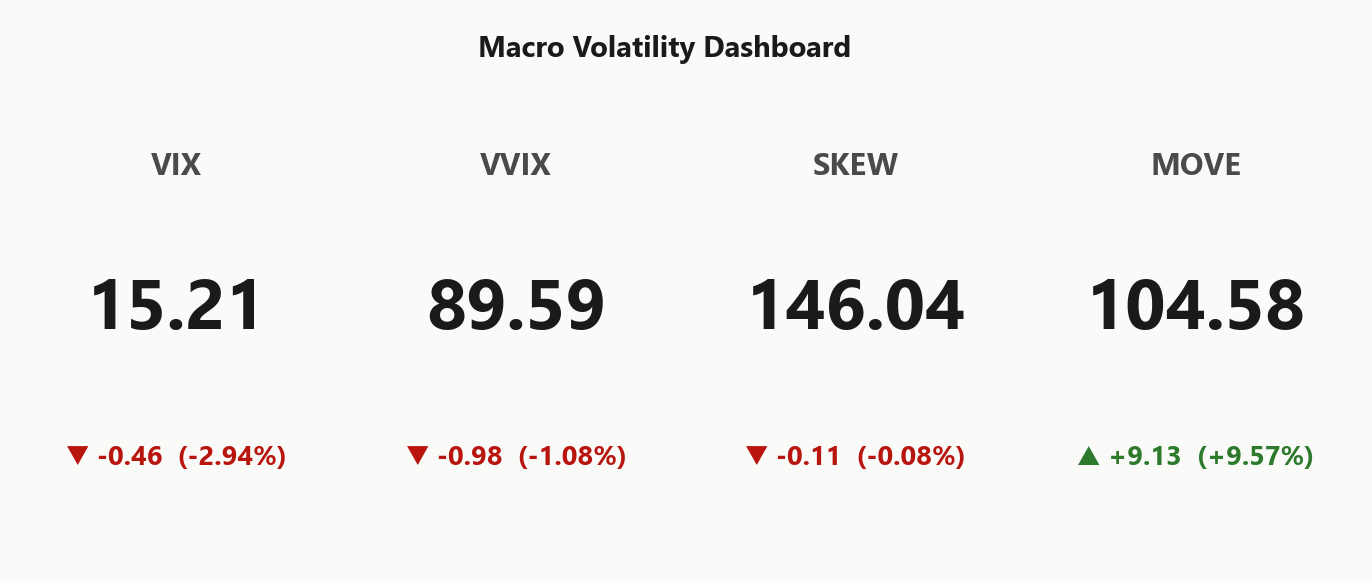
VIX
15.21
-2.94%
VVIX
89.59
-1.08%
SPX
7,726.61
+0.29%
SKEW index
146.04
-0.08%
MOVE (bond vol)
104.58
+9.57%
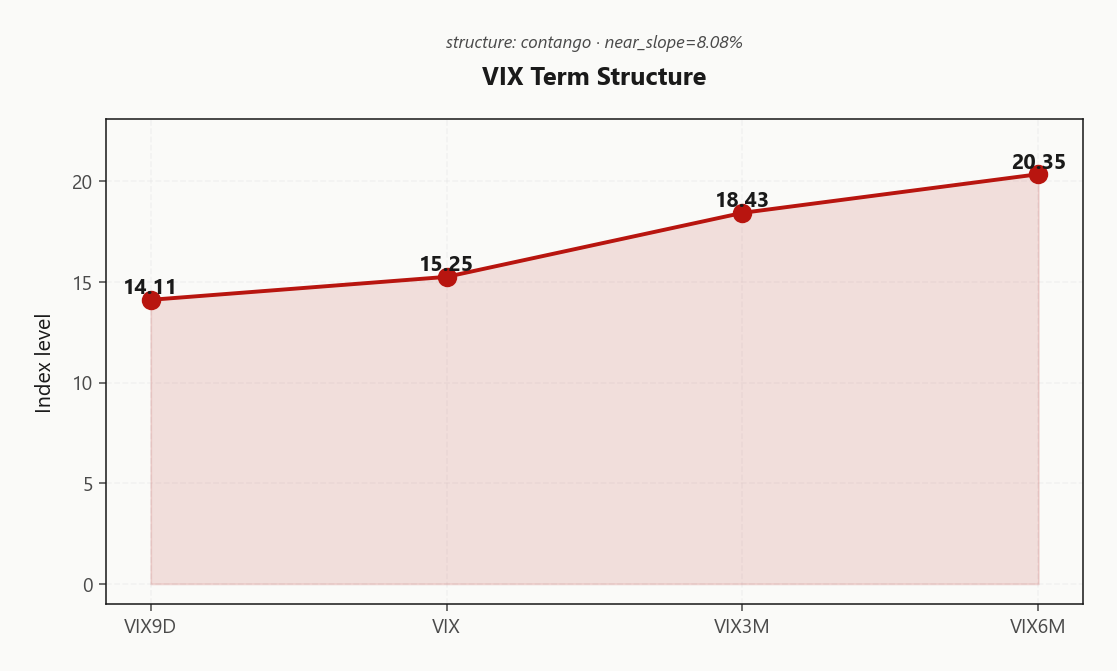
VIX term (9d/30d/3m/6m)
14.11 / 15.25 / 18.43 / 20.35
Steep contango
VVIX / VIX
5.89
Low
Regime
Elevated / Watchful
Regime Assessment
Regime prints Elevated / Watchful with VIX at 15.21 - the tape is neither calm nor stressed, and the classifier lands in Elevated territory. Five-session panic transition probability sits at 0.05, so the tail is contained, not absent; ten-session drift back toward the low-vol basin runs 0.45, biasing mean-reversion as the base case.
Half-life of 15 sessions makes this regime sticky - not a candidate for rapid re-pricing on noise. The only credible break-through path is MOVE contagion transmitting from 104.58 into equity term structure; absent that, expect the Steep contango - vol sellers favored carry and Low vol-of-vol backdrop to hold. Cross-asset regime is Unknown at the index level but split at the small-cap seat, which is where fragility lives inside an otherwise sticky watchful regime.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - sticky, mean-reverting base case, contained tail. Sizing guidance Standard Size; the break-through trigger is MOVE, not VIX.
Trading readVIX, VVIX, and SKEW confirming calm - MOVE is the outlier by a wide margin. When bond vol diverges from equity vol like this, equity vol usually catches up rather than the reverse.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The curve is in Steep contango - vol sellers favored - VIX9D at 14.11 printing below spot VIX at 15.25, with the 3M leg at 18.43 extending through 20.35. Carry is intact across the term - vol sellers get paid, but the whole trade rides on that front-week discount holding.
The fair-warning line is the near slope at 8.08% pct. Any flattening there is the first tell that the front is repricing an event, and a flip to backwardation would relocate premium onto the front week where dealer gamma is thin. VIX9D under spot means no near-term event premium is currently in the tape - that's a condition, not a guarantee.
Sweet-spot DTE is the middle of the curve. Forward 30-to-60 fair vol sits at 19.8296772541, forward 60-to-90 at 22.1038480813 - that's the reference for calendar structuring. Own the mid, sell the front, and avoid front-week gamma where any MOVE-driven vol lift transmits fastest.
What it means for your trading
Structure is Steep Contango with Contango intact across the curve - sell front-week vol, own mid-curve calendars, watch the near slope at 8.08% pct as the flip-signal.
Trading readSteep contango on the near slope confirms carry, but the day's watch item is any flattening in the front - that's the first tell that the market is pricing an event, not just calm.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.61% against HV20 at 10.58 leaves VRP at 1.03% - razor-thin, and not a level that pays you to be short index vol. HV60 at 11.13 still sits above HV20, so the compression is recent, not a fresh low-vol regime - the realized print has room to mean-revert higher, which asymmetrically punishes the naked short-vol seat on SPY.
IWM tells the opposite story: VRP at 5% is fat, with options paid well above realized. QQQ splits the difference at 1.55% - the middle-ground read that confirms the asymmetry is structural, not a single-name artifact. Index-level premium is exhausted; small-cap premium is not. The vol-selling capital allocation should skew toward IWM, where the edge is concentrated and dealer negative-gamma amplifies any realized print back into the seller's favor on mean reversion.
What it means for your trading
SPY VRP at 1.03% is too thin to defend a short-vol seat, while IWM VRP at 5% is where the paid premium actually lives - route the vol-selling book through small-cap.
Skew Convexity
SPY quarter-delta skew prints 1.51% with a smile ratio of 1.19% - a hedged-tape configuration, not a stress reading. Put wing IV at 9.36% sits meaningfully over ATM at 7.95%: downside is bid, orderly, and paid for. Nothing here signals capitulation demand - just a book that already carries the hedge.
The call wing tells the more actionable story. IV at 7.85% is at parity with ATM - dealers are pricing zero upside convexity. No chase premium, no gamma grab, no positioning for an unpin. Combined with the put bid, the smile leans asymmetrically short into the tape, and it does so quietly.
Trade construction follows directly: put spreads over naked puts. You are overpaying for tail as an outright when the wing is this bid and the smile ratio is this stretched. Finance the long put by selling the further wing - the skew is doing the work for you. On the call side, there is nothing worth owning outright; call spreads only make sense as delta expressions, not vol expressions.
What it means for your trading
Skew at 1.51% and smile ratio 1.19% describe an orderly hedged book with a bid put wing and a flat call wing - asymmetric enough to force spread structures, not tight enough to justify chasing tail outright.
Vol-of-Vol Structure
VVIX at 89.59 against VIX at 15.21 puts the ratio at 5.89, squarely in Low territory. No binary regime is being priced, no jump premium is on the tape - the vol surface is not paying for a shock. Sizing follows the read: Standard Size, with no reason to trim short-vol exposure on vol-of-vol grounds alone.
The counter-signal is MOVE at 104.58, printing a sharp move higher against a drifting VIX. Bond-vol contagion is the reason to keep this call qualified - one instrument does not confirm calm, and MOVE historically leads equity vol on macro repricings. Treat Low VVIX as permission to size, not a mandate to press.
What it means for your trading
VVIX at Low regime clears the way for Standard Size on premium-selling structures, but MOVE at 104.58 is the standing warning that the calm is one bond-vol transmission away from breaking.
Dispersion Spread
Index premium is done. SPY ATM IV at 11.61% has compressed into a tape where single-name vol refuses to follow - QQQ ATM at 17.17% and IWM ATM at 17.86% both sit well north of the index print. Correlation is not doing the work index hedges need it to do; the basket is quiet because the components are cancelling, not because the components are calm.
That gap is the trade. Sell the index where premium is exhausted, own the single-names where the idiosyncratic bid is intact - mega-cap dispersion in the QQQ complex and small-cap dispersion in the IWM book, especially anything earnings-adjacent. The dispersion seat is idiosyncratic-long, index-short, and today it's the cleanest way to monetize a regime where SPY VRP at 1.03% pays nothing while IWM VRP at 5% pays plenty.
What it means for your trading
SPY IV at 11.61% against QQQ 17.17% and IWM 17.86% says the index is compressed while components stay bid - sell index vol, own single-name vol, and route the short-vol capital where the premium actually lives.
Liquidity & Microstructure
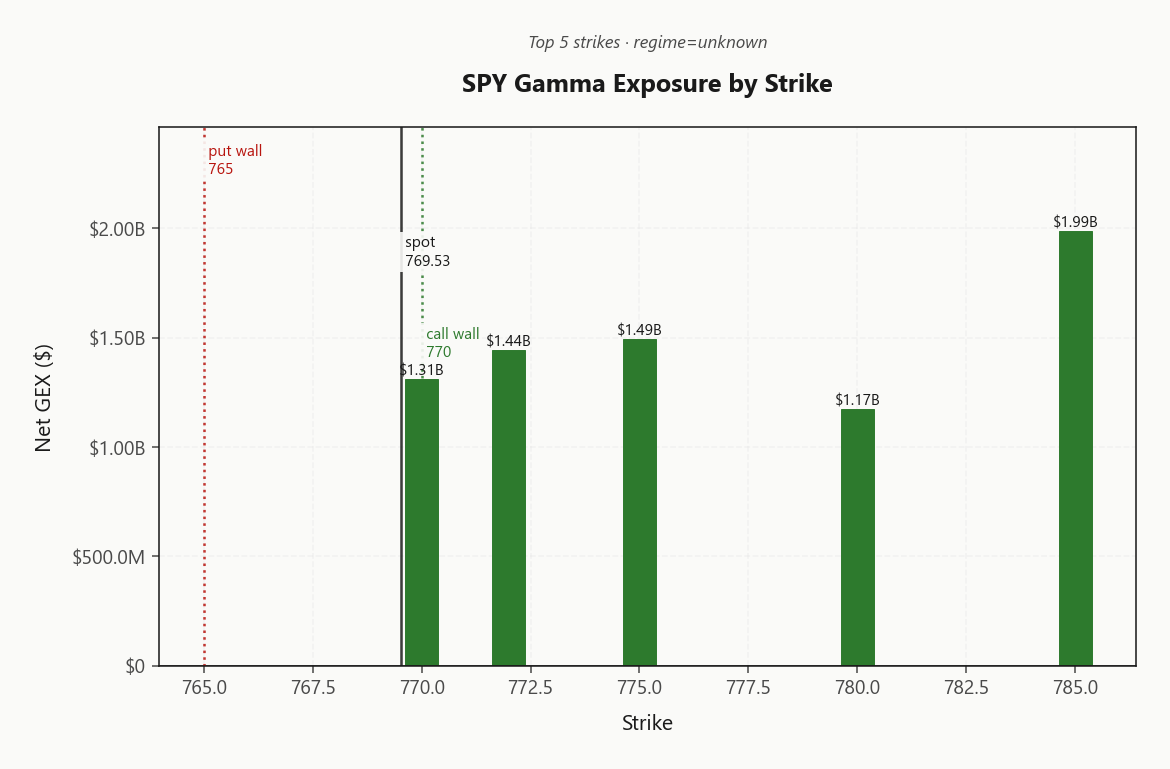
SPY's open interest concentrates at the deep-ITM 500 anchor - LEAPS residue, not a tradeable dealer level. The live gamma cluster sits tighter: 765.00 on the downside, 770.00 on the upside, with spot pressed directly against the ceiling. Flip status reads Stored Sign Mismatch, so treat the wall itself as the pivot rather than any inferred flip.
Dealer supply is heaviest at 785.00, carrying net GEX of $1.99B - that's the immediate ceiling and the level to trade against. Above 770.00, dealer flow flips supportive as short-gamma hedgers chase; below 765.00, the same mechanics reverse and dealers become the accelerant into any air pocket.
Inside the range, mean-reversion dominates and pins are the base case. Outside it, the tape gets its trend - and the wall, not the anchor, is where the flow unlocks.
What it means for your trading
The tradable book runs between 765.00 and 770.00, with spot on top of the ceiling and the deep-ITM 500 anchor irrelevant to today's dealer flow. A break of 785.00 is where dealer mechanics invert - mean-reverting inside, amplifying outside.
Trading readGamma cluster is layered tight between the put wall and call wall with spot in the middle - dealers dampen inside the range, amplify outside it. The tradable levels sit at the wall, not the deep-ITM anchor.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY net VEX at -$93.79B is the read of the day - deeply negative, meaning dealers sell delta into any vol expansion. That's the vanna accelerant: a MOVE-led vol spike doesn't just widen premium, it forces mechanical supply into the tape. With bond-vol already diverging, this is the transmission channel that would flip the regime from mean-reverting to trending in a session.
Charm at -$2.8M is effectively neutral - no close-pin pressure being built, no directional decay bleed to lean into. The pin story today is gamma-driven, not charm-driven, which means late-session drift is a coin flip rather than a magnet.
The charm pivot at 770 sits essentially on top of spot (0.0610762413 pct away), with bias Neutral. A break either direction unlocks dealer flow - up through the pivot puts them chasing, down through it hands the vanna book the wheel. Trade the pivot, not the bias.
What it means for your trading
Vanna is the live risk, charm is dormant - negative VEX at -$93.79B means any MOVE-driven vol expansion mechanically converts into dealer selling, and the pivot at 770 is the trigger line for that flow.
Cross-Asset Confirmation
MOVE prints at 104.58 against a VIX drifting to 15.21 - bond-vol shock without equity-vol confirmation. That divergence is the single most important cross-asset tell of the session: rates volatility is repricing while equity term structure holds Contango. History says equity vol catches up to bond vol, not the other way around, so treat the calm surface as borrowed time.
Fear & Greed reads Fear at 36 - retail defensive, not capitulated. Positioning is cautious enough to underwrite a grind higher, thin enough that a real shock lands on empty books. The regime split is confirmed: QQQ at 744.24 holds positive_gamma while IWM at 282.00 sits in negative_gamma - same tape, opposite dealer posture.
Mega-cap dealer flow anchors the index; small-cap dealer flow amplifies. The SPY hedge misses the tail that matters - if MOVE contagion transmits, it lands in IWM first.
What it means for your trading
Bond-vol at 104.58 diverging from a quiet equity tape while QQQ/IWM regime split is True - the day's asymmetry is small-cap fragility, not index premium.
Scenario EV
The session's highest-EV structure resolves to Unknown, routed through IWM where VRP prints 5% against SPY's thin 1.03%. The asymmetry is the whole trade - same contango regime, opposite dealer posture, and the paid seat is unambiguously small-cap. Optimal tenor sits at 21-30 DTE, mid-curve where 19.8296772541 anchors fair vol; front-week is the gamma trap, back-month is the carry lane.
VVIX in Low territory with ratio 5.89 confirms no jump premium is being paid - sizing guidance resolves to Standard Size, no defensive haircut warranted. VRP assessment Unknown keeps the edge concentrated on the IWM leg, and the pivot at 770 is the SPY-side kill switch: a break either way unlocks dealer flow and rewrites the trade.
What it means for your trading
Route iron condors through IWM at 21-30 DTE where VRP 5% pays for the seat; skip naked SPY short vol at 1.03%. VVIX Low greenlights Standard Size, with the 770 pivot as the abort level.
Actionable Summary
Route premium selling through IWM at 21-30 DTE where VRP prints 5% - fat, and the only seat in the index complex paying carry today. Naked SPY short vol is a pass: 1.03% is razor-thin against realized, and the risk/reward doesn't clear the hurdle. Structure recommendation resolves to Unknown; keep it small-cap-routed, avoid the front-week gamma trap.
Pivot sits at 770 - a break either way unlocks dealer flow, and spot is essentially riding it. MOVE at 104.58 is the contagion tell against a quiet VIX; bond-vol divergence is the reason to size to Standard Size, not fade the signal. IWM's put wall at 280.00 is the first flow-amplifier level to watch.
Regime label Elevated / Watchful - sticky, not fragile, but MOVE is the one line that would flip the read. Trade the edge where it lives: small-cap premium, mid-curve DTE, size standard.
What it means for your trading
IWM-routed premium selling at 21-30 DTE is the session's edge; pivot 770 and MOVE at 104.58 are the two levels that dictate whether the Elevated / Watchful regime holds.
Rapid-rates-break narrative is the credit-side echo of the MOVE spike - the single most important non-equity signal for how sticky this regime stays.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.21 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $4.72B. The gamma flip sits at N/A, with the call wall at 770.00 and the put wall at 765.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 769.53. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.61% with a volatility risk premium of 1.03%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.21. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime