Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY trades 771.52 with dealers long gamma at $9.57B - positive-gamma regime, mean-reversion dominates. Call wall 775.00 caps upside, put wall 770.00 cushions the tape, gamma flip sits at 769.74 with spot holding just above - a shallow cushion, not a fortress. Dealer vanna at -$111.59B and charm at -$4.5M imply muted vol response but modest end-of-day selling pressure. VIX 14.97 with VIX9D/VIX/VIX3M/VIX6M in steep contango (Contango, near slope 14.11%%) and VVIX at 88.21 = vol sellers paid, jump risk quiet. SPY VRP 0.92% confirms IV rich to RV. IWM negative gamma with spot below flip 293.03 is the fragility read - small-caps break first if Iran headlines re-escalate. Bottom line: iron condor in SPY 30-45 DTE inside 770.00/775.00, avoid chasing directional bets while VIX9D anchors the front, watch charm pressure into close near 770.00.
Positive gamma cushion intact; VIX contango + low VVIX keeps vol sellers in the driver's seat
SPY 771.52 sits above the 769.74 flip with dealers deeply long gamma at $9.57B net GEX, muting intraday range while QQQ mirrors the setup. IWM diverges into negative gamma below its 293.03 flip, making small-caps the fragility tell if geopolitical headlines escalate. VIX contango, low VVIX, and active VRP align on the same trade: harvest premium in index complex, keep tail hedges cheap given headline risk.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
771.52
769.74
+0.23%
775
770
760
$9.57B
Long gamma
QQQ
745.30
739.67
+0.76%
750
730
721
$7.20B
Long gamma
IWM
283
293.03
-3.42%
285
280
285
-$3.32B
Short gamma
VIX
14.97
-
-
20
14.50
19
$12.87M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.54
10.62
+0.92
1.31
2.23
0.91
QQQ
17.04
15.63
+1.41
1.42
1.41
0.87
IWM
18.01
12.79
+5.22
0.14
2.22
1.41
VIX
89.35
102.64
-13.29
-141.73
0.31
0.47
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
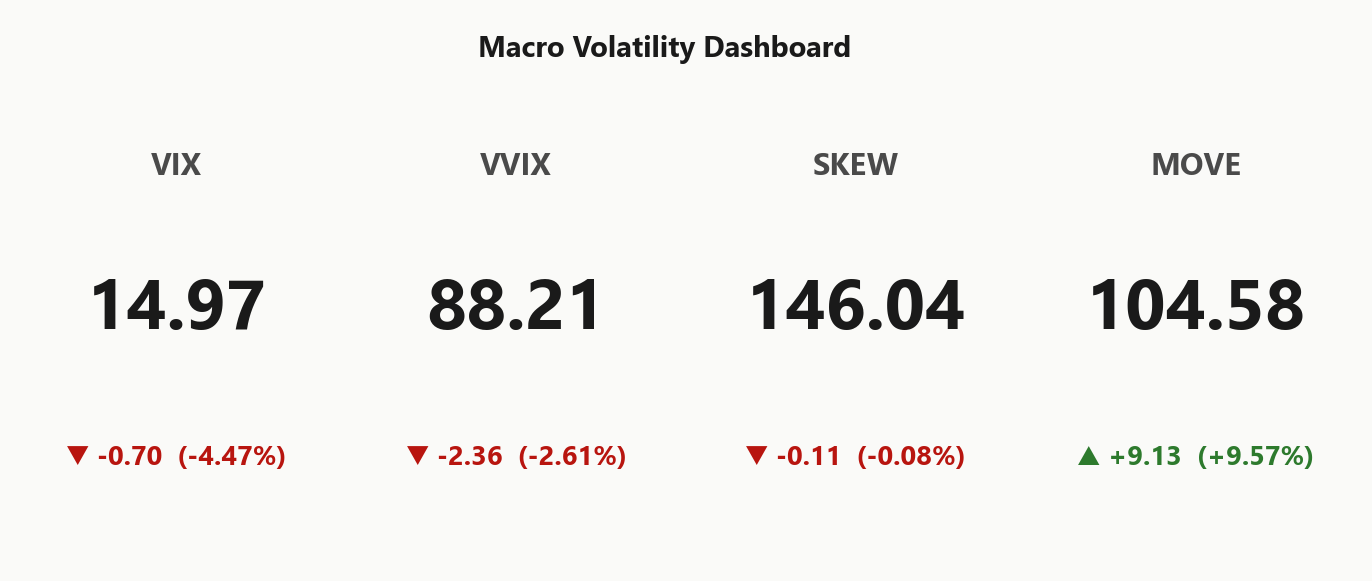
VIX
14.97
-4.47%
VVIX
88.21
-2.61%
SPX
7,744.55
+0.52%
SKEW index
146.04
-0.08%
MOVE (bond vol)
104.58
+9.57%
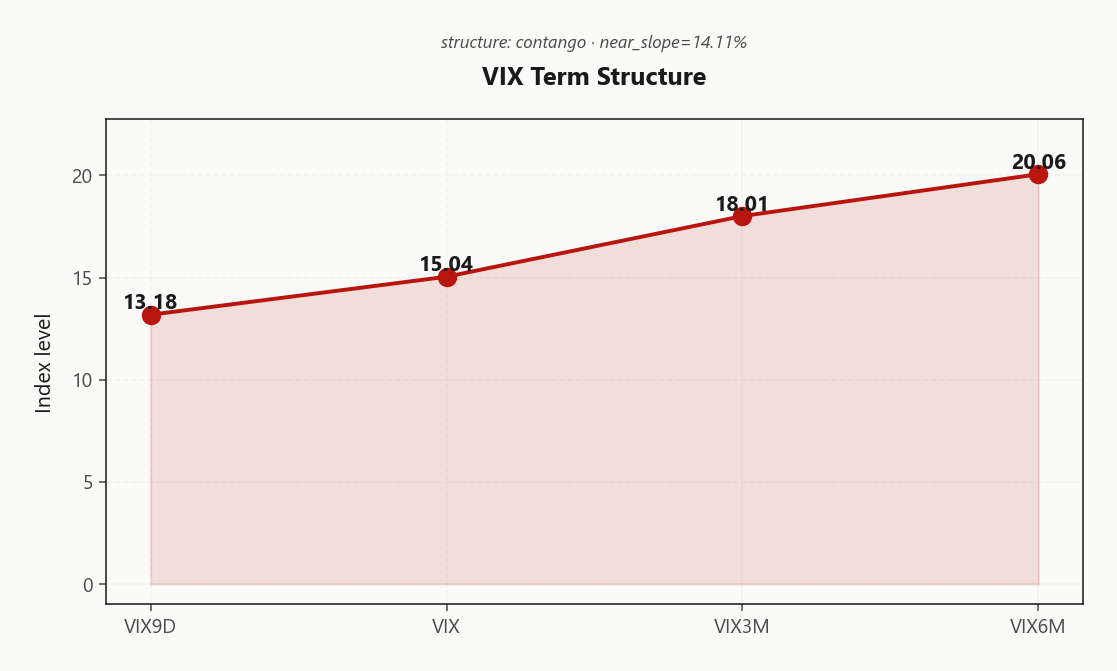
VIX term (9d/30d/3m/6m)
13.18 / 15.04 / 18.01 / 20.06
Steep contango
VVIX / VIX
5.89
Low
Regime
Low / Carry
Regime Assessment
The tape sits in a Low / Carry regime with VIX anchored at 14.97. Transition math is favorable: the panic jump probability over the next five sessions reads 0.05, while the ten-session persistence path prints 0.45. Empirical half-life stretches to 30 sessions - this state is sticky, not fleeting.
Plan trades on that horizon. Carry seat pays for size, contango pays for calendar rolls, and VVIX cooperation at 88.21 keeps sizing at Standard Size. The tail is not the base case - it is the reason to keep VIX wing calls on the shelf. Geopolitical headlines remain the mechanism that shortens the clock; nothing in the vol surface or MOVE-adjusted rates complex is pricing that scenario today.
Regime is Low / Carry with a 30-session half-life and only 0.05 panic probability over five sessions - size for carry, hedge the geopolitical tail cheaply.
Trading readVIX and VVIX cooperating on suppression while MOVE quietly climbs - a rates-vol divergence is the pre-warning signal to monitor.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints textbook Contango with 13.18 anchored below spot 15.04, ruling out any acute front-end stress. Near-term slope of 14.11% pays sellers to roll down the curve, and the Steep Contango regime label confirms tail hedges remain cheap while carry stays live.
Further out, 20.06 against 18.01 shows term premium priced but not stretched - no event kink, no bimodal outcome in the strip. Front-week 0DTE IV underprices realized noise, so the edge sits squarely in the belly where slope is steepest and gamma bleed stays manageable.
Trade the geometry: harvest premium in the 30-45 DTE belly of the SPY complex, keep VIX upside optionality on as the cheap tail against a rates-vol surprise.
What it means for your trading
Steep Contango with Steep Contango keeps vol sellers paid to roll down; belly of the curve is the seat, front-week is the trap.
Trading readSteep contango with no near-term kink says vol sellers keep the carry seat - market is not pricing an event, and any spike is a technical, not fundamental, break.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.54% continues to trade rich to realized, with HV20 at 10.62 printing below HV60 at 11.14 - a slight compression in tape volatility that leaves implieds carrying a live, if modest, premium. SPY VRP sits at 0.92%, sustainable rather than stretched, keeping the short-vol seat paid without forcing size.
The dispersion tell is small-caps: IWM VRP at 5.22% is aggressively wide, pricing stress that hasn't materialized in realized. QQQ VRP at 1.41% confirms tech premium bid but paid - the mega-cap complex offers cleaner carry than the small-cap wing, where negative gamma below the 293.03 flip discounts the seat.
Bias short-vol structures across the index complex, size to the SPY VRP rather than the IWM outlier, and treat IWM premium as a size-down harvest given the fragility beneath the flip.
What it means for your trading
Options remain rich to realized across the complex, with SPY VRP at 0.92% offering sustainable carry and IWM VRP at 5.22% flagging the richest - but riskiest - short-vol seat. Bias short-vol structures over long, but anchor them in SPY where the gamma cushion supports the carry.
Skew Convexity
SPY's quarter-delta skew prints 1.31% with a smile ratio of 1.16% - the put wing is bid at 9.66% against a call wing offered at 8.35% versus ATM 9.02%. Ordered downside premium, not panic. The tail isn't being chased; hedgers are paying up in size but the ten-delta isn't lit.
IWM tells the counter-story with skew at 0.14% - nearly flat despite spot living below its 293.03 flip in negative gamma. Flat skew inside a fragile regime signals no directional conviction either way, which is itself a warning: small-cap protection isn't being priced even where it should be. Section signal reads Skew Steep - steepening in SPY, dormant in IWM.
Structure preference: put spreads over naked puts. The wing is paid for; sell it to finance the long leg rather than buying it outright.
What it means for your trading
SPY skew at 1.31% is steep but orderly - put wing bid, call wing offered, ten-delta quiet. Prefer put spreads over naked puts and treat IWM's flat skew as the fragility tell, not comfort.
Vol-of-Vol Structure
VVIX prints 88.21 against spot VIX at 14.97, pushing the VVIX/VIX ratio to 5.89 - squarely in the Low jump-risk zone. The tape is telling you the market is not paying up for the second derivative; convexity on VIX itself is offered, not bid.
That ratio maps directly to sizing guidance of Standard Size - no haircut on short-vol notionals, no bimodal outcome being priced into the wings of VIX options. A vol spike from here would arrive as a technical break, not a structural repricing, because the vol-of-vol complex isn't warning you in advance.
Combined with the Steep Contango curve and an Vrp Active premium read, the vol-of-vol seat is the green light for the carry trade: iron condors and short strangles get full-size treatment while VVIX behaves. Watch the ratio, not the level - a lift back toward historical means is the earliest signal the sizing regime shifts.
What it means for your trading
VVIX at 88.21 and a ratio of 5.89 keep the vol-of-vol read Low, licensing Standard Size premium sales. Any spike from here is technical, not structural - but the ratio is the tell to monitor before adding size.
Dispersion Spread
Index vol sits suppressed with SPY ATM IV at 11.54% against HV20 of 10.62, yet the single-name tape tells a different story. Absolute GEX repositioning in NVDA, MSFT, and AAPL dwarfs anything happening at the index level, and the section reads Moderate correlation - the dispersion seat is live.
The asymmetry is the trade: idiosyncratic risk keeps repricing in mega-caps while SPY dealers dampen the composite. IWM at 18.01% ATM IV confirms the small-cap wing is not the vehicle here - the cleaner expression is short index vol, long single-name vol, weighted toward NVDA-adjacent names where dealer hedging is doing the real work.
Pair the short SPY strangle or condor against long premium in the top gamma-shifters. The Aligned mega-cap tape means the index short leg carries; the single-name longs earn their keep on the next idiosyncratic print.
What it means for your trading
SPY ATM IV at 11.54% understates the single-name dispersion signaled by Moderate correlation and outsized mega-cap GEX shifts. Sell index vol, own single-name vol in NVDA-adjacent names.
Liquidity & Microstructure
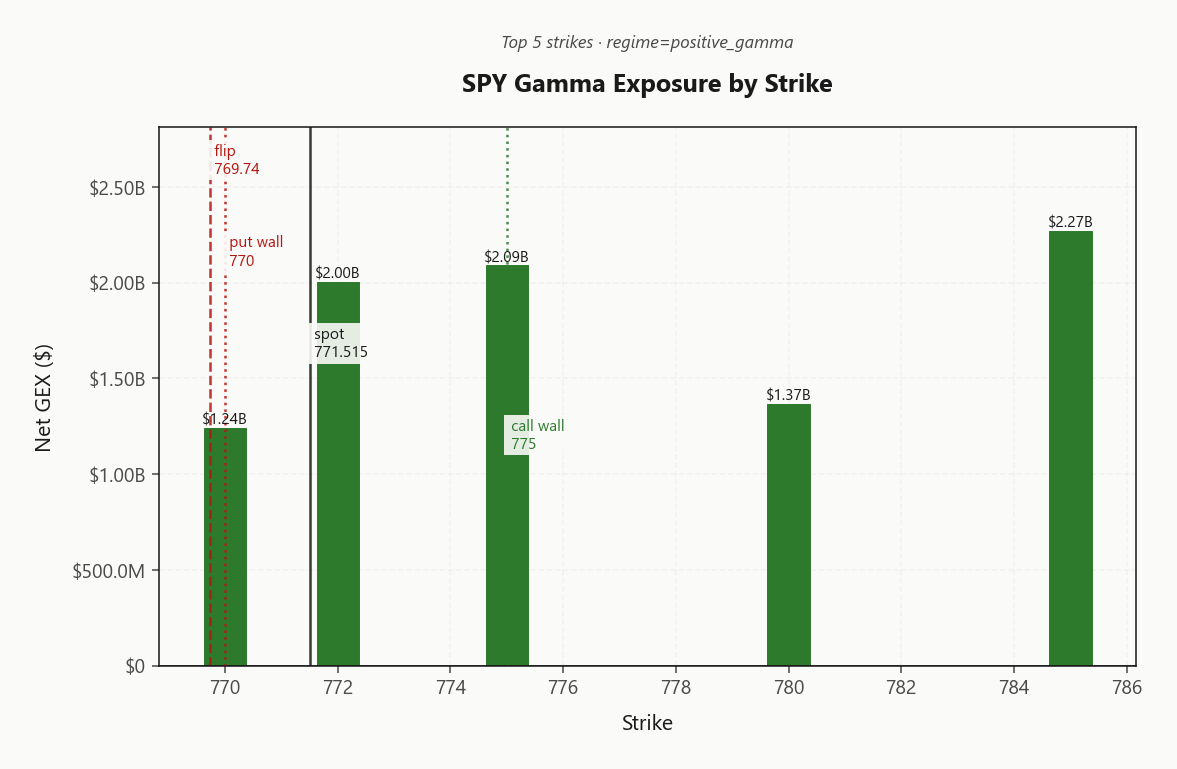
SPY's book anchors at the 785.00 strike with dominant dealer damping of $2.27B in net gamma - the day's magnet and the reason intraday range stays capped. The 775.00 call wall is a hard ceiling into the close; the 770.00 put wall doubles as the support magnet where dealer buying kicks in.
The switch sits at 769.74. Spot at 771.52 holds above it, but the cushion is thin, not deep - a break below flip inverts dealer flow from suppressive to accelerant, and the tape reverses violently. On a real selloff, the 500 highest-OI strike is the lower magnet flow gravitates toward.
Trade the envelope: fade strength into the call wall, treat the put wall as support until spot loses the flip. Structure is Deep, but respect the fulcrum.
What it means for your trading
SPY's dealer book is deep and suppressive above 769.74, with the 775.00/770.00 envelope defining the fade range. Losing the flip flips the regime - until then, mean-reversion inside the walls is the trade.
Trading readDealer damping is concentrated right at spot with the call wall forming a hard ceiling - fade strength into 775.00, treat the put wall as a floor until spot breaks below flip.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits offside at -$111.59B net VEX - a negative print that means any lift in 14.97 forces dealers to sell delta into the move, not buy it. The cushion from positive gamma is real, but it is one VIX pop away from flipping into an accelerant. Charm is quieter but pulling the same direction: -$4.5M net CHEX drips modest sell pressure into the close, tightening the tape rather than lifting it.
The fulcrum is 770 - the charm pivot lands exactly on the put wall, so flow reverses at the same strike that anchors dealer support. Current bias reads Neutral with spot straddling the level; a clean break turns hedging flow from damping to amplifying in a single tick.
Playbook: respect the pivot, keep short strikes inside 770.00/775.00, and treat any VIX print through the mid-teens as the vanna trigger - that is where the cascade lower goes live.
What it means for your trading
Positive gamma masks a hostile vanna/charm stack - dealers dampen now but sell into any vol spike, with 770 the pivot where flow flips.
Cross-Asset Confirmation
Rates vol is the tell today. MOVE at 104.58 printed a 9.57% session while equity vol sits pinned - a quiet credit-channel stress that isn't showing up in VIX at 14.97 or VVIX at 88.21. When rates vol diverges from equity vol, the equity print is the lagging read.
Fear & Greed reads Fear at a score of 38 despite the tape grinding higher - positioning is nowhere near stretched, which caps the pain-trade-lower thesis and keeps the contrarian bid alive. QQQ at 745.30 tracks the SPY positive-gamma regime cleanly; tech is aligned. IWM at 283.00 is the offside asset - small-caps below flip aren't confirming the mega-cap calm.
Cross-asset direction registers Aligned at the index level, but MOVE and Fear & Greed are the dissenting votes. Treat equity vol suppression as conditional on rates behaving - a MOVE follow-through is the first-order break signal, IWM the second.
What it means for your trading
Equity vol is calm but 104.58 on MOVE and Fear sentiment aren't confirming - rates and positioning flag the tail that low VIX is ignoring. Cross-asset reads Aligned on the surface, but watch MOVE and IWM for the first break.
Scenario EV
Structure scoring lands on Iron Condor at 56, comfortably ahead of the put spread alternative at 42. The regime backdrop - contango term structure, positive gamma cushion, and an active VRP read of Unknown - argues for premium harvest over directional convexity, and the scorecard agrees.
The sweet spot sits in the 30-45 DTE window: past the front-week gamma torch, ahead of the next earnings vol pocket, and squarely on the steepest slope of the VIX curve. VVIX at 88.21 keeps sizing at Standard Size - no need to shave clips.
Anchor short strikes inside the 770.00 / 775.00 envelope, where dealer damping does the heavy lifting. Respect the charm pivot at 770 - flow flips there, and the trade thesis flips with it.
What it means for your trading
Scorecard, curve, and gamma map all point to the same seat: a Iron Condor in the 30-45 DTE belly, strikes tucked inside 770.00/775.00.
Actionable Summary
Bottom line: harvest premium in SPY via Iron Condor structures in the 30-45 DTE window, anchored inside the 770.00/775.00 envelope. Regime reads Low / Carry with VIX at 14.97 and VVIX at 88.21, so size normal - not big - and let the Contango curve pay the carry.
Respect the 770 pivot: spot sits fractionally above it and flow flips there. Above, dealers damp; below, they amplify. Avoid IWM directional shorts - spot trades below its 293.03 flip in negative gamma, and the tape cuts both ways. Small-caps are the fragility tell, not a clean short.
Keep tail hedges cheap: MOVE ticked 9.57% against a suppressed equity vol print - that rates-vol divergence is the credit-channel warning to monitor before it reprices the index book.
What it means for your trading
Sell premium in SPY inside the 770.00/775.00 corridor while the Low / Carry regime holds, but treat the 770 pivot as the line where the trade changes character. IWM negative gamma and a rising MOVE are the two tells that break the setup first.
Oil sliding on truce hopes even as Houthi attacks continue = geopolitical premium compressing; supports the low-vol regime but leaves tail hedges cheap
Rate spike history warning ties directly to the MOVE index jump - the credit-vol channel is the one to watch for a real break
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.97 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 769.74 against a spot of 771.52. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.54% with a volatility risk premium of 0.92%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.97. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime