Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closes at 771.25 with net GEX $3.21B and regime tagged Unknown - dealer gamma dampens intraday moves. Key levels: call wall 785.00 caps upside, put wall 750.00 anchors downside, max pain sits at 760.00 with charm pivot at 760. Dealers carry positive gamma but negative vanna (-$108.24B) - a vol spike would flip hedging flow to selling delta into weakness. VIX at 14.87 with Steep Contango term slope of 16.44%% and VRP running 0.7% says premium sellers earn carry but must respect the VVIX at 87.83. QQQ tracks Positive Gamma while IWM is Negative Gamma - small-caps are the fragile leg. Bottom line: sell premium in 21-30 DTE window on index proxies, avoid single-name gamma chase, watch 760 as the flip zone for dealer bias.
Low-vol carry regime with steep contango; SPY positive gamma cushion intact while IWM signals negative-gamma fragility
Index complex closes with SPY at 771.25 inside a deep positive-gamma cushion while IWM remains Negative Gamma - the split says mean-reversion works in mega-caps but small-caps stay trend-prone. VIX at 14.87 with Steep Contango term structure and VVIX at 87.83 confirms carry-friendly conditions, though Fear & Greed at 37 shows sentiment lags the tape.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
771.25
-
-
785
750
760
$3.21B
-
QQQ
744.50
738.22
+0.85%
760
730
721
$3.84B
Long gamma
IWM
282.07
292.79
-3.66%
285
280
285
-$3.79B
Short gamma
VIX
14.87
-
-
20
14.50
19
-$3.52M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.38
10.68
+0.70
1.07
2.23
0.97
QQQ
17.21
15.64
+1.57
2.07
1.41
0.98
IWM
17.76
12.84
+4.92
0.87
2.22
1.32
VIX
89.80
104.35
-14.55
-145.58
0.31
0.19
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
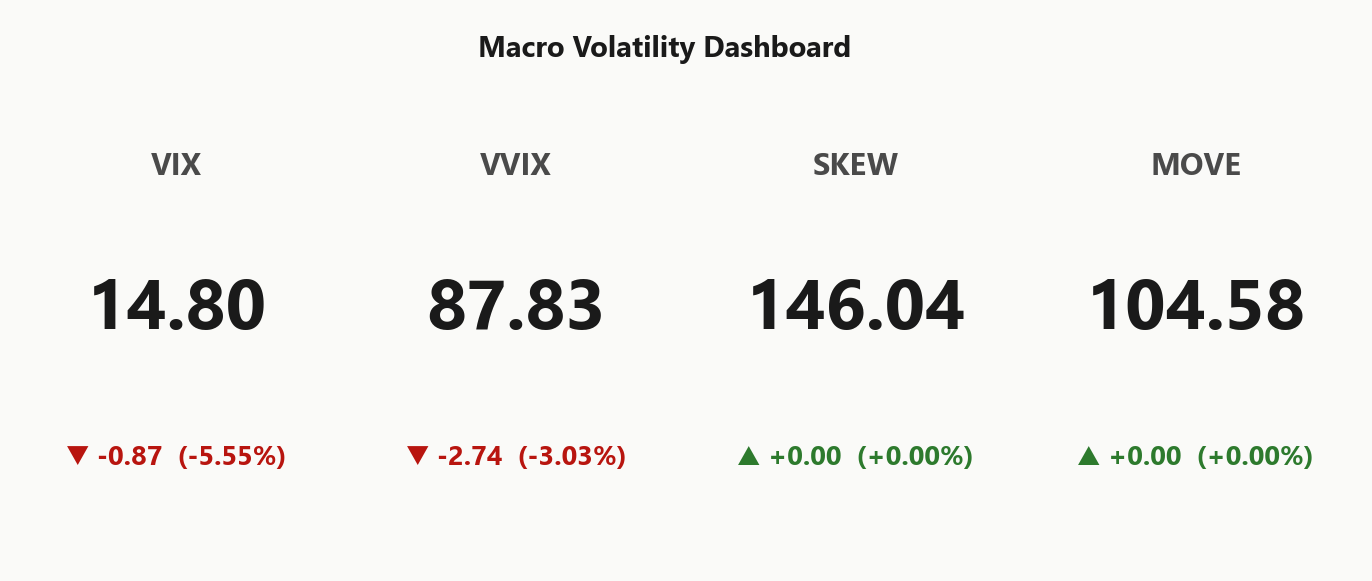
VIX
14.80
-5.55%
VVIX
87.83
-3.03%
SPX
7,743.41
+0.51%
SKEW index
146.04
0.00%
MOVE (bond vol)
104.58
0.00%
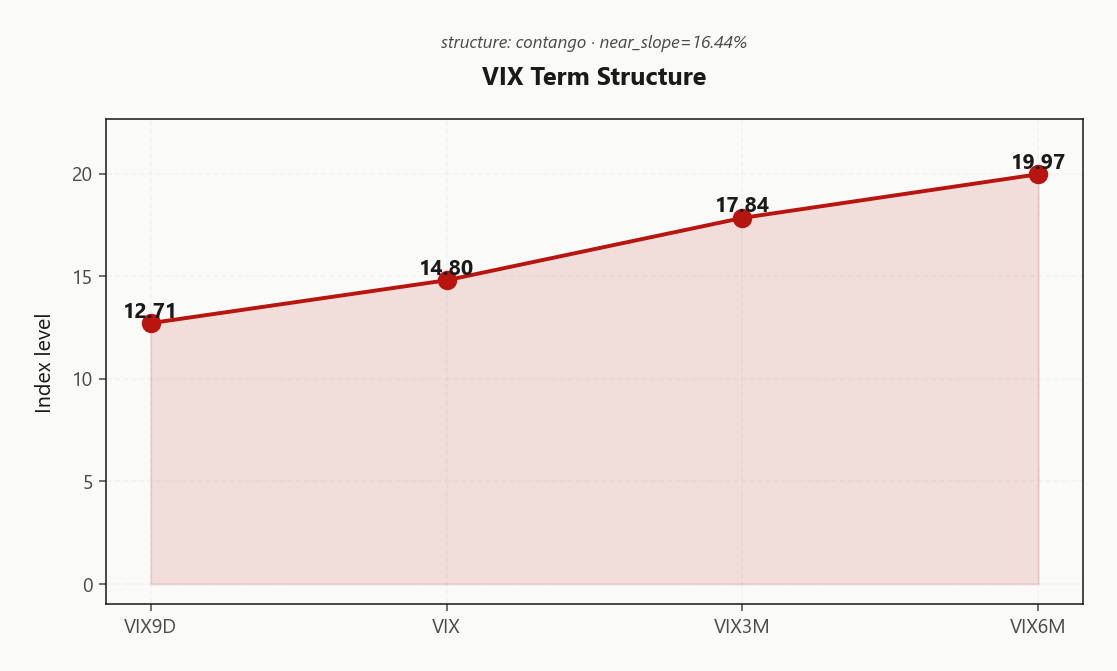
VIX term (9d/30d/3m/6m)
12.71 / 14.80 / 17.84 / 19.97
Steep contango
VVIX / VIX
5.93
Low
Regime
Low / Carry
Regime Assessment
Regime prints Low / Carry with VIX anchored at 14.80 and a half-life of 30 sessions - carry has real runway, and the transition matrix says positioning for continuation dominates positioning for reversal.
To-panic probability over five sessions sits at 0.05 while to-low probability across ten sessions builds to 0.45 - the regime is sticky, not fragile. Signal color reads Green, green-lighting short-vol expression at standard size, with VVIX at 87.83 keeping tail insurance affordable if the tape reprices.
Trade the regime, not the fear: SPY Unknown cushion and QQQ Positive Gamma confirm the mega-cap carry lane, while IWM Negative Gamma is the excluded leg. Watch VVIX and MOVE at 104.58 for the first tell - sticky doesn't mean permanent.
What it means for your trading
Regime tagged Low / Carry with half-life 30 sessions and to-panic probability of 0.05 - position for continuation, keep cheap VIX call convexity as the asymmetric tail hedge.
Trading readVIX, VVIX, and MOVE all quiet and aligned - no divergence flagging a regime shift, so premium sellers can operate at full size while the dashboard stays confirming.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Contango from front to back, with VIX9D at 12.71 sub-VIX 14.80 - no near-term event premium being paid, and the near slope of 16.44%% confirms the carry setup is structurally intact rather than a transient print.
Back-end geometry holds shape: VIX3M at 17.84 against VIX6M at 19.97 keeps the upward slope alive, and the forward 30-to-60 vol implied at 19.1801564123 against forward 60-to-90 at 21.893747966 says the curve is pricing continuation, not compression. Regime tag Steep Contango with signal Steep contango - vol sellers favored greenlights calendar and diagonal expression where roll-down does the work.
The clean edge sits in the 21-30 DTE band - far enough out that vol is fairly priced, close enough that roll-down accrues meaningfully into the front. Sell front-week theta, own back-month vega; curve normalization is the tail that pays, and contango is the carry that funds the wait.
What it means for your trading
Steep Contango across the whole curve is a textbook carry green light - express via calendars and diagonals in the 21-30 DTE window, not naked shorts, so a curve inversion doesn't wipe the trade.
Trading readSteep contango across the whole curve is the textbook carry setup - front-month vol sellers win on both theta and roll-down as long as the curve doesn't invert.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 11.38% prints above HV20 10.68 and HV60 11.16, leaving VRP paid at 0.7% points. Modest but positive - sellers are collecting real premium, not fair value, and the spread survived the close-wrap compression in spot vol.
Across the complex, QQQ VRP prints 1.57% - tech implied stays richer than realized as single-name dispersion keeps index vol propped above component-weighted delivery. IWM carries the cleanest expression at 4.92%, the fattest premium of the index book, though the Negative Gamma backdrop means the payout profile is trend-prone rather than mean-reverting - express the short-vol view via SPY/QQQ structures, not IWM naked premium.
VIX VRP at -14.55% stays negative - vol-of-vol underpriced against realized VVIX churn, so VIX call convexity remains cheap tail insurance. Pair the short-index-premium carry with a small VIX call overlay; the asymmetry funds itself while VVIX at 87.83 holds the Low regime.
What it means for your trading
Premium sellers earn 0.7% on SPY and 1.57% on QQQ against realized floors, while IWM's 4.92% VRP is richest but sits in a Negative Gamma regime that flips the payout geometry. Sell index premium in the 21-30 DTE window, hedge tail with cheap VIX calls given negative VIX VRP.
Skew Convexity
SPY quarter-delta skew prints 1.07% with smile ratio 1.14% - an orderly downside bid, not a panic curve. Put-wing IV at 8.48% against ATM at 8.23% reflects measured protection demand, consistent with dealers absorbing hedge flow into a positive-gamma book rather than repricing tail insurance.
Call-wing IV at 7.41% trades below ATM - dealer overhead supply caps upside convexity and kills any topside chase. Put spreads dominate the risk/reward math: naked puts overpay for a tail nobody is bidding, while defined-risk verticals harvest the modest downside premium without leaking vega into a suppressive vol regime.
Cross-asset tells the fragility story. QQQ smile ratio at 1.2% runs steeper than SPY, tech carrying a heavier hedge bid. IWM quarter-delta skew at 0.87% stays flat despite the Negative Gamma regime - the left tail is underpriced, making outright IWM puts the cleanest asymmetric expression of small-cap fragility.
What it means for your trading
Skew signal reads Skew Steep: express SPY downside through put spreads to avoid overpaying an unbid tail, and use IWM outright puts where flat skew undersells the Negative Gamma regime.
Vol-of-Vol Structure
VVIX at 87.83 against VIX 14.80 pins the ratio at 5.93 - squarely in Low territory. No bimodal pricing, no jump premium being demanded, and the vol-of-vol tape eased -3.03% into the bell alongside spot vol compression. The regime signal prints Green.
Practically, this is a green light: convexity buyers aren't paying up for VIX call wings, so tail insurance stays cheap - carry the hedges you'd normally skip. On the sell side, sizing guidance holds at Standard Size; premium sellers operate at full weight into the 21-30 DTE window without a vol-of-vol tax.
Watch the ratio, not the absolute - a VVIX pop with VIX static is the first tell that jump risk is being re-priced and sizing needs to tighten.
What it means for your trading
With VVIX/VIX at 5.93 and the regime tagged Low, run Standard Size on short-vol structures while layering cheap VIX call convexity as tail insurance.
Dispersion Spread
SPY ATM IV at 11.38% sits well inside QQQ's 17.21% - a vol-point spread that isn't index risk, it's dispersion. Cross-strike dispersion of 32.72 against cross-expiry 3.39 confirms the width lives in the smile, not the term - component vol is doing the work while index vol gets diluted by correlation.
Today's mover stack is concentrated: MSFT and META carry the largest positive GEX shifts, with AAPL and NVDA behind them. That concentration is exactly the mechanic suppressing SPX vol below component-weighted fair value - index premium reads cheap on a look-through basis even as single-name convexity stays bid.
Trade the asymmetry directionally: sell index premium where dealer gamma cushions the tape, then buy back single-name convexity selectively in the mega-cap leaders if hedges are needed. Dispersion signal reads Moderate - meaningful edge, not a full-throttle print.
What it means for your trading
Elevated single-name vol against suppressed index vol favors structural SPX/SPY premium selling with tactical long convexity in MSFT or NVDA; dispersion at Moderate supports the trade without demanding size.
Liquidity & Microstructure
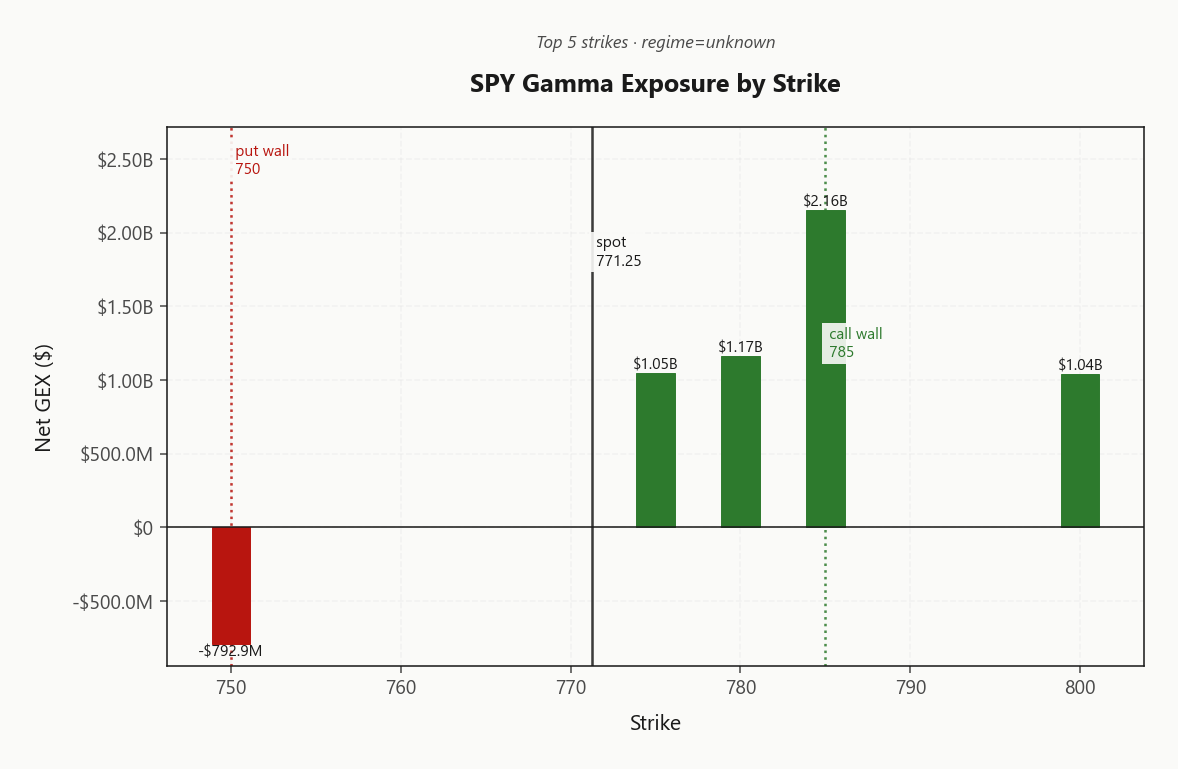
The book anchors on 500 as the deep-liquidity magnet, with the call wall at 785.00 capping upside and the put wall at 750.00 floor-ing the downside. Spot at 771.25 sits inside the corridor, and the top strike at 785.00 carries $2.16B of net gamma - the dominant hedging magnet dealers defend into every reversion.
The put wall at 750.00 is the first line of defense; losing it flips dealer flow from mean-reverting to trend-accelerating and pulls the tape toward the flip zone at 760. Max pain sits at 760.00, biasing pin behavior into the weekly. Gamma flip status prints Stored Sign Mismatch - the level is unresolved, but the wall structure keeps the regime cushioned as long as spot holds inside the range.
Trade the corridor: fade rips into 785.00, buy weakness toward 750.00, and treat a close outside either wall as the regime break signal.
What it means for your trading
Deep-liquidity walls at 785.00 and 750.00 frame a mean-reversion tape with spot at 771.25 inside the corridor; the put wall is the tripwire - lose it and dealer flow inverts into the 760 pivot.
Trading readGamma stacks positively across upside strikes with the call wall as the ceiling and put wall as the floor - dealer hedging dampens moves inside the range, so fade strength into the wall and buy weakness toward the floor until a wall breaks.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
SPY's positive gamma cushion is a conditional shock absorber, not a structural one. Net VEX prints -$108.24B - a deeply negative vanna book that converts dealers into delta sellers the moment vol lifts. As long as VIX stays contained at 14.80 and VVIX at 87.83, the gamma dampening holds; a repricing higher flips the same book from stabilizer to accelerant. That is the asymmetry to respect when sizing short-premium against the wall structure.
Loss of 760 tips dealer bias negative and stacks with the VEX profile - that is the sequence to trade, not the current print.
What it means for your trading
Positive gamma is real but conditional on VIX at 14.80 and VVIX at 87.83 staying contained; VEX of -$108.24B means a vol spike inverts the hedging flow. Watch 760 - a break flips charm bias from Neutral to negative and compounds the vanna risk.
Cross-Asset Confirmation
The index complex closes bifurcated: SPY holds a positive gamma cushion while QQQ tracks Positive Gamma and IWM prints Negative Gamma - the regime split (True) is the day's cleanest asymmetry, flagging small-cap fragility beneath a stable mega-cap tape. Cross-asset tone reads Unknown, with MOVE at 104.58 confirming no credit-side spillover - the Iran/oil geopolitical premium is fading, not repricing rates.
QQQ closes at 744.50 against IWM at 282.07 - the small-cap underperformance is embedded in flow, not headline-driven, which makes IWM the fragile leg on any macro shock. Fear & Greed reads Fear at 37, sentiment lagging the tape recovery - a contrarian tailwind for continuation while retail stays under-positioned.
Trade the split: mean-revert mega-caps into walls, respect trend in IWM.
What it means for your trading
Regime divergence (True) with MOVE contained at 104.58 says this is a positioning story, not a credit event - express short-vol via SPY/QQQ, treat IWM as the tell for regime break.
Scenario EV
Regime prints Low / Carry with VIX at 14.87 and forward vol Steep Contango - the setup pays defined-risk premium sellers in the 21-30 DTE window where theta accrual clears management runway. Scenario score reads Red, so lean on manual synthesis: iron condors on SPY anchored outside 785.00 and 750.00, calendars on QQQ to harvest the 19.1801564123 roll-down against front-month decay.
VRP prints 0.7% on SPY and 1.57% on QQQ - both real premium against realized, both express cleanly inside Positive Gamma dealer cushion. IWM VRP at 4.92% looks richest on the tape but sits inside Negative Gamma - the losing side compounds against you as dealers sell weakness, so skip small-cap short premium regardless of the carry math.
Sizing runs Standard Size with VVIX/VIX at 5.93 - no bimodal jump premium being paid, full weight authorized. Watch 760 as the flip zone.
What it means for your trading
Sell SPY iron condors and QQQ calendars in the 21-30 window at Standard Size; avoid IWM short premium and keep cheap VIX call convexity as tail protection while VVIX at 87.83 stays affordable.
Actionable Summary
Regime tags Low / Carry with VIX at 14.80 and VVIX at 87.83 - the carry setup is live, and the Steep Contango term structure pays sellers on both theta and roll-down. Anchor SPY and QQQ iron condors in the 21-30 DTE window, placing short strikes outside the 785.00 call wall and 750.00 put wall where dealer hedging fades excursions back into the range.
Fund the tail with cheap VIX call convexity while VVIX sits at 87.83 - vol-of-vol isn't pricing a jump, so insurance is on sale. Avoid naked short IWM premium: the Negative Gamma regime amplifies the losing side and inverts the mean-reversion cushion that supports the mega-cap trade.
Watch 760 on SPY - a break flips dealer bias and unwinds the Unknown cushion. Cut size if VVIX presses above 87.83; vol-of-vol expansion is the first tell that the carry window is closing.
What it means for your trading
Sell defined-risk premium on SPY and QQQ inside the wall structure, hedge the tail cheaply through 14.80 VIX calls, and steer clear of IWM shorts while the charm pivot at 760 holds.
Trump-Xi diplomatic exchange over Iran-China alignment lowers geopolitical risk premium - supports the compressed VIX and steep contango setup, reduces tail-hedge demand at the margin.
Iran refusing nuclear concessions is the counterweight to the diplomatic thaw - keeps oil and MOVE from fully unwinding geopolitical premium, prevents the tail from getting priced out entirely.
10-year yield hitting a 19-year high is the quiet macro pressure under the tape - rate-sensitive small-caps explain IWM's negative gamma while mega-cap cash-cows keep the index steady.
Weekly wrap narrative confirms SPX and Nasdaq on track for winning weeks - validates the carry regime and sets the psychological anchor for continuation into next session.
Oil sliding on US-Iran de-escalation exploration removes a live tail catalyst from the vol surface - reinforces short-vol carry setup and takes energy-driven index whip off the table.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.87 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $3.21B. The gamma flip sits at N/A, with the call wall at 785.00 and the put wall at 750.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 771.25. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.38% with a volatility risk premium of 0.7%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.80. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime