Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 764.65 trades below the 768.04 gamma flip - dealers are short gamma with net GEX at -$6.96B, so intraday moves get amplified rather than pinned. Call wall sits at 770.00, put wall at 760.00, and the flip acts as the pivot: reclaim it and dealer buying supports the tape, lose the put wall and vanna sells into weakness. Net vanna at -$44.74B means a vol spike accelerates the downside - this is the destabilizing bias flagged by Destabilizing. VIX at 15.75 with Contango term structure and VVIX at 90.20 says vol sellers still get paid, VRP at 0.92% confirms the premium. Fear & Greed at 33 (Fear) plus MOVE at 95.45 - rates vol repricing hard - is the divergence to watch. Bottom line: sized-down Iron Condor in the 30-45 DTE window, avoid naked short vol in front-week where 0DTE gamma at 26.1%% amplifies whipsaws, and treat 768.04 as the line - trade only from confirmed side.
Negative gamma across index complex with spot below flip - dealer flow destabilizing, VIX contango still supports vol carry
SPY at 764.65 trades below the 768.04 gamma flip with dealers net short gamma across SPY, QQQ and IWM - moves get amplified, not dampened. Yet VIX term structure holds Contango at 17.99%% near slope and VVIX at 90.20 sits in a normal jump-risk band, so vol sellers keep the structural carry even as the tape trades fragile. The tell is MOVE at 95.45 - rates vol has re-priced hard while equity vol sleeps, and that gap is the risk to underwrite today.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
764.65
768.04
-0.44%
770
760
760
-$6.96B
Short gamma
QQQ
736.84
738.07
-0.17%
740
736
723
-$3.31B
Short gamma
IWM
280.72
290.88
-3.49%
290
280
288
-$4.95B
Short gamma
VIX
15.75
16.23
-2.97%
20
15
19.50
-$15.19M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.76
10.84
+0.92
1.66
2.24
1.10
QQQ
17.18
16.19
+0.99
1.93
1.43
0.99
IWM
17.11
12.92
+4.19
1.55
2.32
3.16
VIX
77.09
100.99
-23.90
-126.30
0.31
3.51
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
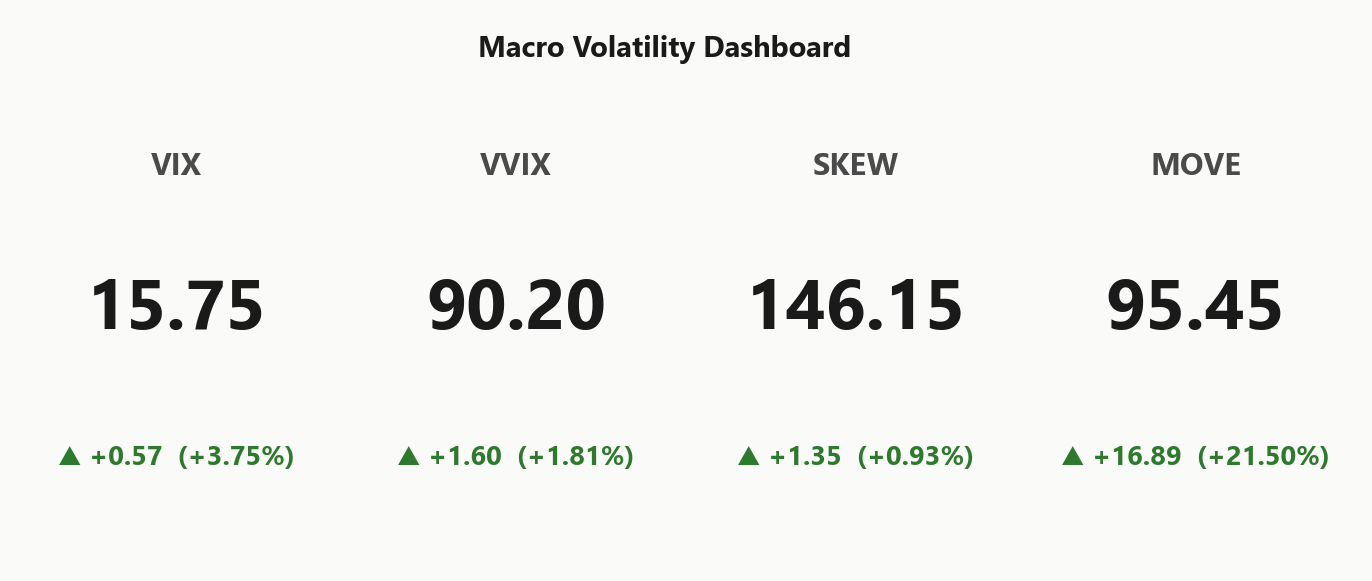
VIX
15.75
+3.75%
VVIX
90.20
+1.81%
SPX
7,675.51
-0.40%
SKEW index
146.15
+0.93%
MOVE (bond vol)
95.45
+21.50%
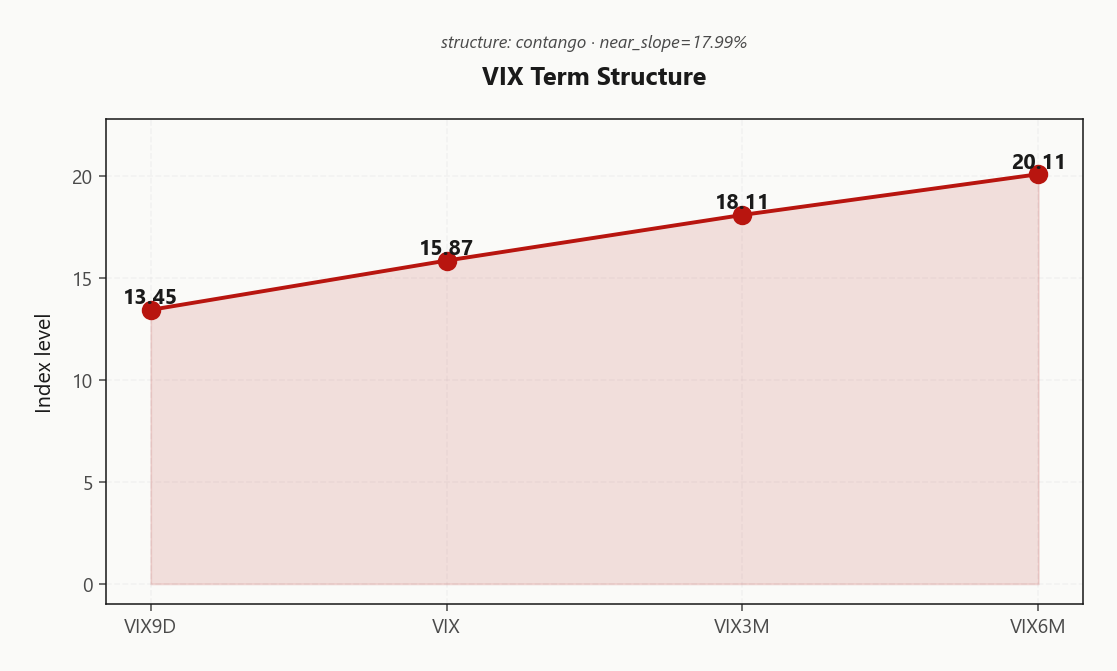
VIX term (9d/30d/3m/6m)
13.45 / 15.87 / 18.11 / 20.11
Steep contango
VVIX / VIX
5.73
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX anchored at 15.75 and a half-life of 15 sessions - this tape is sticky, not transitional. Trade the regime, don't fade it. Path probability to a lower-vol print in ten sessions runs 0.45, which keeps the structural bias toward short-vol carry over reflexive long-vol hedges.
The tail is 0.05 to panic in five sessions - small, but not zero, and that is the sizing constraint. Position the vol book to survive the jump, not to maximize the base case. The compression risk to the sticky read is the 95.45 MOVE print running hot against a placid 15.75 VIX; if rates vol keeps leading and equity vol catches up, the half-life shortens fast.
Bias: run the carry, cap the size, and treat the 768.0415842848 pivot with Destabilizing dealer flow as the line that flips the regime read.
What it means for your trading
Elevated / Watchful with a 15-session half-life - carry the short-vol book, but size for the 0.05 tail and treat MOVE-to-VIX convergence as the trip-wire that shortens the regime.
Trading readVIX quiet, VVIX normal, SKEW at 146.15, MOVE at 95.45 - equity vol suite in agreement, rates vol screaming; that mismatch usually resolves toward the noisier signalVIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
VIX9D at 13.45 sits well beneath VIX at 15.87, which then steps up to VIX3M at 18.11 and VIX6M at 20.11 - the curve is Steep Contango end to end with near-slope at 17.99%%. Front-week vol sellers keep the roll intact, and the structural carry favors the short side of the term curve.
The steepness itself is the tell. The market is not paying for near-term event risk - it is paying for distant risk. Forward 30-to-60 at 19.1319026759 and forward 60-to-90 at 21.9283401105 mean medium-term hedges remain cheap relative to how much term premium is already built into the back end. The Steep contango - vol sellers favored read makes calendar spreads - not naked strangles - the cleaner expression.
Best edge sits in the 30-45 DTE bucket where forward vol at 19.1319026759 monetizes the roll-down without exposing the book to front-week gamma amplification. Sell the short wing, buy the 30-45 DTE leg, and let the contango do the work.
What it means for your trading
Term structure is Steep Contango with forward 30-to-60 at 19.1319026759 - the roll pays vol sellers, but the market's pricing of distant-only risk argues for calendar spreads over naked short vol.
Trading readContango with 17.99%% near-slope pays the vol carry trade - front-month VIX futures at 18.11 vs spot 15.87 means shorts get the roll-downForward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY HV20 at 10.84 against ATM IV at 11.76% leaves VRP at 0.92% - premium is present but thin. Short-vol still pays on the index, but the cushion is narrow and sizing has to respect it, particularly with dealer bias reading Destabilizing below the flip.
The standout is IWM: HV20 at 12.92 versus ATM IV at 17.11% prints VRP at 4.19% - small-cap options are paying up far beyond what realized has delivered. QQQ sits in between at 0.99%, less compelling than IWM and not rich enough to press. The core complex ranks cleanly: IWM richest, SPY thin, QQQ mid.
Structural tell: SPY HV60 at 11.24 sits above HV20, so recent tape is a vol compression, not acceleration - the realized backdrop that lets the carry work even with spot below 768.04. Actionable: concentrate the short-vol book toward IWM in the 30-45 DTE window; keep SPY exposure trimmed.
What it means for your trading
IWM VRP at 4.19% is the richest short-vol venue in the complex; SPY at 0.92% pays but requires sized-down carry, and the HV60-over-HV20 shape confirms compression rather than acceleration.
Skew Convexity
SPY quarter-delta skew at 1.66% with put-25d IV at 14.9% against call-25d at 13.24% - the downside bid is ordered, not panic. Smile ratio at 1.13% versus ATM at 13.21% puts wings only modestly above the belly. Traders are hedged, not scared - and that shape argues for put spreads over naked long puts, since the left wing is already paying for itself.
The call side reads inverted-flat - zero upside conviction priced in. Chasing rallies via long calls isn't being subsidized by skew; if anything, dealer supply above the flip caps the payoff. Sell the calls to finance the puts, or express directional downside through vertical spreads rather than outrights.
Cross-check IWM: smile ratio at 1.08% shows a richer left tail than SPY - own protection there if hedging small-cap beta, not at the index. Note the 2-DTE reads can exaggerate weekend and event distortion; validate the shape at the 30 DTE profile before sizing the hedge.
What it means for your trading
Skew at 1.66% and smile ratio at 1.13% describe a hedged, not fearful, tape - trade downside via put spreads and route small-cap protection through IWM where the left tail at 1.08% is richer.
Vol-of-Vol Structure
VVIX at 90.20 with the VVIX/VIX ratio at 5.73 sits squarely in the Normal band - no bimodal jump-risk premium priced into the tape, no bid for convex vol-of-vol structures. Sizing guidance is Standard Size: this is the single reason short-vol carry remains viable while dealer gamma is destabilizing at the index level.
The tell is asymmetric. VVIX printing quiet in absolute terms would be one story; the ratio at 5.73 against VIX at 15.75 says the market still pays up for the tail even inside the calm - vol-of-vol has not collapsed, it has just refused to accelerate. Underwrite the carry, but treat the triple-digit VVIX threshold as the trip-wire: a break there forces half-size or flat across the iron condor book, regardless of what VIX itself is doing.
VVIX change on the session: 1.81% - noise, not a signal shift.
What it means for your trading
Normal vol-of-vol at 90.20 keeps full sizing on the carry structures viable, but the VVIX/VIX ratio at 5.73 shows the tail is still being paid for - a break above the triple-digit VVIX threshold flips the calculus and forces immediate size reduction.
Dispersion Spread
Index vol is running notably suppressed against the single-name proxies - SPY ATM IV at 11.76% versus QQQ at 17.18% and IWM at 17.11%. Correlation is doing the heavy lifting at the index level, which is exactly why SPY/SPX remains the preferred short-vol venue while the complex sits in negative gamma. The IWM-to-SPY IV spread is the widest gap in the core book - that is where the richest short-premium venue lives, and where an iron condor monetizes both VRP and the wider wing pricing.
The setup is not a classic dispersion trade. Long single-name vol against short index vol only pays when correlation is breaking down and single names lead the tape - with the regime Aligned across SPY, QQQ and IWM, correlation is holding and index vol is the protected leg. Selling single-name vol into a divergent negative-gamma regime is the wrong direction of risk - the index absorbs the beta shock, the single names amplify it.
What it means for your trading
Pair the short-vol book toward IWM where the IV premium over SPY is widest and VRP is meaningfully thicker; leave dispersion off the table until the complex breaks out of an Aligned negative-gamma regime.
Liquidity & Microstructure
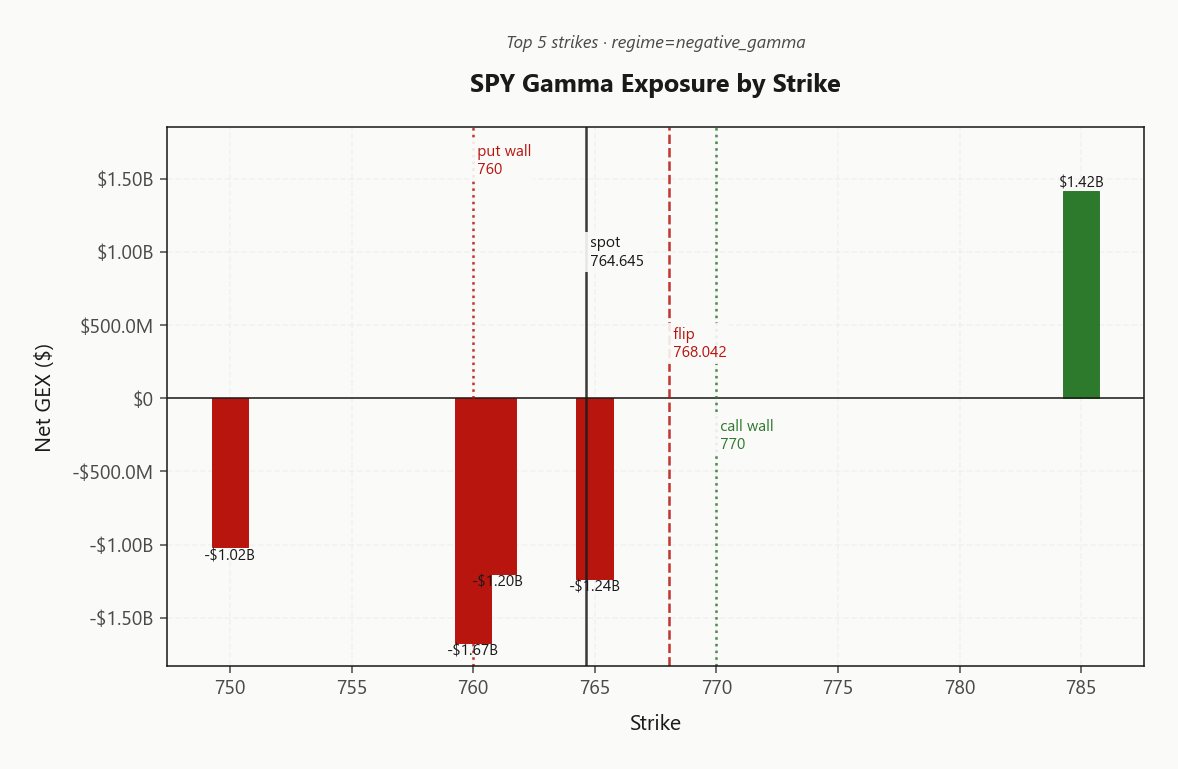
SPY at 764.65 trades below the 768.04 gamma flip - dealer hedging is destabilizing, not stabilizing, and every intraday move gets amplified rather than pinned. Reclaiming the flip is the whole game: above it, dealers buy weakness and sell strength; below it, the mechanics invert and the tape sells its own weakness.
The put wall at 760.00 is the last real support before gamma amplification kicks in - the 760.00 strike carries net GEX at -$1.67B, and that is the accelerator zone on a breach. On the top side, the call wall at 770.00 caps rallies as dealers sell into strength; treat it as resistance backed by real flow, not a chart line.
Ignore the top OI print at 500 - that is LEAP concentration, not spot-relevant navigation. The strikes that matter today are the put wall below and the call wall above; trade only from the confirmed side of 768.04.
What it means for your trading
Spot below 768.04 converts dealer flow from stabilizer to accelerant, with the put wall at 760.00 as the trigger and the call wall at 770.00 as the ceiling. Reclaiming the flip is the only clean path back to a supportive tape.
Trading readWith spot below the flip, the gamma landscape says dealer flow amplifies moves in BOTH directions until price reclaims 768.04 - the put wall at 760.00 is the true support, not a technical level; below it the tape sells its own weaknessNet dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
The single level that matters is the gamma flip at 768.0415842848. Current dealer bias reads Destabilizing, and until spot reclaims that pivot, the vanna channel dominates - every uptick in implied vol trades as a spot down-draft. Reclaim it and the same dealer book flips to stabilizing; lose separation from it and the vol-to-spot beta only widens.
Layer on 0DTE gamma at 26.1%% of total book and the intraday whipsaw sits on top of an already destabilizing structural bias. Trade only from the confirmed side of the flip, and treat any VVIX expansion as an immediate sizing signal, not a lagging one.
What it means for your trading
Vanna-dominated tape with spot below the 768.0415842848 flip and bias Destabilizing - a VIX uptick mechanically sells spot lower via dealer hedges, and the 0DTE layer at 26.1%% amplifies the swing. Reclaiming the pivot is the one gate that flips the regime constructive.
Cross-Asset Confirmation
MOVE at 95.45 up 21.5%% is the lead - rates vol has repriced hard while VIX at 15.75 barely flinches. That gap is the trade: equity vol is under-pricing what the bond tape is already telling you, and the resolution usually runs toward the noisier signal.
Cross-equity reads are Aligned - SPY, QQQ at 736.84 and IWM at 280.72 all sit in negative gamma. No rotation to fade, no pair setup - this is a beta shock signature with bond selloff pre-Trump/Xi and oil bid stacking on top. Fear & Greed at 33 (Fear) reads contrarian bullish on the medium horizon, but tactically positioning is already defensive and the risk-off tell dominates.
Watch TLT and HYG for the confirmation leg - credit spreads widening is the pathway that forces equity vol to catch up to rates vol, and that's when the divergence collapses.
What it means for your trading
Rates vol has moved, equity vol hasn't - with cross-equity regimes Aligned in negative gamma, the asymmetric setup is the MOVE-VIX gap, not any single index. Credit is the tripwire.
Scenario EV
Scenario EV points to Iron Condor with a composite score of 41, outranking the put spread alternative at 26. The edge is structural: VRP at 0.92% is present but not extreme, VVIX at 90.20 sits in the Normal band, and Contango pays time decay on both wings simultaneously. The 30-45 DTE window is where that math compounds cleanly.
Put spreads score lower because skew at 1.66% has already priced the implied downside - you're paying for protection the tape has bid up. The iron condor monetizes both wings without that skew tax. Avoid naked short vol in the front week: 0DTE gamma at 26.1%% of total is where dealer amplification does the most damage, and dealer bias reads Destabilizing with spot below 768.0415842848.
Sizing discipline is non-negotiable - tail risk is not zero while the flip is unreclaimed. Roll shorter wings only once VVIX confirms stability, and treat any VVIX break as the trigger to halve the book.
What it means for your trading
Iron condor in the 30-45 DTE window at standard size - the setup where Contango and Normal vol-of-vol pay for both wings without gamma pain. Cut size or step aside if dealer bias stays Destabilizing and VVIX breaks its calm band.
Actionable Summary
Regime reads Elevated / Watchful with dealer bias Destabilizing and spot pinned below the gamma flip at 768.0415842848. Reclaim it and dealer flow stabilizes the tape; lose the put wall and vanna sells into weakness. Trade only from the confirmed side of that line - this is not a level to fade, it is the switch for the entire regime.
Optimal structure is Iron Condor in the 30-45 DTE window at standard size, monetizing VRP without eating gamma pain. Best carry venue is IWM where VRP at 4.19% dwarfs SPY at 0.92%; best hedge is calendar spreads harvesting front-end contango. Avoid naked short vol inside the front week and single-name short vol into an aligned negative-gamma complex.
Watch three trip-wires: SPY reclaim of 768.0415842848 flips the regime constructive; VVIX crossing 100 forces size reduction across the vol book; and the 95.45 MOVE-versus-15.75 VIX gap is the rates-to-equity contagion tail.
What it means for your trading
Sized-down Iron Condor in the 30-45 DTE window is the paid trade while 768.0415842848 caps the regime; IWM carries the richest VRP and calendars harvest the Contango contango.
Trump-Xi summit + Meta hardware event = one macro geopolitical risk, one mega-cap positioning catalyst - both can dominate the tape independently of the underlying options structure
Family office pivot from tariff-worry to inflation-worry aligns with the MOVE spike - institutional positioning is repricing rates risk, and equity vol lags the reprice
Oil bid on stalled Iran talks = inflation pass-through risk that keeps the Fed hawkish that keeps yields bid that keeps MOVE elevated - the causal chain running through the tape today
Yesterday's Wall Street close on rising yields and oil sets today's opening tone - regime continuation, not regime reset
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.75 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 768.04 against a spot of 764.65. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.76% with a volatility risk premium of 0.92%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.75. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime