Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 767.10 sitting 0.0718104058% under the gamma flip at 767.65, net GEX at -$1.58B = dealers short gamma and forced to amplify direction on any breach. Call wall 770.00 caps upside, put wall 765.00 is the reflexive support - a break of 765.00 accelerates on dealer sell-hedging. Dealer positioning is destabilizing: charm pivot flags Destabilizing bias, vanna exposure -$69.17B means a vol spike compounds delta selling. VIX at 15.64 with term structure Contango and VVIX at 90.11; VRP 0.92% says carry is thin on SPY but IWM at 4.56% pays. Bottom line: fade rallies into 770.00, respect 765.00 as the trigger - trade iron condors on IWM where VRP is fat, avoid naked SPY short strangles until spot reclaims flip.
Negative gamma across index complex with SPY pinned at flip 767.65; destabilizing charm regime
The index complex is uniformly short-gamma with SPY and QQQ mechanically pinned at their flip levels while IWM sits well below its 291.71 pivot. VIX term structure remains in steep contango even as MOVE surged 21.5%%, signaling bond-vol stress that has not yet migrated to equity vol. Iron condors are the structure of choice - VRP is bid but vol-of-vol at 5.76 still supports standard sizing.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
767.10
767.65
-0.07%
770
765
760
-$1.58B
Short gamma
QQQ
739.51
739.61
-0.01%
740
736
723
-$872.96M
Short gamma
IWM
281.15
291.71
-3.62%
290
280
288
-$4.79B
Short gamma
VIX
15.65
16.27
-3.83%
20
15
19.50
-$21.30M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.86
10.94
+0.92
1.12
2.24
1.09
QQQ
17.35
16.25
+1.10
0.43
1.43
0.96
IWM
17.49
12.93
+4.56
-1.14
2.32
1.74
VIX
76.07
101.63
-25.56
-128.27
0.31
0.42
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
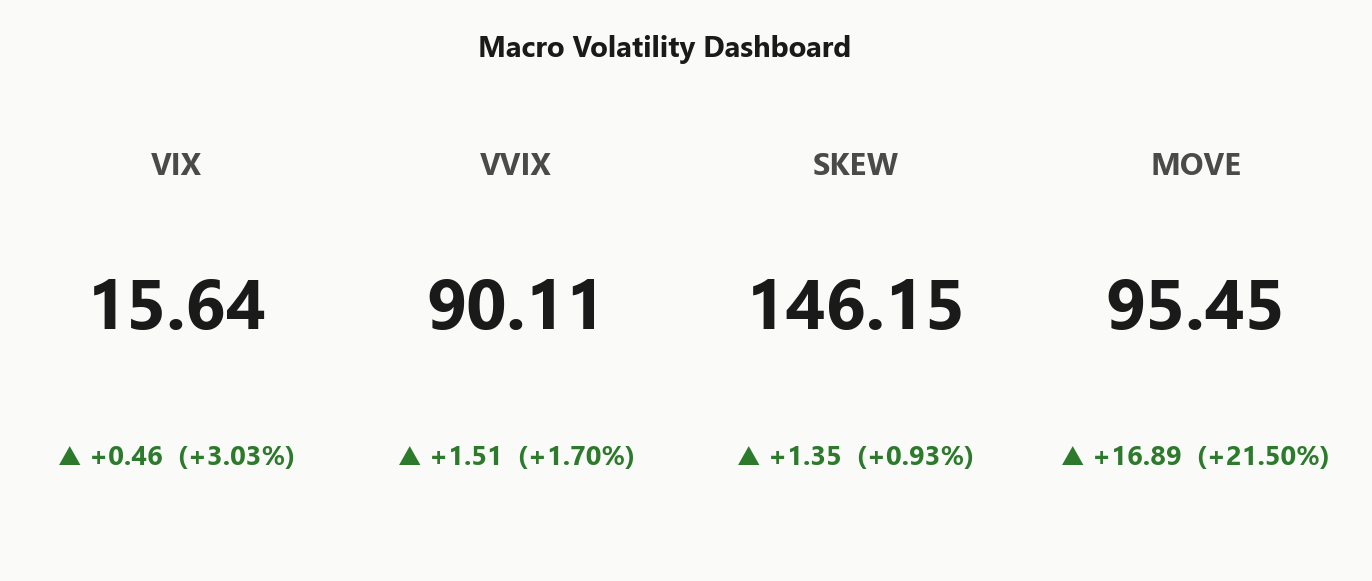
VIX
15.64
+3.03%
VVIX
90.11
+1.70%
SPX
7,701.59
-0.06%
SKEW index
146.15
+0.93%
MOVE (bond vol)
95.45
+21.50%
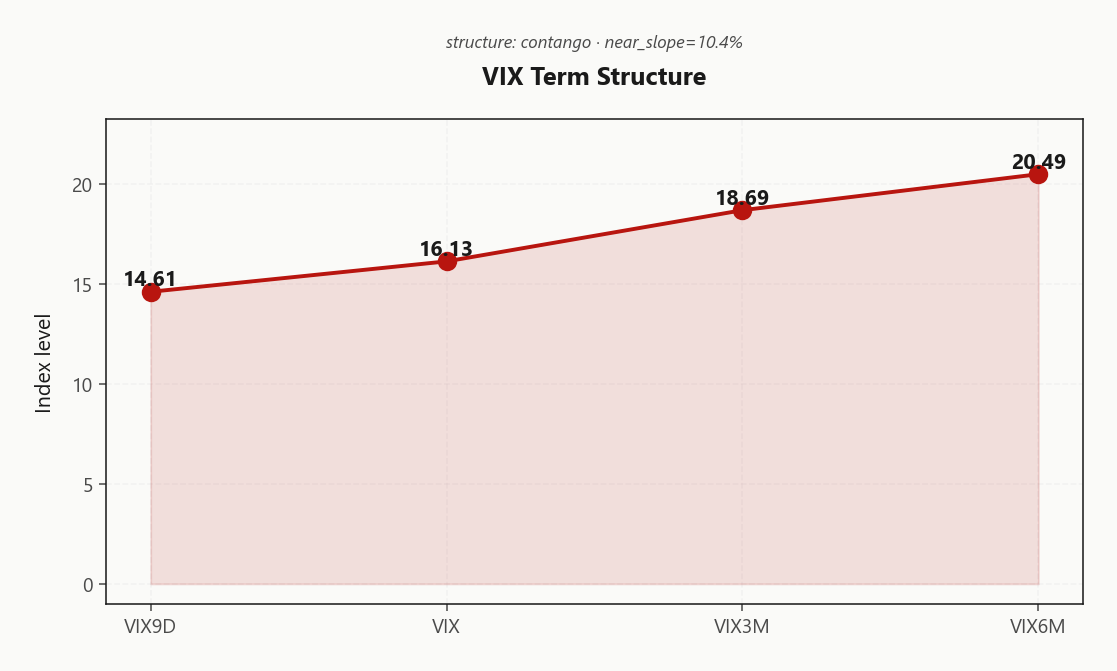
VIX term (9d/30d/3m/6m)
14.61 / 16.13 / 18.69 / 20.49
Steep contango
VVIX / VIX
5.76
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape is holding an Elevated / Watchful regime with VIX printing 15.64 - no panic priced, no reversion imminent. Five-session panic probability sits at 0.05 and the ten-session drift-back-to-calm probability is 0.45. Neither tail is dominant; the base case is grind, not resolution.
Half-life clocks 15 sessions - sticky. Position for a two-week horizon, not intraday theta chase. Sizing frameworks anchored to a same-day mean-revert will misprice this tape; the regime persists long enough that carry compounds and gamma exposure accrues.
Signal reads yellow - watchful, not defensive. Keep dry powder for a VVIX/VIX ratio migration or a curve inversion; those are the leading tells that flip the state before spot does. Trade the range, respect the pivot, and let the half-life do the work.
What it means for your trading
Elevated regime at VIX 15.64 with a sticky 15-session half-life - size for two weeks, not intraday. Yellow signal: watchful but not defensive, and the base case is persistence, not resolution.
Trading readMOVE surging while VIX barely moves is the divergence to trust - bond vol leads equity vol into rate-driven episodes, and the equity market has not yet caught up.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is anchored in Contango with VIX9D at 14.61 printing well beneath spot VIX 16.13 and 3M VIX 18.69. Event premium beyond the quarter is being paid while the front end stays calm - a classic Steep Contango shape that hands structural short-vol carry to sellers in the front two months.
Forward 30/60 vol at 19.846553857 prints above spot IV, meaning the tape is pricing a gradual re-vol into Q4 rather than an immediate shock. The belly at 30-45 DTE is where carry is fattest and gamma leakage is thinnest - the textbook window for premium harvest.
The catch: front-slope of 10.4%% is the shape most exposed to a bond-vol pass-through, and MOVE at 95.45 is already flashing divergence. Contango can invert on a single hawkish session - size the belly, don't lean on the wings.
What it means for your trading
Steep Steep Contango keeps the 30-45 DTE belly the cleanest carry window, but the shallow near-slope leaves the curve one MOVE follow-through away from inversion.
Trading readContango holds but the front slope is flattening - vol carry is available, but the market is quietly conceding that a mid-curve pop is possible.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY realized is cooling into a soft implied bid. RV20 prints 10.93 against ATM IV at 11.86%, and the tighter RV5 window at 13.83 still trades under implieds. The IV/RV spread reads Thin Premium - options are richer than the tape has actually delivered, but with VRP at 0.92%, sellers are paid modestly rather than lavishly. SPY-native premium harvest has to be size-selective.
IWM is where the carry actually lives. Realized has compressed while ATM IV at 17.49% holds firm, generating a VRP at 4.56% - the richest premium in the index complex today. Small-caps are the clean vehicle for premium harvest; index-native short strangles do not pay for the negative-gamma tape they overlay.
Realized deceleration on SPY still favors sellers on paper, but the setup is fragile. A MOVE-driven cross-current could reprice IV higher and invert the carry inside a session - route the trade through IWM iron condors where the VRP cushion is real, not through naked SPY structures.
What it means for your trading
IWM offers the cleanest VRP harvest in the complex while SPY's thin premium at 0.92% demands selectivity. Realized deceleration favors sellers but a MOVE-driven vol re-price could reverse the edge quickly.
Skew Convexity
SPY quarter-delta skew prints 1.12% with a smile ratio of 1.08% - put wing bid over calls but well inside tail-panic territory. Put-25d IV at 15.23% sits modestly above ATM 14.66%, while call-25d clears at 14.11%. Downside is ordered, not scrambled: the market wants protection but is not paying up for convexity.
IWM breaks the pattern. Small-cap 25d skew flips to -1.14% - calls bid over puts, the fingerprint of squeeze positioning ahead of a repricing higher. That inversion sits uneasily against a uniformly short-gamma index tape and MOVE spiking 21.5%, meaning the small-cap chase is being priced without a matching hedge bid.
Structure implication: ratio spreads over naked puts on SPY where the wing is not paying enough to justify unhedged convexity, and lean IWM call-side flow - sell the inverted skew rather than fight it. The tail is polite; do not overpay for it.
What it means for your trading
SPY skew is downside-tilted but orderly at 1.12%, while IWM's inverted skew at -1.14% flags a small-cap squeeze bid - favor ratio structures over naked puts and route premium into the IWM call skew rather than chasing SPY tail convexity.
Vol-of-Vol Structure
VVIX prints 90.11 against VIX at 15.64, putting the ratio at 5.76 - squarely in the Normal band. No bimodality is being priced: the tape is not paying up for a vol-crush and it is not paying up for a spike either. Jump risk is ordered, not extreme.
That reading unlocks Standard Size across the premium-selling book. Iron condors, calendars, and short strangles can be run at full weight - the vol-of-vol tax that would otherwise force half-size is absent. The green signal on this axis is what makes the Iron Condor recommendation carry-viable despite the destabilizing charm pivot elsewhere in the stack.
The migration to monitor is the ratio itself. A push through the mid-sixes flips the regime - bimodality returns, sizing must be halved, and any short-vega structure inherits a convex tail. Until then, treat vol-of-vol as the one green light in an otherwise yellow-and-red greek complex.
What it means for your trading
Vol-of-vol at 5.76 is the permission slip for Standard Size - run the condor book at full weight, but watch the ratio for any escalation that would force a mid-session downshift.
Dispersion Spread
SPY ATM IV at 11.86% prints materially below QQQ 17.35% and IWM 17.49% - index vol is suppressed against single-name and small-cap surfaces, and the SPY-to-IWM gap is the widest we've seen in weeks. Cross-strike dispersion at 73.43 corroborates: the smile is doing the work the index tape refuses to.
Dispersion tilts short single-name, long index. Correlation sits in the moderate band, meaning SPY hedges will not offset idiosyncratic single-stock shocks - a critical caveat with mega-cap earnings crowding the QQQ book. Route small-cap premium into the fat side of the surface and let index vol underwrite the wing.
Preferred structure: SPY iron condor paired with an IWM strangle, sized standard given Standard Size regime. Avoid QQQ dispersion outright - mega-cap earnings positioning is too crowded to trust the vol premium, and the single-stock leg carries asymmetric event risk that index shorts cannot absorb.
What it means for your trading
Index vol at 11.86% is the cheapest leg in the complex while IWM carries the richest premium - the dispersion trade is short single-name / long index, executed through an SPY iron condor and IWM strangle, with QQQ sidelined on earnings crowding.
Liquidity & Microstructure
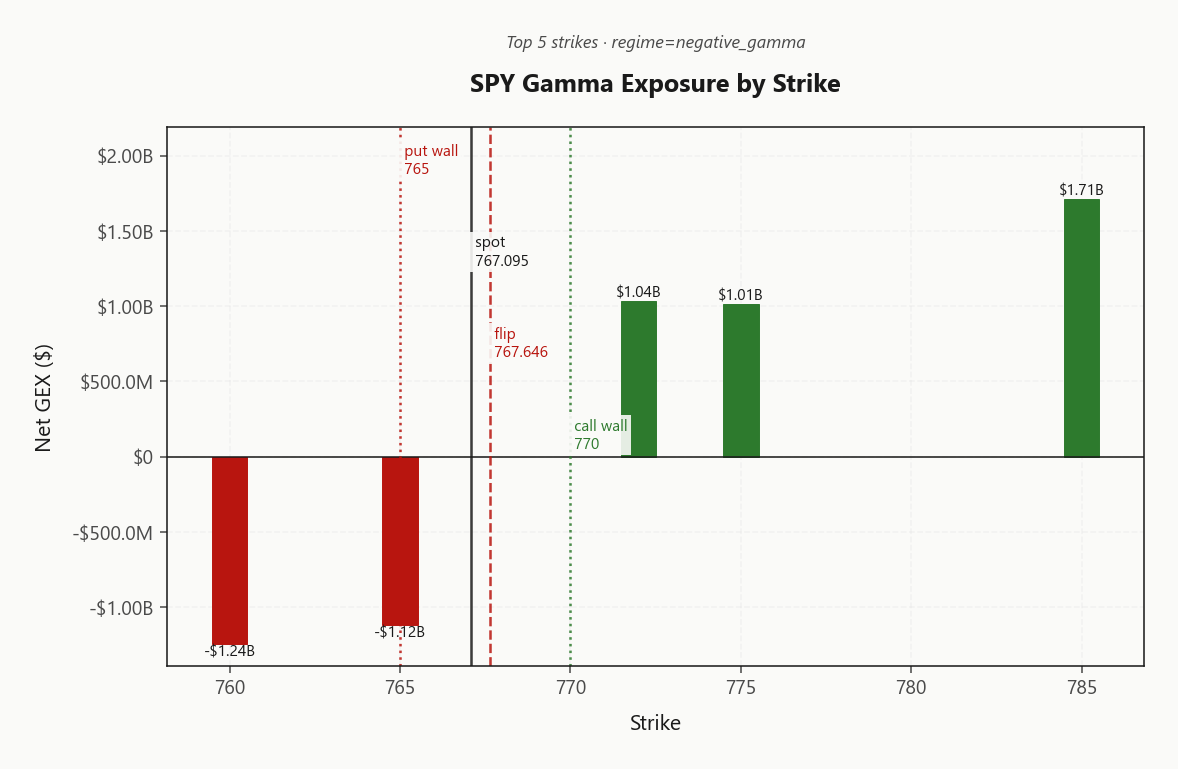
SPY spot at 767.10 is pinned 0.0718104058% under the gamma flip at 767.65 - every tick is a pivot decision and dealers are on the fragile side of the book. The top strike sits above spot at 785.00 carrying $1.71B of positive gamma, the magnet that caps rallies before the 770.00 call wall.
Below spot, the reflexive support is the put wall at 765.00 - the level where dealer sell-hedging accelerates and the negative-gamma feedback loop takes hold. A clean break there is not a mean-reversion setup; it is a mechanical amplifier.
Highest OI sits far below at 500, a legacy protective cluster - not today's magnet. The tape is engineered around the 765.00 - 770.00 corridor with the flip as the hinge; fade rallies into resistance, respect the put wall as the trigger.
What it means for your trading
Spot pinned 0.0718104058% beneath the flip at 767.65 leaves the book mechanically fragile between the 765.00 put wall and the 770.00 call wall. The 785.00 gamma magnet caps upside; a break of the put wall is the accelerant, not the buy zone.
Trading readPositive gamma cluster sits above spot at the call wall while the negative-gamma wall stacks below at 765.00 - the tape has been engineered to accelerate on a break lower and to cap on any push into resistance.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna at -$69.17B is deeply negative - a vol pop mechanically forces dealers to sell delta into weakness. That is the accelerant, and it is fully armed with spot pinned under the flip. Any uptick in 11.86% compounds the short-delta problem rather than dampening it.
Charm at $1.6M is a rounding error against the vanna book - no meaningful time-decay tailwind to lean on into the close. Dealers do not get bailed out by the clock here; they get bailed out only by a reclaim of 767.645854032.
The charm pivot flags Destabilizing bias - the red-signal setup where dealer flow amplifies moves rather than absorbing them. Single decision level: reclaim 767.645854032 and the feedback loop softens; fail it and vanna-driven selling dominates the tape.
The tell today is MOVE at 95.45 ripping 21.5%% while VIX barely twitches at 3.03%% - this is a rates/duration episode bleeding into equities, not an equity-native shock. Fixed-income vol is leading, equity vol is the follower, and the lag is the trade window.
Fear & Greed at 34 prints Fear - real caution, not complacency, which means positioning has already de-risked into the tape rather than chasing it. QQQ at 739.51 and IWM at 281.15 both sit below their flips, confirming Aligned negative-gamma alignment across the complex.
No index offers a diversification hedge intraday - the fragility is uniform. Route the duration-driven vol premium through IWM condors where VRP is fattest; skip index-native short strangles until MOVE mean-reverts or VIX catches up.
What it means for your trading
MOVE leading VIX by 21.5%% flags a bond-vol shock the equity tape hasn't priced yet; with Fear & Greed at Fear and every index below its flip, treat this as a rates transmission event, not a stand-alone equity de-risking.
Scenario EV
The EV stack recommends Iron Condor at score 40, ahead of put spreads at 26 - directional structures are underpaying given the aligned negative-gamma tape. The sweet spot is 30-45 DTE, where Steep Contango in the VIX curve fattens the carry and the front-to-mid slope still favors sellers.
Vol-of-vol argues for full engagement: VVIX at 90.11 and the VVIX/VIX ratio at 5.76 sit squarely in the Normal band, clearing Standard Size rather than a defensive haircut. Route the harvest through IWM where VRP at 4.56% dwarfs SPY at 0.92%.
Discipline the wings. Naked short strangles stay off the sheet until spot reclaims the flip at 767.645854032 - with charm bias flagged Destabilizing, a breach compounds through vanna before the condor can breathe.
What it means for your trading
Trade the range via Iron Condor at 30-45 DTE, sized standard against a normal VVIX regime. Keep strangles holstered until spot reclaims 767.645854032.
Actionable Summary
Trade the range, not the direction. With SPY, QQQ, and IWM all pinned under their flip levels and cross-asset regime Aligned, the cleanest edge is IWM iron condors at 30-45 DTE where VRP prints 4.56% - the richest carry in the complex against SPY's thin 0.92%. Structure score 40 beats put spreads at 26; contango is doing the work.
Avoid naked SPY short strangles until spot reclaims the charm pivot at 767.645854032 - vanna at -$69.17B is a destabilizing accelerant on any vol re-price. Watch MOVE at 95.45, up 21.5%%: bond-vol contagion is the tail that flips the VIX curve. If spot reclaims flip and rallies stall into the call wall at 770.00, layer a put ratio hedge.
Sell IWM premium where VRP pays, respect 767.645854032 as the regime hinge, and keep MOVE at 95.45 on the tape as the single cross-asset trigger for a defensive pivot.
Hawkish Philly Fed rhetoric feeds directly into the MOVE spike and duration repricing - the primary macro cross-current pushing bond vol above equity vol today.
Family-office positioning survey confirms flow-of-funds tilt back toward stocks and PE even as inflation worry rises - supports the persistent dip-buy bid keeping SPY pinned at the flip.
NY Fed's Williams reinforcing a hike-by-year-end message - the second hawkish Fed voice today, corroborating the bond-vol spike and pressuring the front-end vol curve.
Bond market sell-off framing ahead of Trump-Xi ties directly to the 21.5%% MOVE spike; the lead story for cross-asset traders.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.65 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.65 against a spot of 767.10. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.86% with a volatility risk premium of 0.92%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.64. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime