Today's SPY, QQQ & VIX Gamma, Dealer Positioning & Regime | FlashAlpha

Market Overview

Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.

FlashAlpha Research AI-assisted
Generated
Validated citations - no literal numbers from LLM

SPY pinned just below flip at 767.76 - negative gamma, contango carry, Elevated / Watchful

SPY sits fractionally below its gamma flip at 767.76, keeping dealers short gamma into the close while VIX term structure Contango preserves carry for vol sellers. IWM's fat VRP at 4.88% contrasts thin SPY premium at 0.91%, and QQQ's regime remains undetermined on a stored sign mismatch. With Fear & Greed at Fear and MOVE steady at 95.45, the setup favors Iron Condor at 30-45 DTE while spot remains chained to the flip.

Dealer positioning levels
SymbolSpotGamma flipvs FlipCall wallPut wallMax painNet GEXRegime
SPY766.53767.76-0.16%785760760-$2.14BShort gamma
QQQ739.64--740730723$1.34B-
IWM281.41291.73-3.54%290280288-$4.59BShort gamma
VIX15.6716.27-3.67%201519.50-$26.65M-

Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.

Volatility and risk premium
SymbolATM IVHV 20dVRP25d skewP/C OIP/C volume
SPY11.7510.84+0.911.112.241.07
QQQ17.3316.21+1.121.411.430.94
IWM17.7912.91+4.880.282.321.44
VIX78.1499.97-21.83-129.460.310.40

VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.

Volatility complex
MeasureValueChange
VIX15.46+1.84%
VVIX90.32+1.94%
SPX7,704.13-0.02%
SKEW index146.150.00%
MOVE (bond vol)95.450.00%
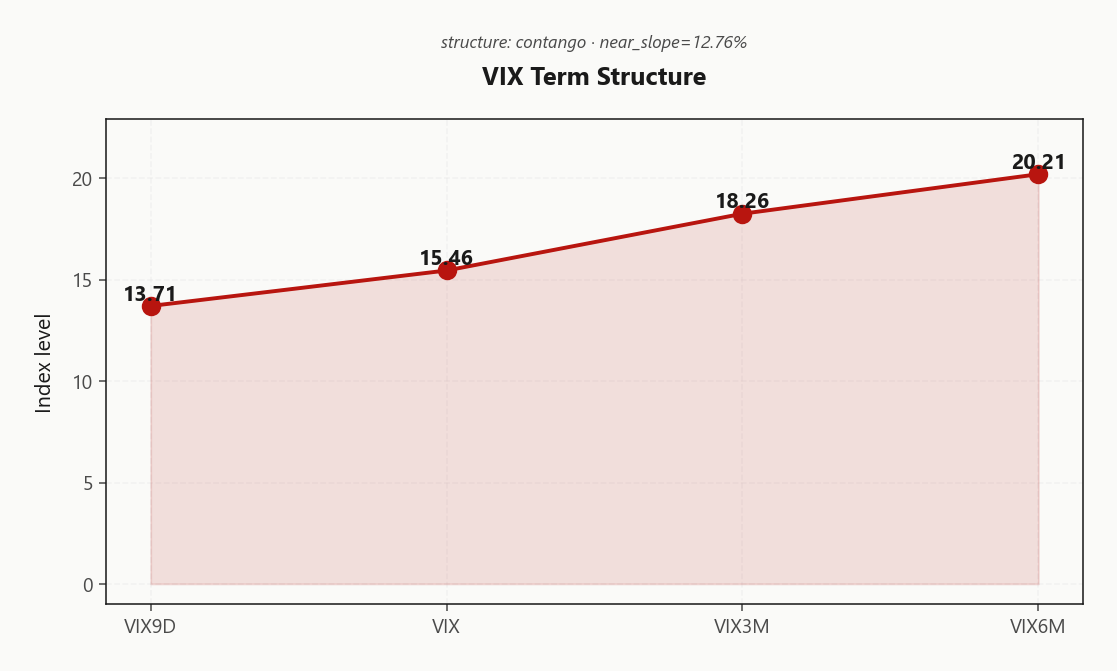
VIX term (9d/30d/3m/6m)13.71 / 15.46 / 18.26 / 20.21Steep contango
VVIX / VIX5.84Normal
RegimeElevated / Watchful

Regime Assessment

Regime reads Elevated / Watchful with VIX anchored at 15.46 - the elevated-but-not-stressed band where premium sellers still get paid and hedgers still get a bid. Half-life on this state runs 15 sessions, which is sticky, not fragile: this is not a regime on the edge of flipping, it is a regime built to grind.

Transition math backs the posture. Probability of decaying into panic over five sessions sits at 0.05, while probability of decaying lower across ten sessions runs 0.45 - the asymmetry favors vol sellers on any horizon that lets carry compound. Book structures that survive a full 15-session cycle earn; tactical trades priced against a flip that isn't coming leak.

Sizing stays disciplined. This is not a risk-on regime, it is a watchful one - enough vol premium to harvest through Iron Condor at 30-45 DTE, enough tail residue that a hedge still costs something to skip.

What it means for your trading
Elevated/Watchful with a 15-session half-life and asymmetric decay toward lower vol favors carry over insurance. Trade the regime, don't fade it - Iron Condor at 30-45 DTE is the expression.
macro_dashboard
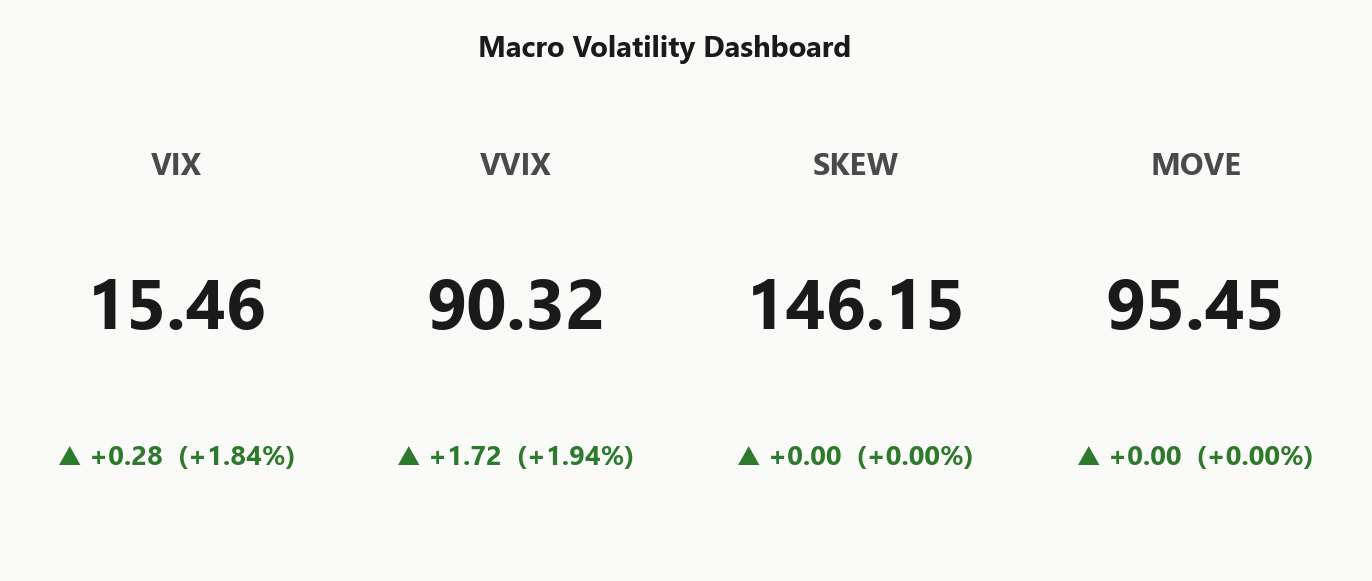
Trading readVIX, VVIX, SKEW, and MOVE are largely aligned in the elevated-but-not-stressed band - no divergence flashing yet. That's a market that grinds, not one that breaks, until one of the four dislocates.
VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.

Forward Vol Geometry

The VIX curve prints Contango on every leg, with 13.71 on VIX9D sitting cleanly under 15.46 spot VIX - no near-term event premium is bid, and the front-end is telling you the market is not paying for headline risk today. Treat any front-week vol pop as noise until VIX9D crosses spot VIX; that is the first tell that carry is breaking.

The belly is where the trade lives. VIX3M at 18.26 rolling into VIX6M at 20.21 preserves the rolldown edge for calendar and short-vol structures, and forward 30-60 vol at 19.5098846742 anchors 30-45 DTE as the harvest zone. The regime reads Steep Contango - vol sellers favored, calendar rolldown intact, front-week gamma avoided.

What it means for your trading
Steep contango from 13.71 through 20.21 keeps the carry trade alive; harvest the belly at 30-45 DTE and skip the front-week where negative vanna does the damage.
vix_term_structure
Trading readContango on every leg says the market isn't paying for near-term event risk - the carry trade for vol sellers is live. A break in the belly would be the first sign to close the book.
Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.

Realized Vol Structure

SPY ATM IV at 11.75% against HV20 10.84 and RV5 13.34 leaves a 0.91% spread that reads Thin Premium - options are priced close to fair versus recent tape, so short-premium at the index level has almost no cushion for a mistake.

IWM tells the opposite story. VRP prints 4.88%, the richest handle in the complex, and that is where iron condors and put-spread sales earn their keep. QQQ sits in the middle at 1.12% - not thin enough to skip outright, not fat enough to size up. VIX itself carries a negative VRP at -21.83%, so long vol-of-vol via VIX calls is not a give-away either.

Route the Iron Condor through IWM at 30-45 DTE where the premium actually pays for the risk. Naked SPY short vol does not clear the hurdle.

What it means for your trading
SPY premium is close to fair versus recent realized - the short-vol harvest lives in IWM at 4.88%, not the index. Route iron condors through the small-cap wing at 30-45 DTE, and leave SPY naked-premium off the book.

Skew Convexity

SPY quarter-delta put skew sits at 1.11% vol points - puts bid at 14.19% against calls at 13.08%, with the ATM anchored at 13.72%. Measured demand for downside, no vol-crush urgency. The smile ratio at 1.09% confirms the wings are lifted while the belly holds - a spread-structure market, not a naked-wing market.

IWM tells the more interesting story. Skew at 0.28% is unusually flat given a negative_gamma book carrying -$21.66B in vanna - hedgers are underweight downside protection into a fragile small-cap tape, and that mispricing is where wing-buy structures earn. QQQ skew at 1.41% runs steeper than the index, consistent with mega-cap concentration risk still commanding a bid despite the unresolved regime read.

Trade the dispersion: harvest SPY wings via defined-risk spreads, buy IWM tails where the market has not priced the gamma vulnerability, and let QQQ steepness cap the sizing on any tech-adjacent short-vol book.

What it means for your trading
Ordered SPY skew and flat IWM skew are misaligned with the underlying gamma regimes - spread structures on SPY, tail longs on IWM, and QQQ steepness caps naked tech vol sales.

Vol-of-Vol Structure

VVIX at 90.32 sits comfortably in the Normal band, with the ratio to VIX at 5.84 - no bimodal jump premium being priced, no dealer scramble to hedge convexity. The session's 1.94% uptick is worth logging alongside the Fear F&G reading, but neither rises to a sizing constraint on its own.

The takeaway: Standard Size on the Iron Condor book. No VVIX-driven haircut required, and no case to lean in either - the vol-of-vol tape is calm enough to underwrite standard risk, tight enough not to reward oversizing. VVIX would need a clean break higher before that calculus shifts.

Contrast against SKEW at 146.15: the tail is bid, but jump risk is not. Hedgers are paying for depth, not for discontinuity - a market that grinds through headline noise rather than one repricing convexity. Keep the tail hedge live, but treat the vol-of-vol layer as a green light on structure sizing.

What it means for your trading
VVIX at 90.32 and the 5.84 ratio to VIX read as Normal - Standard Size on the Iron Condor with no haircut, though SKEW at 146.15 keeps a tail hedge sensible.

Dispersion Spread

Cross-strike dispersion at {"cross Expiry":2.95,"cross Strike":66.74} paints a moderate picture - index vol at 11.75% is a serviceable hedge, but it understates the single-name vol embedded in the mega-cap complex where {"symbol":"META","as Of":"2026-09-24T20:14:55.653Z","market Open":false,"price":{"bid":775.56,"ask":775.74,"mid":775.65,"last":775.65,"last Update":"2026-09-24T20:14:55.653Z"},"volatility":{"atm Iv":48.1,"hv 20":47.57,"hv 60":50.47,"vrp":0.53,"skew 25d":{"expiry":"2026-09-25","days To Expiry":1,"put 25d Iv":54.14,"atm Iv":51.97,"call 25d Iv":63.85,"skew 25d":-9.71,"smile Ratio":0.848},"iv Term Structure":[{"expiry":"2026-09-25","iv":58.05,"days To Expiry":1},{"expiry":"2026-09-28","iv":41.54,"days To Expiry":4},{"expiry":"2026-09-30","iv":47.23,"days To Expiry":6},{"expiry":"2026-10-02","iv":48.1,"days To Expiry":8},{"expiry":"2026-10-05","iv":44.78,"days To Expiry":11},{"expiry":"2026-10-07","iv":43.28,"days To Expiry":13},{"expiry":"2026-10-09","iv":45.63,"days To Expiry":15},{"expiry":"2026-10-16","iv":44.17,"days To Expiry":22},{"expiry":"2026-10-23","iv":43.44,"days To Expiry":29},{"expiry":"2026-10-30","iv":49.68,"days To Expiry":36},{"expiry":"2026-11-06","iv":49.02,"days To Expiry":44},{"expiry":"2026-11-20","iv":47.41,"days To Expiry":58},{"expiry":"2026-12-18","iv":45.08,"days To Expiry":86},{"expiry":"2027-01-15","iv":43.72,"days To Expiry":114},{"expiry":"2027-02-19","iv":45.33,"days To Expiry":149},{"expiry":"2027-03-19","iv":44.96,"days To Expiry":176},{"expiry":"2027-06-17","iv":45.16,"days To Expiry":266},{"expiry":"2027-09-17","iv":45.55,"days To Expiry":358},{"expiry":"2027-12-17","iv":45.74,"days To Expiry":450},{"expiry":"2028-01-21","iv":45.66,"days To Expiry":485},{"expiry":"2028-06-16","iv":46.19,"days To Expiry":631},{"expiry":"2028-12-15","iv":46.47,"days To Expiry":814},{"expiry":"2029-01-19","iv":46.44,"days To Expiry":849}]},"options Flow":{"total Call Oi":2274405,"total Put Oi":1058025,"total Call Volume":824965,"total Put Volume":472477,"pc Ratio Oi":0.465,"pc Ratio Volume":0.573,"active Expirations":23},"exposure":{"net Gex":2353618443,"net Dex":90376527752,"net Vex":-2300153617,"net Chex":-990496,"gamma Flip":null,"gamma Flip Status":"no Boundary","call Wall":800,"put Wall":750,"max Pain":650,"highest Oi Strike":750,"regime":"unknown","interpretation":{"gamma":"Gamma regime undetermined - no published flip (no Boundary)","vanna":"Vol up = dealers sell delta - downside amplified if vol spikes","charm":"Time decay pushing dealers to sell - pressure into close"},"hedging Estimate":{"spot Down 1pct":{"dealer Shares":3034382,"direction":"buy","notional Usd":2353618443},"spot Up 1pct":{"dealer Shares":-3034382,"direction":"sell","notional Usd":-2353618443}},"zero Dte":{"net Gex":0,"pct Of Total":0,"expiration":null},"top Strikes":[{"strike":750,"net Gex":397243904,"call Oi":297417,"put Oi":15528,"total Oi":312945},{"strike":800,"net Gex":385009940,"call Oi":208801,"put Oi":5182,"total Oi":213983},{"strike":700,"net Gex":182600753,"call Oi":190556,"put Oi":29412,"total Oi":219968},{"strike":775,"net Gex":125471332,"call Oi":35117,"put Oi":557,"total Oi":35674},{"strike":765,"net Gex":99849035,"call Oi":28300,"put Oi":1233,"total Oi":29533}],"oi Weighted Dte":153.6},"macro":{"vix":{"value":15.46,"change":0.28,"change Pct":1.84,"as Of":"2026-09-24T19:55:01Z"},"vvix":{"value":90.32,"change":1.72,"change Pct":1.94,"as Of":"2026-09-24T19:54:46Z"},"skew":{"value":146.15,"change":0,"change Pct":0,"as Of":"2026-09-23T21:00:19Z"},"spx":{"value":7704.13,"change":-1.9,"change Pct":-0.02,"as Of":"2026-09-24T20:10:00Z"},"move":{"value":95.4527,"change":0,"change Pct":0,"as Of":"2026-09-24T19:30:00Z"},"vix Term Structure":{"levels":{"vix9d":13.71,"vix":15.46,"vix3m":18.26,"vix6m":20.21},"near Slope Pct":12.76,"structure":"contango"},"vix Futures":{"front Month":18.26,"spot":15.46,"spread":2.8,"basis Pct":18.11,"basis":"contango"},"fear And Greed":{"score":36,"rating":"fear"}},"endpoint Version":"2026.09.11","data As Of":{"node":"fa5","equity Feed":"2026-09-24T20:14:58.746Z","equity Options Feed":"2026-09-24T20:14:58Z","index Feed":"2026-09-24T20:14:46.376Z","index Options Feed":"2026-09-24T20:14:59Z","futures Feed":"2026-09-24T20:14:56.992Z","futures Options Feed":"2026-09-24T20:14:57.05Z","flow Feed":"2026-09-24T20:14:00Z","oi Feed":"2026-09-23T20:00:00Z","macro Feed":"2026-09-23T21:00:19Z"}}, {"symbol":"NVDA","as Of":"2026-09-24T20:14:58.387Z","market Open":false,"price":{"bid":224,"ask":224.09,"mid":224.04500000000002,"last":224.04500000000002,"last Update":"2026-09-24T20:14:58.387Z"},"volatility":{"atm Iv":30.46,"hv 20":44.29,"hv 60":39.23,"vrp":-13.83,"skew 25d":{"expiry":"2026-09-25","days To Expiry":1,"put 25d Iv":30.26,"atm Iv":25.95,"call 25d Iv":36.15,"skew 25d":-5.89,"smile Ratio":0.837},"iv Term Structure":[{"expiry":"2026-09-25","iv":34.55,"days To Expiry":1},{"expiry":"2026-09-28","iv":25.76,"days To Expiry":4},{"expiry":"2026-09-30","iv":29.09,"days To Expiry":6},{"expiry":"2026-10-02","iv":30.46,"days To Expiry":8},{"expiry":"2026-10-05","iv":28.31,"days To Expiry":11},{"expiry":"2026-10-07","iv":29.73,"days To Expiry":13},{"expiry":"2026-10-09","iv":30.43,"days To Expiry":15},{"expiry":"2026-10-16","iv":30.84,"days To Expiry":22},{"expiry":"2026-10-23","iv":31.34,"days To Expiry":29},{"expiry":"2026-10-30","iv":31.86,"days To Expiry":36},{"expiry":"2026-11-06","iv":32.39,"days To Expiry":44},{"expiry":"2026-11-20","iv":36.88,"days To Expiry":58},{"expiry":"2026-12-18","iv":36.31,"days To Expiry":86},{"expiry":"2027-01-15","iv":36.45,"days To Expiry":114},{"expiry":"2027-02-19","iv":36.63,"days To Expiry":149},{"expiry":"2027-03-19","iv":38.08,"days To Expiry":176},{"expiry":"2027-04-16","iv":38.28,"days To Expiry":204},{"expiry":"2027-06-17","iv":38.98,"days To Expiry":266},{"expiry":"2027-09-17","iv":39.48,"days To Expiry":358},{"expiry":"2027-12-17","iv":40,"days To Expiry":450},{"expiry":"2028-01-21","iv":40,"days To Expiry":485},{"expiry":"2028-06-16","iv":40.73,"days To Expiry":631},{"expiry":"2028-12-15","iv":41.49,"days To Expiry":814},{"expiry":"2029-01-19","iv":41.03,"days To Expiry":849}]},"options Flow":{"total Call Oi":7718084,"total Put Oi":6685213,"total Call Volume":1067832,"total Put Volume":595019,"pc Ratio Oi":0.866,"pc Ratio Volume":0.557,"active Expirations":24},"exposure":{"net Gex":1750380478,"net Dex":61922314120,"net Vex":8053576562,"net Chex":874160,"gamma Flip":214.959681326826,"gamma Flip Status":"sensitive Root","call Wall":230,"put Wall":220,"max Pain":200,"highest Oi Strike":200,"regime":"unknown","interpretation":{"gamma":"Gamma regime undetermined - gamma flip shown but unverified (sensitive Root); treat the level as indicative","vanna":"Vol up = dealers buy delta - downside dampened if vol spikes","charm":"Time decay pushing dealers to buy - supportive into close"},"hedging Estimate":{"spot Down 1pct":{"dealer Shares":7812629,"direction":"buy","notional Usd":1750380478},"spot Up 1pct":{"dealer Shares":-7812629,"direction":"sell","notional Usd":-1750380478}},"zero Dte":{"net Gex":0,"pct Of Total":0,"expiration":null},"top Strikes":[{"strike":230,"net Gex":375729273,"call Oi":463210,"put Oi":94764,"total Oi":557974},{"strike":222.5,"net Gex":206133558,"call Oi":73406,"put Oi":18800,"total Oi":92206},{"strike":227.5,"net Gex":196851549,"call Oi":68639,"put Oi":12661,"total Oi":81300},{"strike":225,"net Gex":174162179,"call Oi":210347,"put Oi":88709,"total Oi":299056},{"strike":250,"net Gex":151100383,"call Oi":455395,"put Oi":20732,"total Oi":476127}],"oi Weighted Dte":180.1},"macro":{"vix":{"value":15.46,"change":0.28,"change Pct":1.84,"as Of":"2026-09-24T19:55:01Z"},"vvix":{"value":90.32,"change":1.72,"change Pct":1.94,"as Of":"2026-09-24T19:54:46Z"},"skew":{"value":146.15,"change":0,"change Pct":0,"as Of":"2026-09-23T21:00:19Z"},"spx":{"value":7704.13,"change":-1.9,"change Pct":-0.02,"as Of":"2026-09-24T20:10:00Z"},"move":{"value":95.4527,"change":0,"change Pct":0,"as Of":"2026-09-24T19:30:00Z"},"vix Term Structure":{"levels":{"vix9d":13.71,"vix":15.46,"vix3m":18.26,"vix6m":20.21},"near Slope Pct":12.76,"structure":"contango"},"vix Futures":{"front Month":18.26,"spot":15.46,"spread":2.8,"basis Pct":18.11,"basis":"contango"},"fear And Greed":{"score":36,"rating":"fear"}},"endpoint Version":"2026.09.11","data As Of":{"node":"fa5","equity Feed":"2026-09-24T20:14:58.746Z","equity Options Feed":"2026-09-24T20:14:58Z","index Feed":"2026-09-24T20:14:46.376Z","index Options Feed":"2026-09-24T20:14:59Z","futures Feed":"2026-09-24T20:14:56.992Z","futures Options Feed":"2026-09-24T20:14:57.05Z","flow Feed":"2026-09-24T20:14:00Z","oi Feed":"2026-09-23T20:00:00Z","macro Feed":"2026-09-23T21:00:19Z"}}, and {"symbol":"AAPL","as Of":"2026-09-24T20:14:58Z","market Open":false,"price":{"bid":335.65,"ask":335.74,"mid":335.695,"last":335.695,"last Update":"2026-09-24T20:14:58Z"},"volatility":{"atm Iv":22.78,"hv 20":21.68,"hv 60":28.45,"vrp":1.1,"skew 25d":{"expiry":"2026-09-25","days To Expiry":1,"put 25d Iv":24.21,"atm Iv":22.92,"call 25d Iv":25.93,"skew 25d":-1.72,"smile Ratio":0.934},"iv Term Structure":[{"expiry":"2026-09-25","iv":24.74,"days To Expiry":1},{"expiry":"2026-09-28","iv":19.01,"days To Expiry":4},{"expiry":"2026-09-30","iv":21.67,"days To Expiry":6},{"expiry":"2026-10-02","iv":22.78,"days To Expiry":8},{"expiry":"2026-10-05","iv":21.41,"days To Expiry":11},{"expiry":"2026-10-07","iv":21.68,"days To Expiry":13},{"expiry":"2026-10-09","iv":22.35,"days To Expiry":15},{"expiry":"2026-10-16","iv":22.47,"days To Expiry":22},{"expiry":"2026-10-23","iv":22.44,"days To Expiry":29},{"expiry":"2026-10-30","iv":26.2,"days To Expiry":36},{"expiry":"2026-11-06","iv":26,"days To Expiry":44},{"expiry":"2026-11-20","iv":25.83,"days To Expiry":58},{"expiry":"2026-12-18","iv":25.31,"days To Expiry":86},{"expiry":"2027-01-15","iv":25.27,"days To Expiry":114},{"expiry":"2027-02-19","iv":26.48,"days To Expiry":149},{"expiry":"2027-03-19","iv":26.82,"days To Expiry":176},{"expiry":"2027-04-16","iv":26.81,"days To Expiry":204},{"expiry":"2027-06-17","iv":27.6,"days To Expiry":266},{"expiry":"2027-09-17","iv":28.1,"days To Expiry":358},{"expiry":"2027-12-17","iv":28.63,"days To Expiry":450},{"expiry":"2028-01-21","iv":28.37,"days To Expiry":485},{"expiry":"2028-03-17","iv":28.63,"days To Expiry":540},{"expiry":"2028-06-16","iv":28.98,"days To Expiry":631},{"expiry":"2028-12-15","iv":29.44,"days To Expiry":814},{"expiry":"2029-01-19","iv":29.32,"days To Expiry":849}]},"options Flow":{"total Call Oi":2730423,"total Put Oi":2009420,"total Call Volume":517738,"total Put Volume":306241,"pc Ratio Oi":0.736,"pc Ratio Volume":0.591,"active Expirations":25},"exposure":{"net Gex":1436860814,"net Dex":38022078483,"net Vex":-8692969090,"net Chex":206387,"gamma Flip":314.51971811003,"gamma Flip Status":"sensitive Root","call Wall":340,"put Wall":330,"max Pain":300,"highest Oi Strike":300,"regime":"unknown","interpretation":{"gamma":"Gamma regime undetermined - gamma flip shown but unverified (sensitive Root); treat the level as indicative","vanna":"Vol up = dealers sell delta - downside amplified if vol spikes","charm":"Time decay pushing dealers to buy - supportive into close"},"hedging Estimate":{"spot Down 1pct":{"dealer Shares":4280257,"direction":"buy","notional Usd":1436860814},"spot Up 1pct":{"dealer Shares":-4280257,"direction":"sell","notional Usd":-1436860814}},"zero Dte":{"net Gex":0,"pct Of Total":0,"expiration":null},"top Strikes":[{"strike":340,"net Gex":450284078,"call Oi":212248,"put Oi":27176,"total Oi":239424},{"strike":350,"net Gex":209805825,"call Oi":220392,"put Oi":14975,"total Oi":235367},{"strike":360,"net Gex":161045397,"call Oi":182903,"put Oi":4757,"total Oi":187660},{"strike":345,"net Gex":150534531,"call Oi":85114,"put Oi":8843,"total Oi":93957},{"strike":337.5,"net Gex":81748561,"call Oi":16256,"put Oi":4791,"total Oi":21047}],"oi Weighted Dte":153.4},"macro":{"vix":{"value":15.46,"change":0.28,"change Pct":1.84,"as Of":"2026-09-24T19:55:01Z"},"vvix":{"value":90.32,"change":1.72,"change Pct":1.94,"as Of":"2026-09-24T19:54:46Z"},"skew":{"value":146.15,"change":0,"change Pct":0,"as Of":"2026-09-23T21:00:19Z"},"spx":{"value":7704.13,"change":-1.9,"change Pct":-0.02,"as Of":"2026-09-24T20:10:00Z"},"move":{"value":95.4527,"change":0,"change Pct":0,"as Of":"2026-09-24T19:30:00Z"},"vix Term Structure":{"levels":{"vix9d":13.71,"vix":15.46,"vix3m":18.26,"vix6m":20.21},"near Slope Pct":12.76,"structure":"contango"},"vix Futures":{"front Month":18.26,"spot":15.46,"spread":2.8,"basis Pct":18.11,"basis":"contango"},"fear And Greed":{"score":36,"rating":"fear"}},"endpoint Version":"2026.09.11","data As Of":{"node":"fa5","equity Feed":"2026-09-24T20:14:58.746Z","equity Options Feed":"2026-09-24T20:14:58Z","index Feed":"2026-09-24T20:14:46.376Z","index Options Feed":"2026-09-24T20:14:59Z","futures Feed":"2026-09-24T20:14:56.992Z","futures Options Feed":"2026-09-24T20:14:57.05Z","flow Feed":"2026-09-24T20:14:00Z","oi Feed":"2026-09-23T20:00:00Z","macro Feed":"2026-09-23T21:00:19Z"}} anchor the GEX mover ranks. The index number smooths the idiosyncratic premium the tape is actually paying for.

That dispersion argues explicitly against selling far-wing puts naked - spread structures dominate when the cross-strike surface is this uneven, and the ordered 1.09% smile ratio confirms the wings are lifted enough to price the risk without collapsing the ATM. Single-name harvest on the movers list belongs sized against index shorts, not stacked on top of them.

Correlation risk is the discipline gate: a shock day compresses the dispersion premium fast, so the same book that earns in a grind gives it all back on a synchronized down-print. Size the single-name leg against the Iron Condor on the index - don't let the idiosyncratic pickup lull the risk budget.

What it means for your trading
Moderate dispersion favors spread structures over naked wings, and the mega-cap premium is where single-name harvest actually earns - but only when hedged against index shorts, since a correlated shock day collapses the edge in one session.

Liquidity & Microstructure

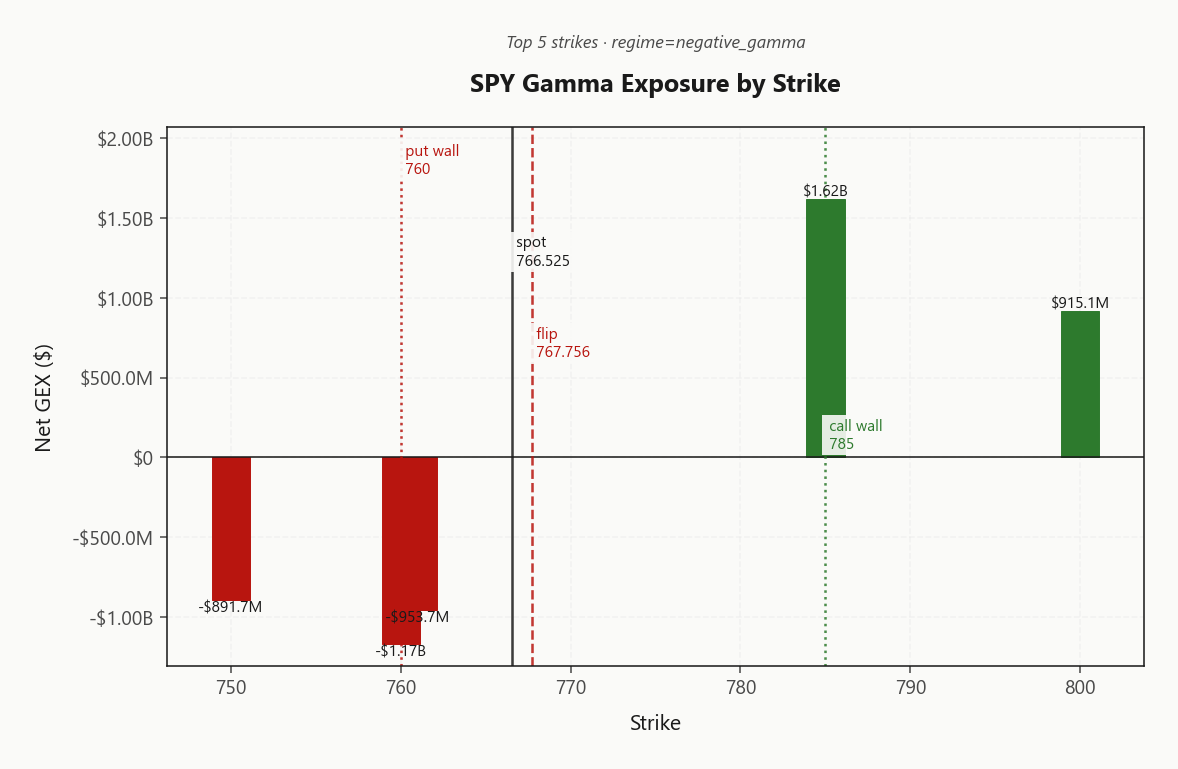
Open interest stacks the book between the put wall at 760.00 and the call wall at 785.00, with the gamma flip at 767.76 sitting a hair above spot. That flip is today's regime switch - cross it and dealer flow reverses from amplifying to damping.

The top strike net GEX of $1.62B at 785.00 caps upside cleanly - that's where dealer sellers show up on any push higher. The put wall at 760.00 lines up with heavy put OI and marks the bounce zone if spot leaks. The highest OI strike at 500 is a legacy longer-dated cluster - ignore it for tactical work today.

With spot within a rounding error of the flip, intraday range expansion is the base case: dealers short gamma amplify moves in both directions until the tape resolves through 767.76. Fade extensions to the walls, respect the flip as the trigger, and treat the channel between the walls as noise until volume confirms.

What it means for your trading
Book is stacked between 760.00 and 785.00 with the flip at 767.76 as today's regime switch. Fade to the walls, respect the flip, expect intraday range expansion until spot resolves through it.
spy_gex_by_strike
Trading readThe stack from the put wall through the flip up to the call wall is where dealer flow does the work today - fade prints into the walls, respect the flip as the regime switch, and treat any move inside that channel as noise unless volume confirms.
Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).

Dealer Vanna & Charm

Dealer vanna prints -$60.27B - the book is loaded to sell into any front-week vol lift. A pop in IV translates directly into forced delta hedging on the short side, which is why the tape reacts more violently to a vol print than to a spot print in this configuration. Charm at -$664.1K is muted, so the usual close-of-week pin flow is absent; do not expect time decay to anchor spot into Friday.

The single tactical trigger is the flip at 767.7555848441. Spot sits 0.1605407318% away on the Destabilizing side - a rounding-error move reverses dealer flow from amplifying to damping. IWM VEX at -$21.66B confirms small-cap dealers are even more exposed to a vol pop, which is why the wing carries the sharper reflexive risk if VVIX 90.32 ticks through its recent range.

Trade the flip as the switch, not the tape. Hedge vega before front-week IV moves; do not lean on charm for a pin.

What it means for your trading
Negative vanna -$60.27B plus muted charm -$664.1K means a vol spike, not time decay, is the accelerant - and spot sits 0.1605407318% from the flip 767.7555848441 on the destabilizing side. Cross the flip and dealer flow reverses; until then, hedge vega and treat any move as amplified rather than damped.

Cross-Asset Confirmation

MOVE holding at 95.45 is the tell - bond vol is not leading equity vol into this print. Credit is calm, the rates-vol channel is quiet, and the Iran headline tape is present without compounding. Fear & Greed prints Fear at 36 while VIX itself sits at 15.46 - sentiment worse than the vol tape, the classic contrarian-supportive setup for premium sellers who can stomach the negative-gamma backdrop.

The divergence is the storyline. SPY prints a Negative Gamma regime against QQQ at 739.64 where the flip is unpublished on a stored sign mismatch - tech regime is qualitative until it reconciles. IWM at 281.41 carries the fragility: small-cap breadth is still the tell, and its fat 4.88% VRP is where short-vol structures earn.

Bottom line: aligned across the complex on direction, split on regime clarity - a positioning story, not a macro shock. Route the trade through IWM.

What it means for your trading
MOVE at 95.45 unchanged and F&G at Fear confirm a positioning-driven tape, not a macro break - the SPY-negative / QQQ-undetermined split is the day's read, with IWM at 281.41 carrying the fragility premium.

Scenario EV

The scoring engine lands on Iron Condor at score 40, comfortably ahead of the put spread at 26 on VRP-adjusted expectancy. The 30-45 DTE window is the sweet spot - far enough out that negative vanna at -$60.27B has room to cool, close enough to capture the rolldown embedded in a Contango term structure.

Route matters more than structure. IWM carries a fat 4.88% that actually pays for the negative-gamma risk in the small-cap book, while SPY's thin 0.91% leaves no cushion against a vanna-driven vol pop. Stack the condor on IWM; leave the index premium alone.

Sizing stays Standard Size - VVIX at 90.32 and the 5.84 ratio to VIX sit in the Normal band, so no vol-of-vol haircut is warranted. The flip at 767.7555848441 remains the tactical trigger for widening or trimming wings intraday.

What it means for your trading
Iron condor at 30-45 DTE, routed through IWM where VRP is fat, sized Standard Size - SPY premium doesn't compensate for the negative vanna carried on the index book.

Actionable Summary

Bottom line: route the Iron Condor through IWM at 30-45 DTE, where 4.88% premium actually pays for the risk. Fade extensions to the SPY walls at 785.00 and 760.00, and treat the flip at 767.7555848441 as today's tactical trigger - cross above and dealers turn stabilizing, stay below and the tape stays amplified.

Avoid naked SPY premium sales: 0.91% does not compensate for net vanna at -$60.27B, where a vol pop forces the whole book into a seller. Keep a tail hedge live - 90.32 VVIX is normal but ticked up, and the Elevated / Watchful regime is sticky enough to trade the range yet fragile enough to punish complacency.

Sizing Standard Size - no case to trim, no case to lean in.

What it means for your trading
Iron condor on IWM at 30-45 DTE is the trade; the SPY flip at 767.7555848441 is the switch that reverses dealer flow and dictates whether the range holds.

News Watch

Frequently Asked Questions

What is the current market volatility regime?
VIX is trading at 15.67 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Negative Gamma gamma with net dealer GEX at -$2.14B. The gamma flip sits at 767.76, with the call wall at 785.00 and the put wall at 760.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at 767.76 against a spot of 766.53. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.75% with a volatility risk premium of 0.91%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.46. Contango signals benign forward expectations; backwardation signals near-term stress.
What's the dealer positioning on QQQ and IWM?
QQQ shows Unknown gamma with net GEX at $1.34B (flip: N/A). IWM shows Negative Gamma gamma with net GEX at -$4.59B (flip: 291.73).