Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
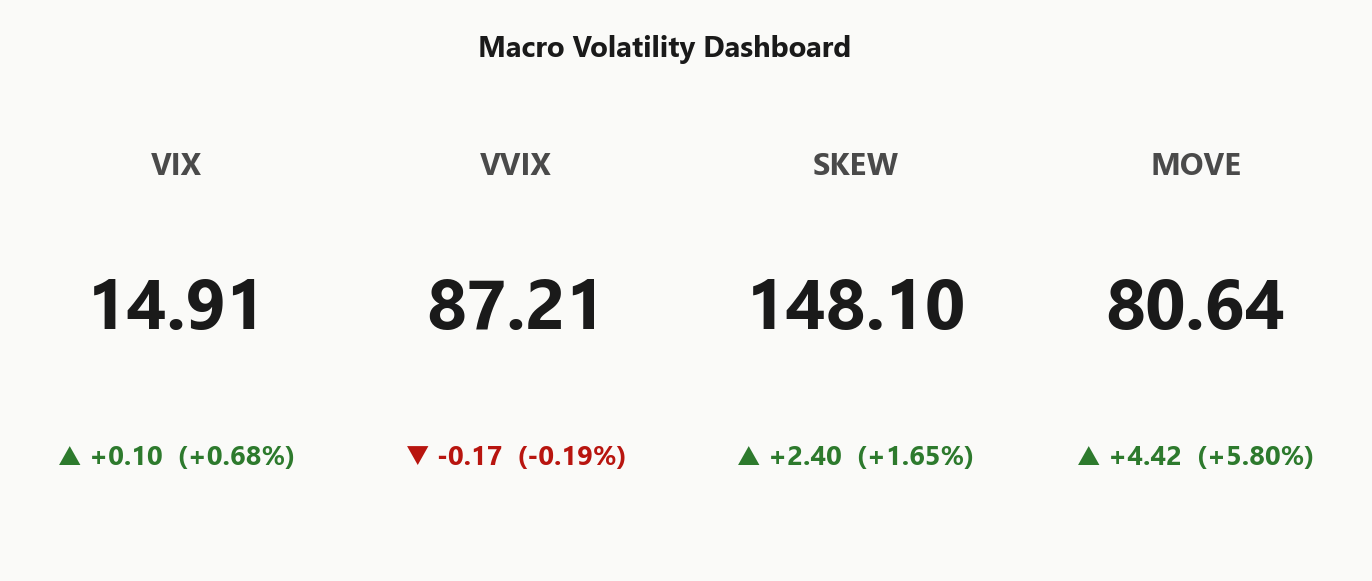
SPY trades at 766.86, sitting precisely at the gamma flip level 765.3704626356 - net GEX prints $4.32B with the regime officially undetermined at this pivot. Call wall sits at 770.00, put wall at 745.00, gamma flip at 765.3704626356: above pivot activates dampening flow, below pivot flips to trend amplification. Dealer positioning shows net vanna -$137.49B (vol-up = dealers sell delta, hostile if VIX pops), charm -$3.5M bias Supportive into close. Vol read: VIX at 14.91, term structure Contango with VIX9D 12.27 well below VIX3M 18.24, VRP 0.48% thin but positive. VVIX at 87.21 gives VVIX/VIX 5.85 - low vol-of-vol supports Standard Size sizing. Cross-asset divergence is the day's real story: QQQ Positive Gamma at 730.78 above its flip 725.01, IWM Negative Gamma at 285.14 below flip 293.77. Bottom line: fade strength above SPY 765.3704626356 toward the call wall 770.00, respect IWM as the fragile leg - a break of 280.00 amplifies index tape.
The index complex diverges into Monday's open - QQQ operates in a long-gamma dampening regime while IWM sits below its flip in trend-amplifying territory. SPY balances on its gamma flip at 765.3704626356, the key pivot for today's tape. VIX at 14.91 with steep contango Steep contango - vol sellers favored and low VVIX/VIX ratio 5.85 keeps carry structures in the driver's seat.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
766.86
765.37
+0.19%
770
745
755
$4.32B
-
QQQ
730.78
725.01
+0.80%
735
700
710
$8.87B
Long gamma
IWM
285.14
293.77
-2.94%
290
280
289
-$3.39B
Short gamma
VIX
14.91
-
-
20
14.50
20
$3.60M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.64
9.16
+0.48
2.62
2.28
1.66
QQQ
12.86
13.24
-0.38
4.30
1.39
0.97
IWM
14.04
11.77
+2.27
3.85
2.50
1.97
VIX
90.18
99.59
-9.41
-140.44
0.30
0.73
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
14.91
+0.68%
VVIX
87.21
-0.19%
SPX
7,697.79
+0.62%
SKEW index
148.10
+1.65%
MOVE (bond vol)
80.64
+5.80%
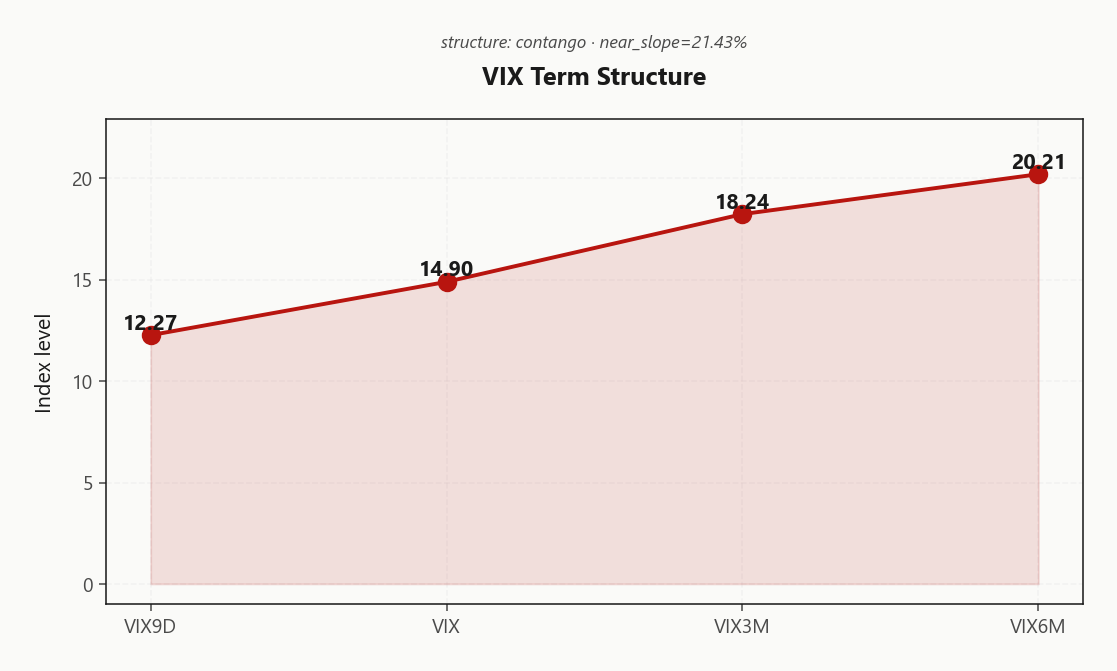
VIX term (9d/30d/3m/6m)
12.27 / 14.90 / 18.24 / 20.21
Steep contango
VVIX / VIX
5.85
Low
Regime
Low / Carry
Regime Assessment
Current regime prints Low, tagged Low / Carry with VIX anchored at 14.91. This is a carry tape, not a panic tape, and the base rates say so with conviction.
Transition math is the tell: panic-shift probability sits at 0.05 over the next 5 sessions against a stay-low probability of 0.45 across 10 - the distribution is heavily skewed toward persistence. Carry structures earn the base rate; tail hedges are the tax you pay for the tiny left slice, not the trade.
Half-life clocks at 30 sessions, meaning today's regime bleeds slowly and predictably. Trade the tape you see: harvest premium, respect the flip level, and do not front-run a regime shift the data isn't showing. Position for continuation with defined-risk shorts; keep dated wings on as insurance, not as a directional bet.
What it means for your trading
Base rates and half-life both argue this Low / Carry regime persists - lean into carry, size standard, and let the tiny 0.05 panic-transition tail justify cheap wings rather than defensive de-grossing.
Trading readVIX low, VVIX low, SKEW elevated, MOVE nudging up - three of four say carry, one whispers caution. The divergence is worth watching: MOVE leads equity vol by weeks when the shift is real.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The front end is priced for quiet: 12.27 VIX9D sits materially below spot VIX at 14.90, which itself trades under VIX3M at 18.24. Structure prints Contango with no event premium bid into the nine-day tenor - the curve is telling you realized expectations for the next two weeks are anchored, not just complacent.
The forward slopes make the carry ladder explicit: forward 30-60 vol 19.6987664588 versus forward 60-90 at 22.0043313918, with a near-slope of 21.43%%. Every day the spot doesn't spike, sellers collect the difference. Regime classifies Steep Contango - Steep contango - vol sellers favored - the cleanest short-vol setup in weeks.
Own the roll-down where it is most convex: 21-45 DTE. Front-week structures carry too little premium against pin risk at the flip; anything past 60 DTE gives back the steepest part of the slope. The middle of the curve is where the geometry pays.
What it means for your trading
Term structure is Contango with a clean carry ladder from 12.27 through 18.24 - the 21-45 DTE window is where forward vol roll-down compounds fastest without paying front-tenor pin tax.
Trading readFront-month contango this steep is a classic carry setup - vol sellers get paid the slope every day the spot doesn't spike. But steep contango also means the biggest give-back happens fastest if the curve inverts.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV at 9.64% against HV20 9.16 leaves a variance risk premium of just 0.48% - a carry cushion exists, but it is narrow. Selling index vol earns the slope, not the fat tail; position sizing has to respect that the margin for realized-vol surprise is thin.
QQQ tells the opposite story. ATM IV at 12.86% sits below HV20 13.24, printing an inverted VRP of -0.38%. Options are cheap to what tech has actually delivered - long premium and calendar longs are the structural edge, not short strangles.
IWM carries the fattest premium in the complex at 2.27%. That is where short-vol structures earn the most vega-per-dollar - iron condors and strangles belong on small caps, not SPY and certainly not QQQ. The VRP map argues for a split book: harvest premium in Negative Gamma IWM, own it in QQQ, tread lightly on SPY.
What it means for your trading
VRP splits three ways: SPY thin, QQQ inverted, IWM rich - short-vol edge belongs in 2.27% small caps while tech favors long premium.
Skew Convexity
Downside skew sits steep across the complex. SPY put-25d IV prints 11.62% against ATM 9.65%, driving skew to 2.62% and a smile ratio of 1.29% - left-tail hedging demand persists even with VIX at 14.91. Nobody trusts the quiet.
QQQ steepens harder: smile ratio 1.37% outruns SPY, so tech hedges cost more per unit of ATM vega. Meanwhile SPY call-25d IV at 9% sits below ATM - upside skew is inverted, no conviction behind the chase. IWM carries the same defensive left-tail bid without any right-side compensation.
Trade implication: the wing is expensive, so fund it. Put spreads dominate naked long puts on payoff-per-vega - you sell the overpriced far strike back to the panic bid. On the call side, the flat-to-inverted right wing means ratio call spreads and call flies get paid cheaply for upside convexity. Do not buy the wing outright; own it as spread.
What it means for your trading
Steep put skew with smile ratio 1.29% and inverted call-25d 9% vs ATM 9.65% favors put spreads over naked puts and call flies over outright long calls. Fund the expensive wing rather than paying up for it.
Vol-of-Vol Structure
VVIX prints 87.21 against VIX 14.91, pinning the ratio at 5.85 - a Low vol-of-vol read. No bimodal outcome is priced into the wings; the market is comfortable that suppressed vol stays suppressed, and the surface is not paying up for a jump.
Sizing guidance falls out clean at Standard Size - no case for halving notional on vol-of-vol grounds. Carry structures earn their full ticket into a benign VVIX print, and the usual defensive haircut applied when the ratio runs hot simply does not bind here.
The one edge cheap VVIX hands you: convexity buyers get a discount. Dated wing protection is on sale, and locking in tail hedges now - while the surface refuses to price a regime break - is the trade that ages well when the ratio inevitably re-rates higher.
What it means for your trading
VVIX/VIX at 5.85 is Low - carry runs at Standard Size notional, and the discount on VVIX makes dated tail hedges the asymmetric add.
Dispersion Spread
SPY ATM IV at 9.64% is pressed into cycle-low territory, yet the GEX-change leaderboard is dominated by mega-cap AI names - META leads, with NVDA, AAPL, MSFT and GOOGL stacked behind. Index vol looks quiet; single-name vol is where the story lives. The moderate correlation regime means index short-vol structures still capture broad dampening from QQQ's positive-gamma cushion, but the premium collected on SPX/SPY is thin against the idiosyncratic risk warehoused in the mover complex.
Dispersion is the tell: implied correlation compresses while single-name positioning churns, so index hedges only partially net down the underlying constituent vol. Short-vol on any of the top GEX movers pays a wide bid-ask in delta terms if a mega-cap breaks alone.
Preferred posture: harvest index VRP through cross-asset carry - particularly the fatter premium outside SPY - and refuse to write short vol on META, NVDA or AAPL into the earnings runway. Let the index book earn the calm; let the singles earn their own premium.
What it means for your trading
With SPY ATM IV at 9.64% and single-name GEX churn concentrated in META and the AI mega-caps, dispersion favors owning index short-vol while sidestepping short premium on the top GEX-mover names into earnings.
Liquidity & Microstructure
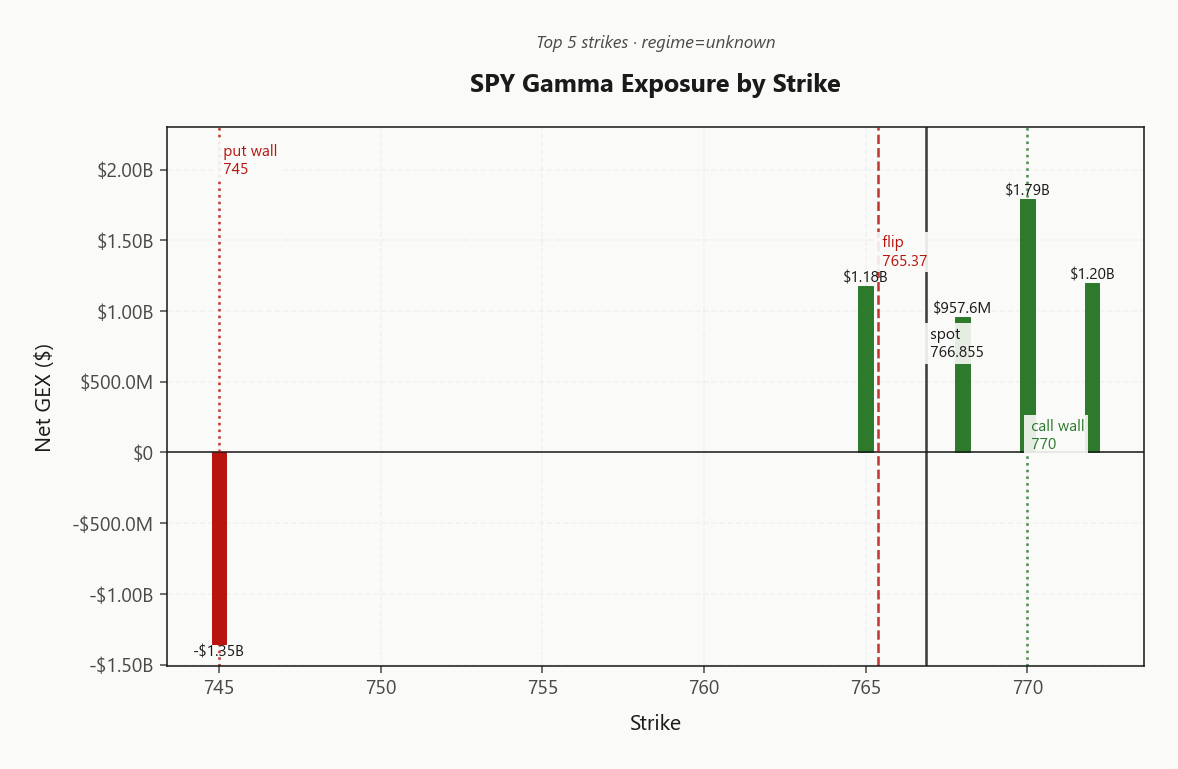
The book's center of gravity sits at 770.00, where $1.79B of positive net GEX pins the call wall 770.00 as today's ceiling. Dealer long-gamma at that strike forces sell-the-rip mechanics into any drift higher - the wall isn't a target, it's a magnet with a lid.
The highest-OI strike at 500 is a legacy artifact, not the live battleground. Real flow concentrates around the 770.00/745.00 corridor, with the gamma flip at 765.37 sitting just -0.1935877531 from spot. That's knife-edge proximity: a single decisive move through 765.37 flips dealer flow from dampening to amplifying and rewrites the tape's character for the session.
Trade the map, not the memory. Fade strength toward 770.00, respect 745.00 as the downside anchor, and treat any close below 765.37 as the trigger to strip short-vol exposure - the regime is Deep only above pivot.
What it means for your trading
SPY's microstructure hinges on the 765.37 pivot with spot just -0.1935877531 above it - the call wall at 770.00 caps upside via $1.79B of concentrated dealer gamma, while a break of the flip inverts the flow regime.
Trading readPositive gamma pile above spot in SPY and QQQ tells dealers to sell rallies and buy dips - mean-reversion wins today unless spot breaks the flip. The put wall below anchors downside; the call wall above is where drift stalls.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX prints -$137.49B - deeply negative and the hostile line item in today's greek stack. As long as VIX at 14.91 stays anchored, vanna sleeps; a pop unlocks aggressive dealer selling into the tape precisely because vol-up forces delta hedges out the door. Gamma dampening cannot offset it - the two greeks work at cross purposes the moment realized cracks.
Charm cuts the other way today. Net CHEX at -$3.5M with a Supportive bias means time decay pushes dealers toward buy-side flow into the close, cushioning drift and reinforcing the pin. That is the tape you are watching now - supportive charm masking a hostile vanna until the vol regime says otherwise.
The single number that matters is the Gamma Flip at 765.3704626356. Above it, dealer flow cushions and caps; below it, flow flips and amplifies. Spot sits -0.1935877531 from the line - trade the pivot, not the narrative.
What it means for your trading
Charm is doing the supportive work into the close while vanna sits loaded against a VIX pop - respect the 765.3704626356 pivot as the flow-flip trigger and watch 14.91 for the vanna unlock.
Cross-Asset Confirmation
MOVE prints 80.64 after ticking 5.8%% - rates vol has stirred but sits well outside credit-stress territory. No corroborating bid across the risk stack, no HY spread widening in the tape. This is a nudge, not a signal, and equity vol has correctly refused to follow.
Fear & Greed reads Fear at score 30 while VIX prints 14.91 - the classic washed-out contrarian setup where positioning is already defensive but realized tape is quiet. Hedges are on, not being chased. Upside surprise room outweighs downside grab-risk on a base-rate read.
The real cross-asset tell is the index regime split: QQQ at 730.78 holds Positive Gamma dampening while IWM at 285.14 sits Negative Gamma below its flip. Risk-on at the top of the cap stack, risk-off at the bottom - isolated equity fragility in small caps, not a macro credit event.
What it means for your trading
Cross-asset picture is Aligned with MOVE contained and F&G at Fear - trade the QQQ/IWM regime split, not a phantom macro crisis.
Scenario EV
The scenario engine returns Unknown with signal color Red - SPY balanced at the flip 765.3704626356 creates pivot ambiguity the auto-picker can't resolve. Fall back to the diagnostic: steep contango Steep contango - vol sellers favored, low VVIX/VIX at 5.85, thin SPY VRP 0.48%, and fat IWM VRP 2.27% together argue short-vol ladders belong on IWM, not SPY.
Optimal DTE sits at 21-30 where the contango slope from VIX9D 12.27 up through VIX3M 18.24 delivers the most convex roll-down. VRP assessment Unknown on the engine, but the manual read is unambiguous - an IWM iron condor around 290.00 / 280.00 captures the fattest premium of the complex while sidestepping SPY's flip risk and QQQ's inverted VRP.
What it means for your trading
Trust the diagnostic over the engine: IWM iron condor 21-30 DTE around 290.00 / 280.00 is the highest-EV structure while SPY sits pinned at 765.3704626356.
Actionable Summary
Bottom line: regime is Low / Carry with SPY balanced precisely on the gamma flip at 765.3704626356. The trade is short-vol carry, but not where the crowd puts it - IWM is where the premium lives while SPY sits in pivot ambiguity.
Optimal: IWM iron condor 21-30 DTE bracketing 290.00 and 280.00 - the fattest VRP in the complex at 2.27%, and steep contango front-slope 21.43%% pays the roll-down every quiet session. Avoid: naked short SPY vol at the flip 765.3704626356 - VRP is thin at 0.48% and a single move through pivot flips the flow regime; also step off long single-name calls in META where GEX churn is doing the price work.
Watch: SPY flip 765.3704626356, SPY call wall 770.00, IWM put wall 280.00, and VIX9D at 12.27 vs VIX3M 18.24 for the first sign the carry regime is cracking.
What it means for your trading
Regime is Low / Carry and sticky - trade the tape you see: harvest IWM VRP in the 21-30 DTE window, respect the SPY flip at 765.3704626356 as the single line that redefines flow direction.
Wells Fargo price target boost on Meta plus a strong futures open is doing real work in the tape - it's the catalyst behind the mega-cap GEX churn showing up in today's mover leaderboard.
A global diesel shortage extending into 2027 is a slow-burn inflation and industrial-margin risk that keeps MOVE bid at the margin even as equity vol stays suppressed.
AI stocks driving futures higher while oil slides is the exact tape that lets QQQ hold its long-gamma regime while broader risk sentiment stays cautious - the divergence is the story.
The Xi-Trump summit backdrop with China's trade engine humming is a scheduled tape risk - a headline surprise here is what forces the panic-transition probability higher than the base rate suggests.
Oil sliding to an 11-day low on US-Iran diplomacy hopes is exactly why MOVE's uptick isn't triggering an equity vol response - geopolitical risk premium is deflating in real time.
Trump's UNGA week of meetings is a calendar-loaded headline risk window - worth flagging as the reason to keep tail hedges on even in a carry regime.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.91 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at $4.32B. The gamma flip sits at 765.37, with the call wall at 770.00 and the put wall at 745.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at 765.37 against a spot of 766.86. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.64% with a volatility risk premium of 0.48%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.91. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime