Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 760.90 sits just under the gamma flip at 763.41 with net GEX -$10.43B - dealers are short gamma, so moves get amplified rather than dampened. Key levels: put wall at 760.00 is the magnet (max pain aligns at 760.00), call wall caps at 762.00, and the flip at 763.41 is the line above which dealer flow reverses. Net vanna -$86.73B means a vol spike sells more delta into weakness - asymmetric downside; charm $1.9M is roughly neutral into today. Vol read: VIX 15.23 down -14%%, term structure in steep contango (VIX9D 13.39 < VIX3M 18.55), VRP running 1.18% - options still rich to realized 9.62. Bottom line: fade tests of 762.00 and buy dips toward 760.00 inside the pin band; break of 763.41 to the upside flips the regime and unlocks trend.
SPY negative gamma below flip at 763.41; VIX contango, VVIX suppressed - mean-reversion regime with pinned wall
SPY 760.90 is pinned to the put wall at 760.00 with dealers short gamma below the 763.41 flip - a fragile floor that amplifies any downside push. Steep VIX contango (Steep Contango) and suppressed VVIX at 88.39 say vol sellers still get paid, but skew steepening warns the tail is bid. QQQ diverges from SPY/IWM regime alignment, which is today's tell.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
760.90
763.41
-0.33%
762
760
760
-$10.43B
Short gamma
QQQ
718.86
-
-
720
715
708
$2.20B
-
IWM
283.89
295.93
-4.07%
285
283
290
-$9.17B
Short gamma
VIX
15.26
15.22
+0.24%
20
15
20
$1.22M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.80
9.62
+1.18
2.37
2.62
1.22
QQQ
14.05
13.35
+0.70
4.76
1.43
1.13
IWM
15.67
12.40
+3.27
4.18
2.49
2.77
VIX
84.91
99.98
-15.07
-138.66
0.30
0.14
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
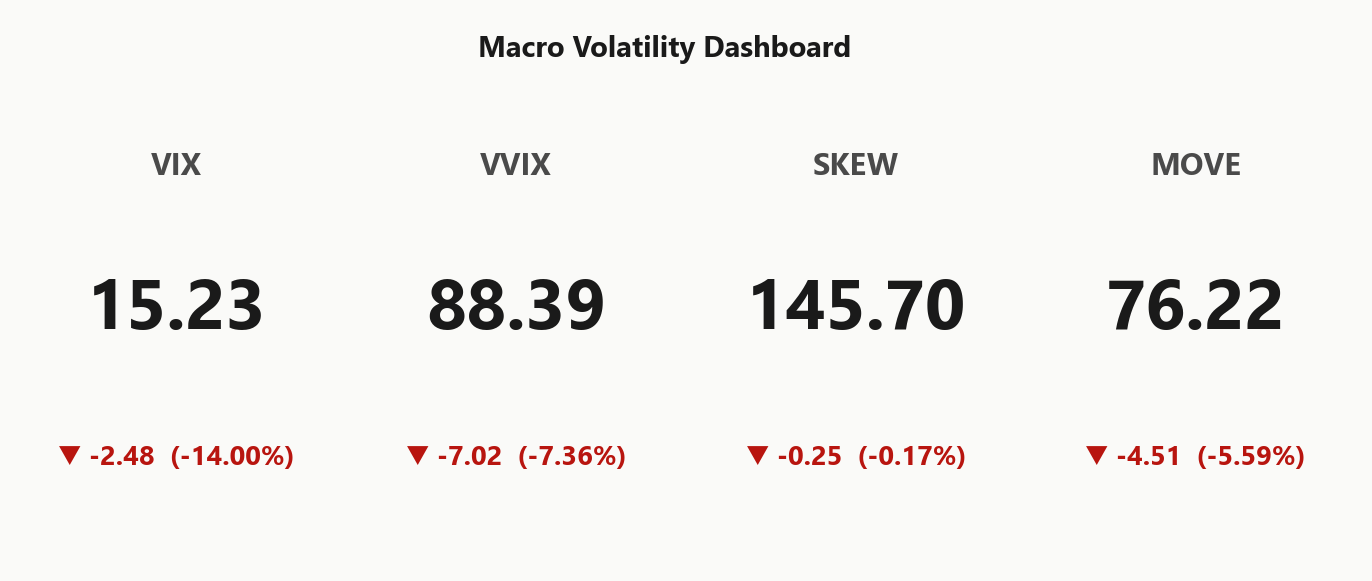
15.23
-14.00%
VVIX
88.39
-7.36%
SPX
7,639.58
+0.02%
SKEW index
145.70
-0.17%
MOVE (bond vol)
76.22
-5.59%
VIX term (9d/30d/3m/6m)
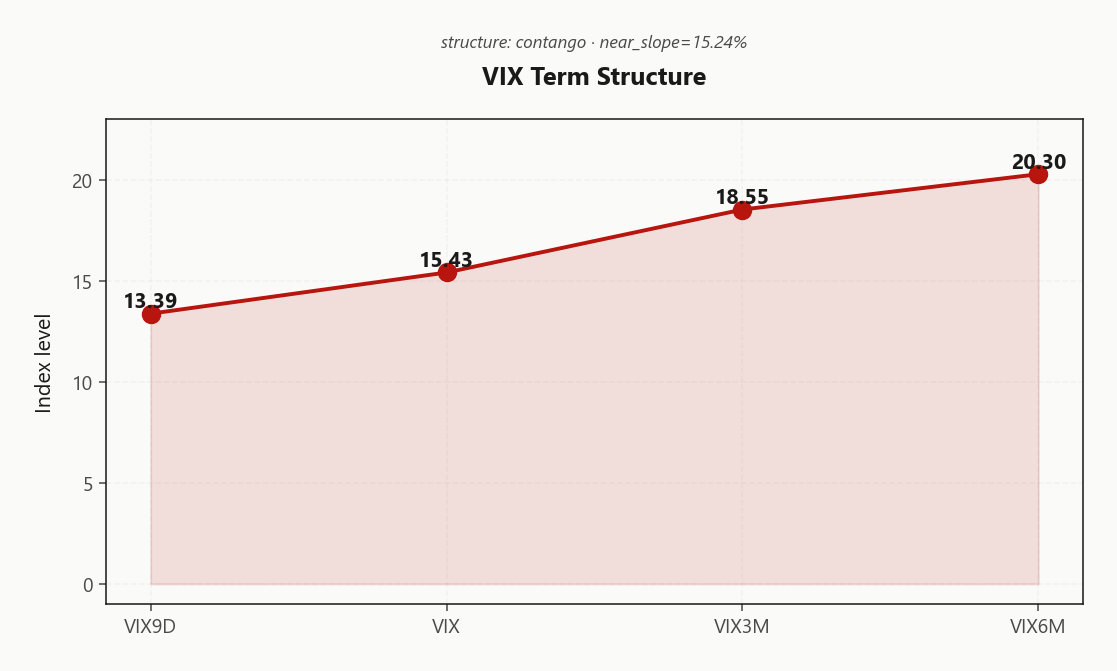
13.39 / 15.43 / 18.55 / 20.30
Steep contango
VVIX / VIX
5.80
Low
Regime
Elevated / Watchful
Regime Assessment
Tape sits in the Elevated / Watchful bucket with VIX at 15.23 - the Elevated regime that pays vol sellers but keeps the safety off. Transition math is the whole story: 0.05 probability of a panic jump over the next five sessions is non-zero and demands tight stops, while 0.45 odds of drifting into a calmer bucket over ten sessions is a near-coinflip that argues against front-running a vol crush.
Half-life clocks at 15 sessions - this state is sticky, not transitional. Plan structures for persistence: sell the belly of forward vol where Steep Contango pays carry, size to Standard Size per suppressed VVIX at 88.39, and treat the gamma flip at 760 as the regime-change trigger. A break there flips the amplification math and kills the elevated/watchful playbook.
What it means for your trading
Elevated but sticky regime: 15-session half-life means vol sellers get paid on carry, but 0.05 panic-transition odds keep the tail bid - size for persistence, hedge for the jump.
Trading readVIX down, VVIX down, MOVE down, SKEW slightly softer - all four are cooling in unison. That's cleaner alignment than divergence, which supports the mean-reversion thesis.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is in Steep Contango: VIX9D at 13.39 sits well below spot VIX 15.43 and VIX3M 18.55, with VIX6M 20.30 anchoring the long end. Structure prints Contango - the textbook carry tape for systematic short-vol.
Front-month VIX futures at 18.55 trade rich to spot at 20.22% basis, which is the market pricing an event bump between the 9D and 30D tenors rather than a clean glide lower. That kink is where calendar edge lives: sell the near, own the belly.
Forward 30 - 60 vol implies 19.9276516429 versus 60 - 90 at 21.9106709162 - the belly is the sweet spot for short vol, not the front where jump risk is priced. Signal color Green confirms structural carry; size for regime, not for hero.
What it means for your trading
Curve shape is Steep Contango with the front-month basis at 20.22% pricing an event bump - fade the near-slope premium and harvest the 30 - 60 belly where forward vol prints 19.9276516429.
Trading readContango slope of 15.24%% - carry trade is alive, but the front-month VIX future premium says the market prices a bump before it prices calm.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV at 10.8% continues to trade rich to trailing realized at 9.62, printing a VRP of 1.18% - the carry side of the tape is live and paying. Section signal reads Vrp Active: this is the harvest window, not the hedge window.
The tell is underneath. HV20 at 9.62 sits below HV60 at 11.29 - realized has been decelerating even as the longer-window print stays elevated. Trailing chop has cooled off a hotter tape, so the premium you're selling is priced against a decaying denominator. That's the textbook short-vol setup: implied rich, realized cooling, VRP asymmetry compounding day over day.
Discipline caveat: this is a Negative Gamma tape below the flip at 763.41. Selling vol against decelerating RV works - but dealer amplification means a single tail print reprices HV20 fast and closes the carry gap. Size to the regime, not to the VRP.
What it means for your trading
VRP at 1.18% with HV20 9.62 decelerating under HV60 11.29 says short-vol carry is paying, but the Negative Gamma regime caps sizing to defined-risk structures.
Skew Convexity
The 2.37% quarter-delta skew with a 1.35% smile ratio tells the whole story: put wing IV at 9.15% is bid asymmetrically against a softer call wing at 6.78%. The left tail is paying up even as the belly bleeds vol - hedgers are still willing to reach for downside convexity, but nobody is chasing upside.
ATM IV at 8.32% sits between the wings, which makes the belly the structurally cheap leg. Section reads Skew Steep - steep enough that naked put purchases overpay for the same protection a put spread delivers. Sell the rich wing against a closer-to-money long and let the smile do the work.
Call wing softness confirms vol markets are not pricing upside conviction - no reflex bid for calls even as spot probes the pin band. That asymmetry is the tell: the tape is defensive, not directional, and skew is charging you accordingly.
What it means for your trading
Skew at 2.37% with the wing gap between 9.15% and 6.78% says finance downside via put spreads, not naked puts - the belly at 8.32% is where the cheap vol lives.
Vol-of-Vol Structure
VVIX at 88.39 against VIX 15.23 prints a ratio of 5.80 - vol-of-vol classification Low, signal Green. Jump risk is being actively sold, with VVIX shedding -7.36% on the session. The market is not pricing a binary regime shift, and short-vol carry sizes at Standard Size.
This is the greenlight for structural premium sellers: when VVIX compresses alongside VIX, dealer gamma-of-vol is well-behaved and skew-hedging demand is muted. The carry environment is genuine, not artificial calm masking a coiled spring. The regime lines up with steep VIX contango and a Elevated / Watchful volatility state - vol sellers get paid, but the underlying tape still sits below the gamma flip.
The tell to watch: VVIX pushing back above the 100 handle marks the first crack in the sell-vol thesis. Until then, size normally, harvest the premium, and let the compressed vol-of-vol print carry the trade.
What it means for your trading
VVIX at 88.39 versus VIX 15.23 (5.80 ratio) classifies as Low - short-vol carry works at Standard Size. A break of VVIX above the 100 handle would be the first signal to pull risk.
Dispersion Spread
Cross-strike IV dispersion runs Moderate even with index ATM parked at 10.8% - the index tape looks tame while single-name variance carries the actual risk. Cross-strike dispersion at 91.71 versus cross-expiry at 3.5 confirms the wings are where the pricing tension lives, not the term axis.
Top GEX changes today cluster in AAPL, NVDA, and META - the mega-cap idiosyncratic engine is doing the heavy lifting behind the index print. That's why QQQ regime diverges from SPY/IWM: single-name gamma resets are dominating the tech benchmark while the broad complex sits pinned. Prefer SPX/SPY vol selling over single-name shorts - index premium is cleaner to harvest, and single-name skew carries tails that don't show up in aggregate IV.
Practical read: index hedges underperform in a stock-specific selloff. If the downside comes from one mega-cap earnings-adjacent print rather than a macro impulse, an SPY put spread bleeds while the actual damage concentrates in the offending ticker.
What it means for your trading
Dispersion at Moderate with cross-strike variance at 91.71 says the risk is idiosyncratic, not systemic - sell index vol, avoid single-name shorts, and don't trust SPY puts as a hedge against a mega-cap-led drawdown.
Liquidity & Microstructure
The headline OI cluster at 525 is a legacy artifact - far below spot and inert. The live book sits at the 760.00/762.00 band, where dealers are pressed short gamma and every tick gets amplified rather than absorbed. That's the pin the tape is trading against, not the strike screens flag.
The regime line is 763.41. Below it, dealer hedging is pro-cyclical - sells into weakness, buys into strength - which is the amplification math behind the fragile floor. Reclaim the flip and flow inverts to mean-reversion, killing the pin thesis and unlocking trend. Trade the level, not the chart around it.
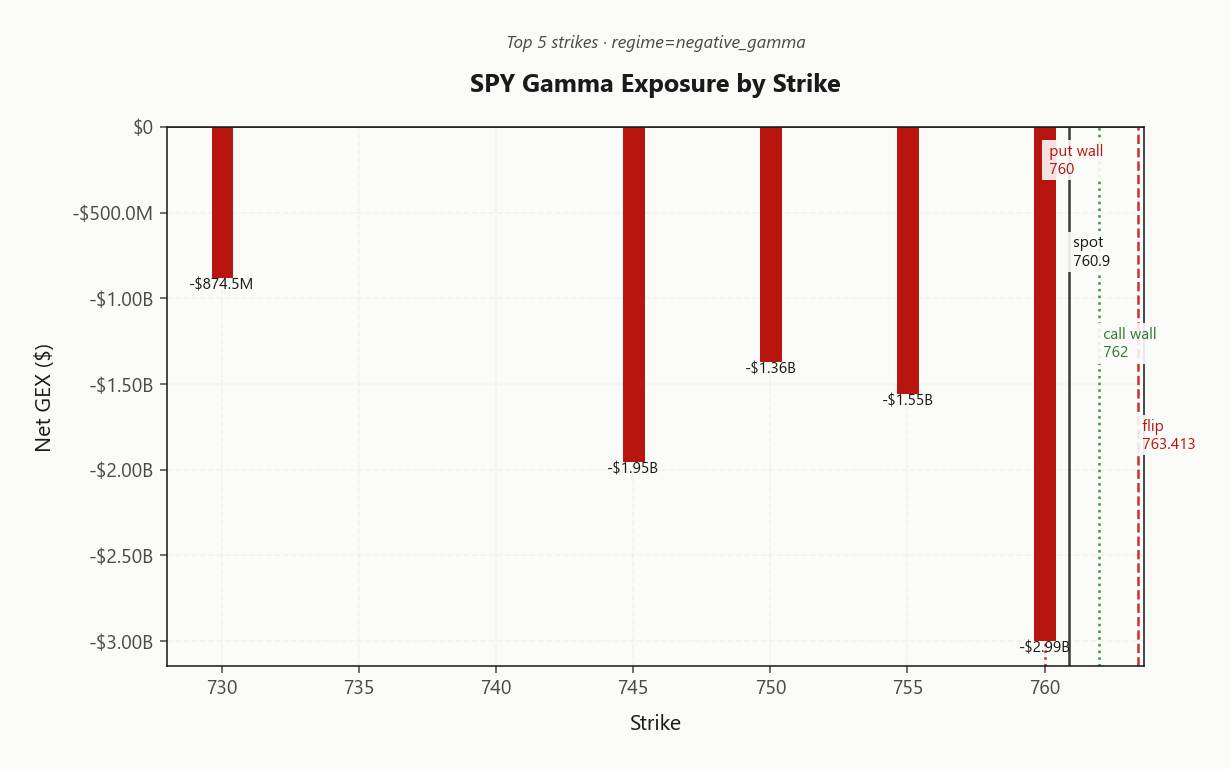
Dominance is one-sided: the top strike at 760.00 carries -$2.99B in net GEX - negative and concentrated enough to anchor intraday behavior. Fade tests of 762.00, buy dips toward 760.00 while the band holds, and treat a clean break of 763.41 as the signal to flip stance.
What it means for your trading
Live gamma sits at the 760.00/762.00 pin with the top strike 760.00 at -$2.99B dominating; 763.41 is the regime line - below it dealers amplify, above it they dampen.
Trading readDeep negative GEX concentrated at 760.00 means dealers amplify moves through that zone - trade the pin above 760.00 but expect knife-through-butter action if it breaks.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna at -$86.73B is the accelerant sitting under this tape. A VIX pop forces dealers to sell delta into weakness - the negative-gamma regime below the flip already amplifies moves, and vanna doubles the drag if vol re-rates. This is the asymmetric downside that suppressed VVIX at 88.39 is not pricing.
Charm reads $1.9M - effectively neutral into the bell. Bias is Neutral with the pivot at 760, spot hugging it at -0.118280983 away. Time decay isn't tipping dealer flow either direction, so the pin band holds by inertia rather than active support.
QQQ vanna at -$63.14B carries the same sign - this is an index-wide vulnerability, not an SPY-specific quirk. Treat any VIX bid as a spot-selling catalyst; the vanna-vol feedback loop is the trade to respect, not the charm pin.
What it means for your trading
Vanna is short and dominant, charm is neutral - the book is loaded for downside acceleration on any vol spike, with no offsetting decay bid to defend the 760 pivot.
Cross-Asset Confirmation
MOVE at 76.22 down -5.59% confirms bond vol is cooling in step with equity vol - no rate-driven risk-off is priced, which rules out the fastest transmission channel for a credit-led selloff. Fear & Greed at 28 (Fear) says positioning is defensive without being panicked; that's contrarian bounce fuel if the negative-gamma regime holds, not an override of it.
The tell today is QQQ at 718.86 printing an unknown regime while SPY and IWM sit aligned in negative gamma - mega-cap tech is disconnecting from the broad tape and small caps. IWM at 283.89 in the same fragile bucket as SPY means the risk-off channel, if it opens, runs through beta not benchmark. Cross-asset tone reads Unknown: aligned on the vol side, diverged on the equity side - trade the divergence, not the alignment.
What it means for your trading
Bond vol and sentiment both cooling (76.22, Fear) support the mean-reversion thesis, but QQQ regime divergence from SPY/IWM at 718.86 is the crack to watch - that's where a stock-specific unwind starts.
Scenario EV
The tape favors Iron Condor at 30-45 DTE, ranked at 38 against the put-spread alternative at 26. The belly of the forward vol curve is where carry compounds: near-tenor VIX9D sits well below VIX3M in steep_contango, and the 30-45 window captures the richest theta bleed without stretching into the term-premium bump.
VRP reads Unknown at the aggregate level, but ATM IV at 10.8% still trades above HV20 at 9.62 - carry present, not carry aggressive. Short strikes belong outside the 760.00/762.00 pin band, wide enough that a break of the gamma flip at 763.41 doesn't take the body of the trade.
Signal reads Yellow - the regime is elevated, half-life 15 sessions, and VVIX suppression at Low says no crisis pricing. Size half of full risk while the flip is unresolved; scale up on a reclaim of 763.41, cut on a break of 760.00.
What it means for your trading
Iron condor at 30-45 DTE outscores the put spread 38 to 26 because rich VRP and a tight pin band pay defined-risk short vol. Size half while the gamma flip at 763.41 is unresolved - the Yellow signal says carry, not conviction.
Actionable Summary
Bottom line: sell defined-risk vol via Iron Condor at 30-45 DTE, with short strikes framing the 760.00/762.00 pin band. The gamma flip at 760 is the regime-change line - trade against it, not through it.
Avoid naked puts (skew rich at 2.37%), single-name vol selling while dispersion runs Moderate, and any chase above 762.00. Size Standard Size - VVIX at 88.39 rules out crisis pricing, but vanna -$86.73B keeps the downside asymmetric.
Watch: a break of 760 unlocks trend and kills the pin thesis. Regime reads Elevated / Watchful with a 15-session half-life - plan for stickiness, not resolution.
What it means for your trading
Iron condor at 30-45 DTE inside the 760.00/762.00 pin is the trade; the gamma flip at 760 is the invalidation. Size Standard Size because Elevated / Watchful regimes stay sticky but break hard when they break.
Kremlin seizure of Nestlé's Russian assets escalates Western-corporate expropriation risk - watch for spillover to any multinational with meaningful Russia exposure.
Jet-financier stress from Iran-war fuel and borrowing costs is a slow-burn credit signal - airlines and lessors carry the tail; watch high-yield spreads.
Hormuz traffic below 10-day average with LNG vessels rerouting is the tape-level signal that supply-chain risk hasn't left - cross-check with tanker rates.
US sanctioning an Iranian crypto exchange tied to Hormuz payments signals financial-warfare escalation - watch crypto beta and sanctions-adjacent tickers.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.26 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 763.41 against a spot of 760.90. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.8% with a volatility risk premium of 1.18%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.23. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime