Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 758.78 sits in a negative-gamma regime with dealer net GEX at -$17B - moves get amplified, not dampened. Call wall 760.00 caps upside, put wall 755.00 is the first line of defense, and gamma flip at 762.69 is the switch: spot is just below it, so we're in the amplification zone but one push higher reactivates dealer buying. Dealer positioning is short delta (-$10.59B) with vanna hostile (-$62.15B) - any vol pop drags dealers to sell more delta, but charm is turning supportive into the close. Vol read is constructive for premium sellers: VIX 15.47 in Contango with near-slope 20.06%, VVIX 89.16 says vol-of-vol is quiet, VRP running 1.72% vol points rich to 20d realized. Bottom line: fade strikes into 760.00 with iron condors in 30-45 DTE - do NOT chase a break above 762.69 until dealers flip long.
Negative gamma across SPY/QQQ with VIX in Steep Contango - dealers amplify moves, mean-revert into walls
SPY trades below its gamma flip at 762.69 with dealers short -$17B of gamma, keeping moves amplified even as VIX cools to 15.47 in steep contango. QQQ mirrors the negative-gamma setup while VIX itself holds positive gamma, signaling vol-of-vol suppression and clean carry for premium sellers. Iron condor scoring dominates the 30-45 DTE window with VVIX at 89.16 greenlighting standard sizing.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
758.78
762.69
-0.51%
760
755
760
-$17.00B
Short gamma
QQQ
716.07
717.14
-0.15%
720
715
708
-$1.49B
Short gamma
IWM
282.80
294.57
-4.00%
285
282
290
-$9.49B
-
VIX
15.47
15.36
+0.73%
20
15
20
$11.13M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.02
9.30
+1.72
2.09
2.62
1.21
QQQ
14.22
13.09
+1.13
4.62
1.42
1.14
IWM
15.43
12.03
+3.40
1.80
2.51
2.43
VIX
84.85
99.99
-15.14
-135.71
0.30
0.34
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
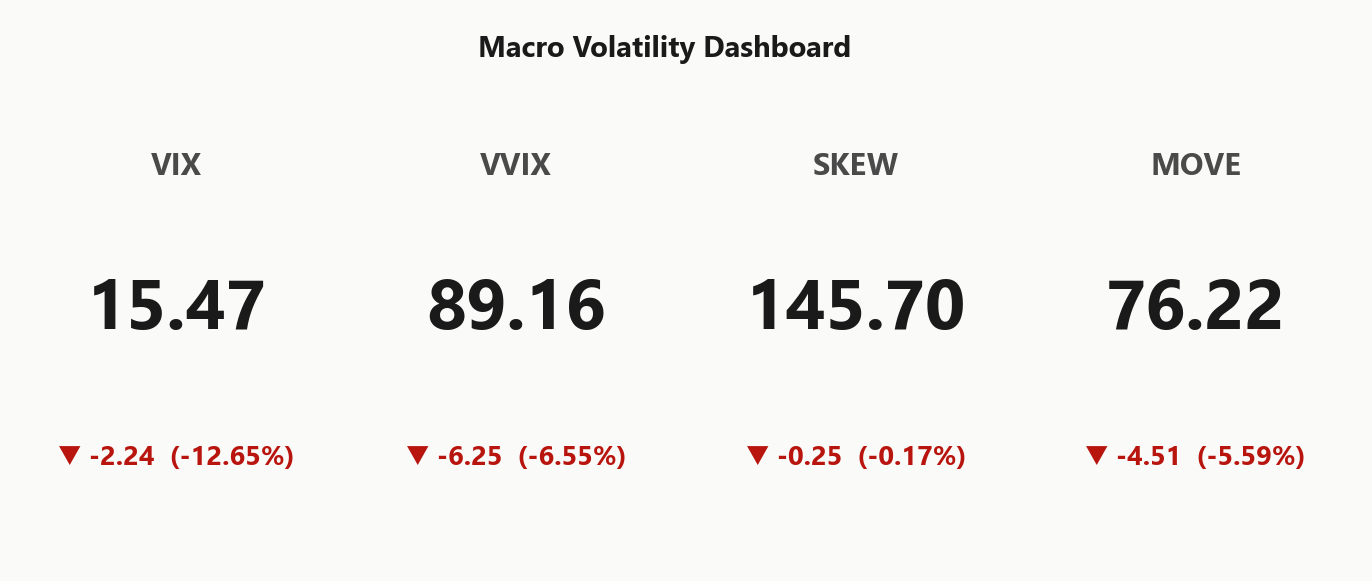
15.47
-12.65%
VVIX
89.16
-6.55%
SPX
7,618.08
-0.26%
SKEW index
145.70
-0.17%
MOVE (bond vol)
76.22
-5.59%
VIX term (9d/30d/3m/6m)
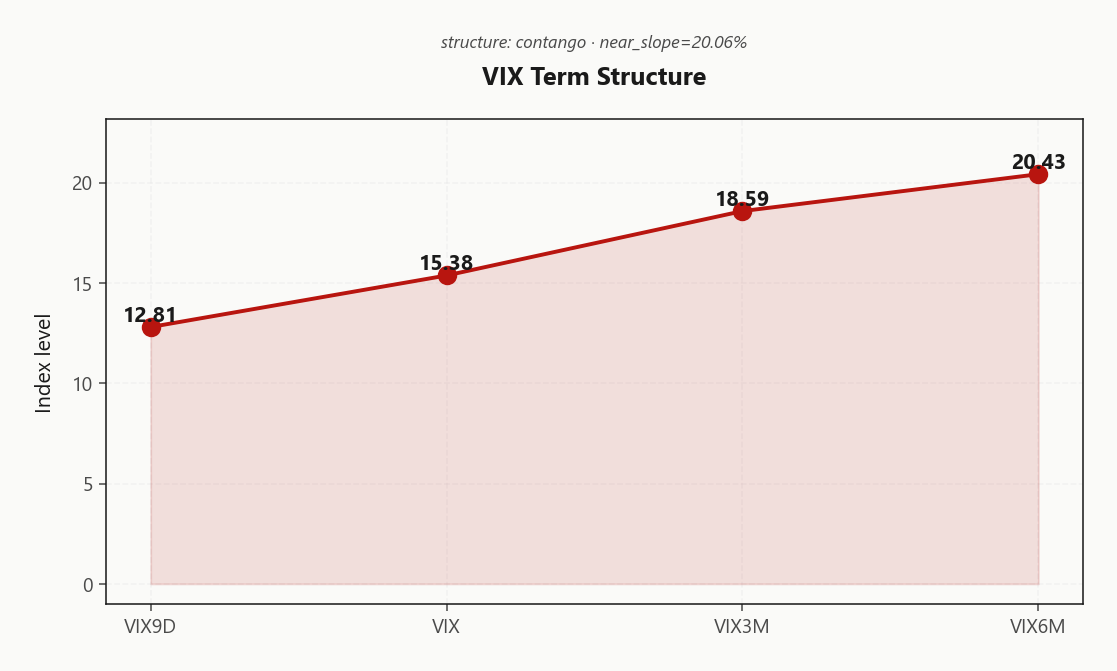
12.81 / 15.38 / 18.59 / 20.43
Steep contango
VVIX / VIX
5.76
Low
Regime
Elevated / Watchful
Regime Assessment
Regime read prints Elevated / Watchful with VIX anchored at 15.47 and a session half-life of 15 - sticky enough that carry trades keep the edge, not so hot that tails demand respect. Current state resolves to Elevated, and the transition matrix leaves the panic door effectively shut: five-session probability of a jump-to-panic reads 0.05, a negligible tail against the realistic mean-revert path where the ten-session probability of drifting into low-vol is 0.45.
Persistence is the trade. With half-life at 15 sessions the regime rewards structures that let theta and roll-down do the work - iron condors in the 30-45 DTE window, calendars into Steep Contango, and short-vol clips sized to Standard Size given VVIX quiet. Cross-asset tone is Aligned, MOVE at 76.22 confirms no rates spillover.
Signal color Yellow - stay watchful but engaged. Elevated is not stressed; the mean-revert path is the base case, the panic tail is the option you buy cheap on the wing, not the scenario you position around.
What it means for your trading
Regime prints Elevated / Watchful with a sticky 15-session half-life and a negligible 0.05 panic probability - carry trades favored, mean-revert path realistic at 0.45.
Trading readVIX down, VVIX down, MOVE down, SKEW flat - everything confirming the vol-suppression narrative. Divergence would require MOVE or SKEW to spike alone.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is Contango with VIX9D at 12.81 printing below spot VIX at 15.38 - no near-term event premium is being paid, and the front end is bleeding time value cleanly. Further out, VIX3M at 18.59 and VIX6M at 20.43 extend the slope, so the market is pricing meaningfully higher forward vol without any front-of-book urgency.
Forward 30-60 sits at 20.0027485611 against 60-90 at 22.1174523849, and that gap is where the carry lives - the 30-45 DTE window captures the steepest roll-down without stepping into the flatter belly. Sell near-dated vol against longer-dated protection; calendars and diagonals extract the term premium without leaning naked into a curve that could snap.
VIX curve in Steep Contango with VIX9D 12.81 under spot 15.38 - short front vol against 18.59-anchored longer-dated protection, cleanest carry in the N/A DTE bucket.
Trading readSteep contango at 20.06% slope - vol carry is real, roll-down works for short-vol structures, market pricing no immediate event risk.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM implied trades at 11.02% against a trailing 20-day realized print of 9.3 - options are paying a real, if Thin Premium, premium over what the tape has actually delivered. That gap is the entire case for short-vol structures here: realized is decelerating with RV5 at 11.24 rolling down toward RV20 at 9.3, so the short-window vol contribution is fading into the implied bid rather than fighting it.
Variance risk premium is running 1.72% vol points rich - sellers get paid, but the margin is thin enough that structure matters more than direction. With HV60 at 11.34 still elevated relative to the current spot regime, the longer-run vol footprint hasn't fully normalized, which argues for capped-risk premium harvest over naked shorts. Pair the front-end sale against the sticky back-end print and the carry lives in the 30-45 DTE window.
What it means for your trading
Options are paying Thin Premium over realized with RV5 11.24 decelerating into RV20 9.3 - VRP at 1.72% vol points validates premium sales, but only in capped structures given HV60 11.34 still carries a longer-run vol footprint.
Skew Convexity
The 2.09% quarter-delta skew with a 1.31% smile ratio reads as an ordered put bid - downside is bid, not panic-bid. Put quarter-delta IV at 8.84% sits modestly rich to ATM at 7.93%, while call quarter-delta IV at 6.75% trades flat-to-inverted versus ATM. Translation: dealers are paying up for hedges in size, but no one is paying up for the chase - upside convexity is on sale.
QQQ's smile ratio at 1.57% steepens the SPY read - the tech tail carries more premium, consistent with mega-cap idiosyncratic risk concentrated in NVDA, META, and AAPL. Cross-asset the regime is Aligned, so the skew signal isn't fighting the tape.
Trade construction: put spreads over naked puts - convexity is ordered, not screaming, so buying the wing outright overpays for a tail the market isn't pricing. Flat call skew argues against selling covered upside for yield; the strike simply doesn't pay. Iron condors in 30-45 DTE remain the cleanest expression, with the short put wing structured, not naked.
What it means for your trading
Skew is elevated but orderly at 2.09% - downside bid without panic - while flat call skew signals no upside conviction being paid. Structure downside via put spreads, not naked puts, and skip covered-call yield until the call wing repriches.
Vol-of-Vol Structure
VVIX at 89.16 against VIX 15.47 pins the ratio at 5.76, a Low vol-of-vol print that strips the bimodal tail out of the front curve. Jump premium is bleeding - VVIX contracted -6.55% intraday - and the flow underneath says nobody is paying up for a gap-risk hedge, only for orderly downside.
With the ratio compressed and the signal reading Green, the desk is cleared for Standard Size premium sales. That greenlight matters most in the 30-45 DTE bucket, where iron condors capture Contango carry without inheriting event-vol convexity.
Watch the ratio, not just the level - a VVIX reflation into a flat VIX is the first tell that the market is repricing jump risk, and that would force sizing back to defensive before spot ever moves.
What it means for your trading
Vol-of-vol reads Low with the VVIX/VIX ratio at 5.76, clearing Standard Size on short-premium structures in the 30-45 DTE window.
Dispersion Spread
Index vol screens suppressed against a mega-cap tape that is doing the actual work. SPY ATM at 11.02% sits meaningfully under QQQ ATM at 14.22%, a spread that says the tech complex is absorbing the idiosyncratic premium while the broad index gets damped by correlation drag. Cross-strike IV dispersion at 83.42 reads moderate - enough spread to matter, not enough to signal panic reallocation.
The mover board tells the same story from the positioning side: NVDA, META, and AAPL lead absolute GEX shifts, with MSFT and GOOGL rounding out a clean mega-cap sweep. Risk is concentrated in five names, and index-level hedges will not fully offset that idiosyncratic tail.
Trade the wrapper, not the constituents. Prefer SPY/SPX vol sales over shorting single-name premium - the index carries the correlation discount while single names carry the event beta. Basket short-vol structures capture the dispersion spread without shorting the names actually paying you to hold them long.
What it means for your trading
Index IV is cheap relative to mega-cap IV with dispersion at 83.42 - sell SPY/SPX vol against the mega-cap-heavy risk book rather than shorting single-name premium directly.
Liquidity & Microstructure
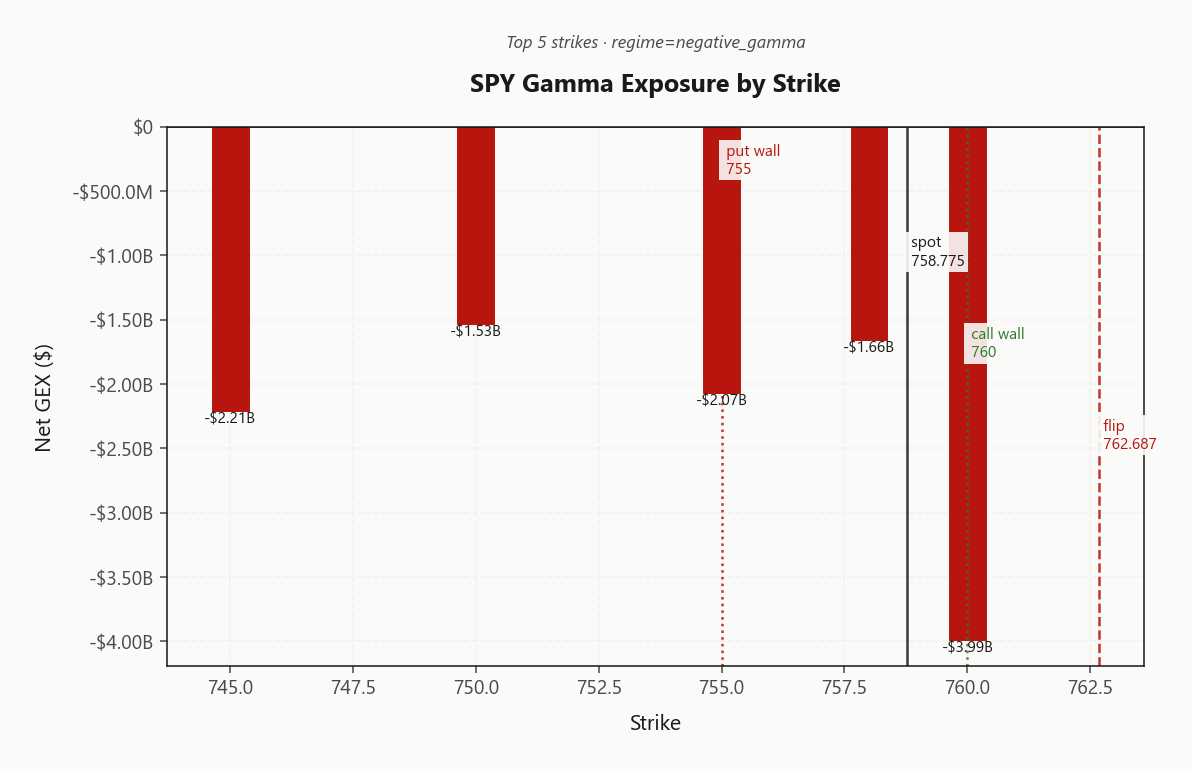
The gamma flip sits at 762.69 with spot pressed just below, turning 760.00 into the dominant magnet - that strike alone carries net GEX of -$3.99B, the heaviest cluster on the board. The call wall at 760.00 caps upside while the put wall at 755.00 anchors the downside shelf, framing a tight corridor where dealer flow does the routing.
Highest OI still resides at 525 - legacy positioning parked well below current spot, non-load-bearing for today's tape but a reminder that the book's structural weight sits far away from the action. The live pressure is at the flip: below it, dealers amplify every push; a clean break above 762.69 flips flow from amplifier to dampener and reactivates supportive hedging.
0DTE net GEX at -$10.09B represents 59.3% of the total book - intraday amplification dominates, and expiring flow will do the heavy lifting into the close. Trade the corridor, respect the flip.
What it means for your trading
Spot pinned below 762.69 with 760.00 as the dominant magnet - dealer flow amplifies until that flip clears, then dampens. 0DTE at 59.3% of the book keeps intraday chop the base case.
Trading readDealers short gamma across the SPY chain with the heaviest concentration at 760.00 - expect amplification below 762.69, mean-reversion pull toward 760.00 on any bounce.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer second-order Greeks paint a split picture: net vanna at -$62.15B is hostile to any vol expansion - a VIX pop drags dealers to sell more delta, accelerating downside - while charm at $9.9M turns supportive into the close, providing the mechanical drift that typically pins spot near heavy strikes.
The charm pivot sits at 760, a Call Wall level with current bias reading Neutral. Spot is only 0.1614444335 away - knife's edge. Below, decay pulls dealer flow one direction; a clean break above flips the mechanical bid and reactivates the buy-into-strength reflex.
QQQ mirrors the setup with net VEX at -$36.9B, so tech vanna risk is aligned rather than offsetting - a vol shock hits both books the same way, and index hedges won't get the cross-asset diversification that usually cushions negative-gamma regimes.
What it means for your trading
Vanna hostile, charm supportive, pivot at 760 - fade strength into the pivot and treat any VIX uptick as an accelerant, not a fade signal, until dealers flip long gamma.
Cross-Asset Confirmation
MOVE cools to 76.22 (-5.59%) while Fear & Greed prints Fear at 28 - bond vol is well-behaved and credit is not flinching, so the stress is equity-only, not a macro shock cascading through rates.
QQQ at 716.07 and IWM at 282.80 round out the picture: small-caps carry the heaviest short-gamma weight into the tape, tech tracks the same negative-gamma stance, and the vol product itself sits Positive Gamma. Cross-asset tone reads Unknown with regime divergence Aligned - every leg pointing the same way.
Contrarian bounce fuel is building under the F&G print, but without a MOVE or credit twitch to confirm, fade rips into 760.00 rather than front-run a reversal.
What it means for your trading
Bond vol at 76.22 and F&G at 28 confirm equity-isolated jitters - Aligned regime across SPY/QQQ/IWM keeps the short-vol carry trade intact, with IWM at 282.80 the softest leg to watch.
Scenario EV
The scoring matrix lands on Iron Condor as the dominant structure at 41, comfortably ahead of the put spread alternative at 29 - condors edge directional bets when the vol surface is this well-behaved and the regime is mean-reverting rather than trending.
Optimal window sits in the 30-45 DTE bucket, the sweet spot for theta capture that clears the near-week gamma noise but stays inside the steep Contango carry slope. VRP assessment reads Unknown, which validates the short-vol lean - options are paying above trailing realized without demanding tail-risk premium.
VVIX at Low greenlights Standard Size - no bimodal jump risk being priced, so this is a full-clip premium harvest window, not a probe.
What it means for your trading
Iron condors win the setup at 41 versus the put spread's 29, with the 30-45 DTE window offering the cleanest theta capture. VRP Unknown plus Low vol-of-vol equals classic short-vol carry conditions.
Actionable Summary
Primary trade:Iron Condor in 30-45 DTE, centered around 760 - the charm pivot doubles as the 760.00 magnet, giving the short strikes a structural anchor while VRP at 1.72% pays sellers to sit through the chop.
Avoid chasing directional upside until spot clears 762.69 - dealers remain short -$17B of gamma below the flip, so every push higher gets faded, not extended. Watch755.00: a clean break flips the tape from mean-revert to panic-acceleration and forces condor rolls or full unwind.
Sizing:Standard Size - VVIX at Low with ratio 5.76 greenlights the full clip. Regime read:Elevated / Watchful with a 15-session half-life - carry trades favored, but keep hedges honest.
iPhone 18 launch day at Apple stores - AAPL is a top-5 GEX mover, and retail flow around launch typically amplifies single-name gamma into weekly expiries.
Cramer's Fed rate-hiking playbook - matters because rate regime shifts drive the MOVE/VIX correlation that's currently supportive of the negative-gamma equity setup.
Trump faces skeptical world leaders at UN over Iran war - geopolitical tail risk that's currently muted in MOVE at 76.22 but could reprice tail vol quickly.
Hormuz traffic below 10-day average, LNG vessels reappear - energy supply chain read that ties to oil vol and inflation expectations, indirect equity impact.
Oil pares losses on Saudi supply concerns and Middle East tensions - crude vol is a leading indicator for MOVE and could disrupt the current contango carry regime.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.47 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Negative Gamma gamma with net dealer GEX at -$17B. The gamma flip sits at 762.69, with the call wall at 760.00 and the put wall at 755.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at 762.69 against a spot of 758.78. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.02% with a volatility risk premium of 1.72%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.47. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime