Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closes at 762.84 with net GEX -$2.7B - dealers still short gamma below the flip at 763.78, so intraday moves amplified rather than dampened. Call wall 770.00 caps upside, put wall 745.00 is the trapdoor; max pain 760.00 sits inside the range and pins the tape. Dealer vanna -$110.22B and charm -$874.3K both destabilizing - vol up feeds delta selling, into-close decay leans offer. VIX 14.86 with term structure Contango at slope 21.53%%, VVIX 87.59 calm - carry regime Low / Carry, but VRP 1.01% is thin and the fear/greed reads Fear at 29, a tell that positioning is defensive. Bottom line: sell premium in the 21-30 DTE window per 21-30 but keep condor wings inside 770.00/745.00 and cut if spot slips under 763.78.
Low-vol carry regime: VIX 14.86, steep contango, but SPY sits below charm pivot at 763.7826541281
VIX collapsed to 14.86 and the term structure is in steep contango (Steep contango - vol sellers favored), which normally green-lights carry - but SPY at 762.84 still trades under the gamma flip at 763.78, so dealers remain short gamma and vanna/charm point destabilizing. The regime label reads Low / Carry, yet the pivot is fragile: one push through 745.00 reawakens the amplifier. Carry is available; conviction is not.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
762.84
763.78
-0.12%
770
745
760
-$2.70B
-
QQQ
722.49
-
-
725
700
707
$1.85B
-
IWM
284.14
294.64
-3.56%
300
280
290
-$3.69B
-
VIX
14.81
-
-
20
14.50
20
$12.89M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.18
9.17
+1.01
1.94
2.62
1.11
QQQ
13.75
13.11
+0.64
3.86
1.42
1.06
IWM
14.22
11.83
+2.39
2.17
2.50
2.22
VIX
92.85
100.68
-7.83
-147.92
0.31
0.22
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
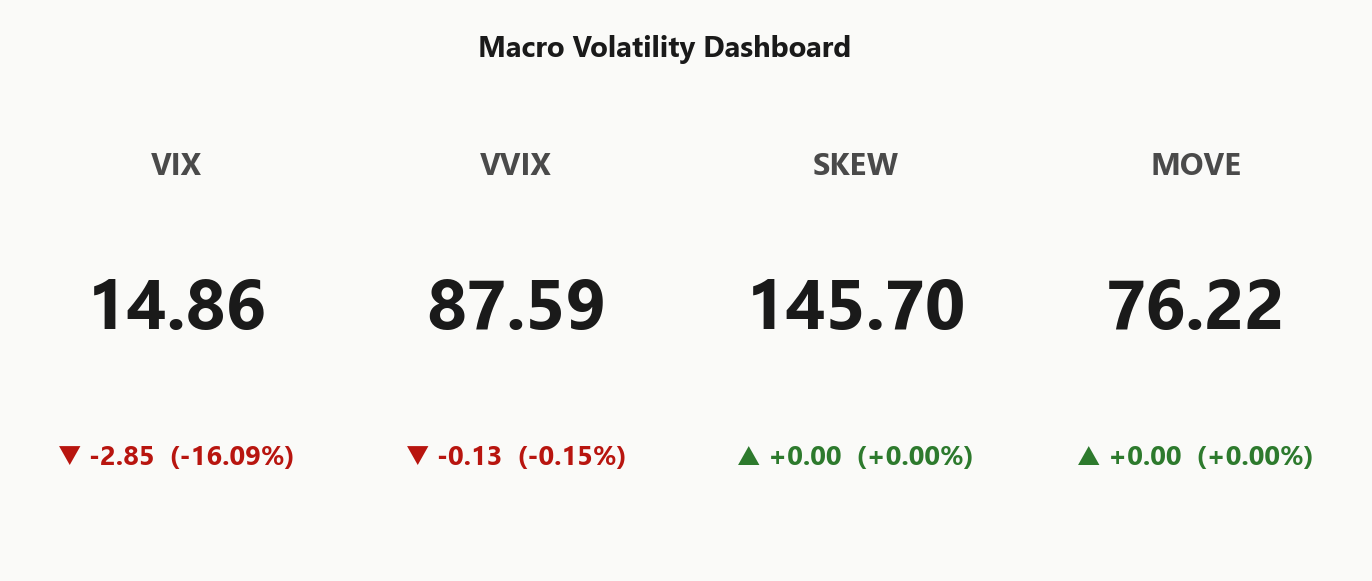
14.86
-16.09%
VVIX
87.59
-0.15%
SPX
7,650.50
+0.17%
SKEW index
145.70
0.00%
MOVE (bond vol)
76.22
0.00%
VIX term (9d/30d/3m/6m)
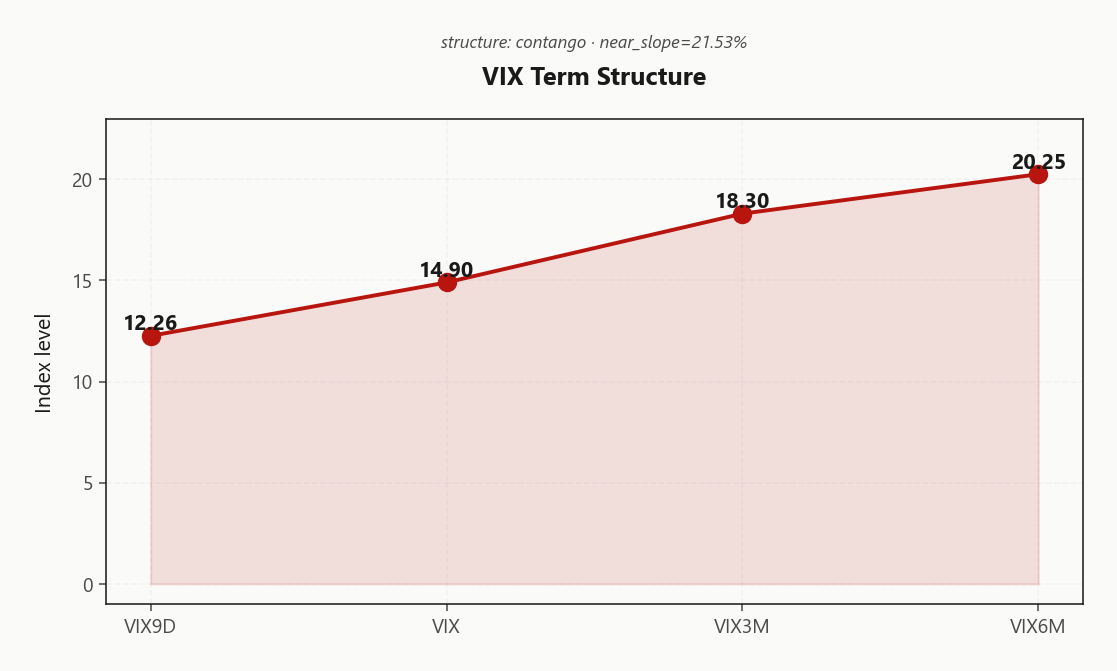
12.26 / 14.90 / 18.30 / 20.25
Steep contango
VVIX / VIX
5.89
Low
Regime
Low / Carry
Regime Assessment
The regime tape reads Low / Carry with VIX pinned at 14.86 - the low-vol carry bucket is the operative frame, and the transition math confirms it. Five-session panic odds sit at 0.05: low, but nonzero, and the short-gamma dealer footprint below the flip is what keeps that tail alive rather than dead. Ten-session odds of staying in the low bucket read 0.45, which is the number that matters for anyone sizing a premium-sale book this week.
Half-life is the tell. At 30 sessions the regime is sticky - not a print that flips on a single headline, but a state that decays slowly. That is weeks of window for premium harvest, not days, and it reframes the trade: position for persistence, not transition. Fade the impulse to hedge the regime itself; hedge the pivot at 763.7826541281 instead, which is where the plumbing actually breaks.
Bottom line: sell into the carry, respect the flip, and let the half-life do the compounding.
What it means for your trading
Low/carry regime with a 30-session half-life gives a genuine window for premium harvest; the 0.05 panic tail is small but the short-gamma setup below 763.7826541281 means the kill switch, not the regime call, is what protects the book.
Trading readVIX collapsed, VVIX calm, MOVE contained, SKEW at 145.70 still elevated - the wings still price a tail even as the body prices peace. That divergence is your reason to keep protection on cheap when carrying the short vol book.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX complex sits in Steep Contango with the front week at 12.26 trading under spot VIX at 14.90 - no near-term catalyst is priced. The back end pushes to 18.30 and 20.25, a curve that expects mean reversion higher rather than a shock print.
Forward vol in the 30-60 window sits at 19.782062582, well above spot - that is where the roll-down carry lives and where the Steep contango - vol sellers favored signal pays. The 60-90 forward at 22.0280502996 prices normalization, not systemic stress; the wing has no urgent bid.
Structure reads Contango - sell the front, hold the back, harvest the compression. The trade breaks only if the front week reclaims spot or the flip level gives way.
What it means for your trading
Steep contango with the 30-60 DTE forward at 19.782062582 versus spot VIX 14.90 - carry window is open, roll pays, no shock priced past 20.25.
Trading readSteep contango at slope 21.53%% says roll-down carry is the trade of the week - short front, long back, harvest the compression. Only a break of the flip level ends this setup.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Realized has bled under implied and the print looks clean on the surface: HV20 at 9.17 against ATM IV of 10.18% leaves a positive spread, and the VRP tag of 1.01% is what greenlights the carry regime label. But the gap is thin - closer to fair than rich, and nowhere near the compensation short-vol books historically demand when dealer flow leans destabilizing.
The tail argues for restraint. HV60 at 11.3 still prints above current ATM IV, which means the recent tape's fatter days remain in the writer's rearview and any mean-reversion of realized higher wipes the edge quickly. IV-RV assessment reads Unknown - a signal to clip, not to load.
Net: cheap options for dip buyers, mediocre premium for sellers. Take small size, keep DTE inside 21-30, and let the dispersion trade carry the book where the premium actually pays.
What it means for your trading
VRP is live but shallow - HV20 sits under ATM IV of 10.18% while HV60 at 11.3 still overhangs the write. Half-size any premium sale; the spread doesn't underwrite full clips.
Skew Convexity
Quarter-delta skew prints 1.94% with a smile ratio of 1.33% - puts pay up over calls, but the curve is orderly, not panicked. The put wing at 7.91% sits well above the call wing at 5.97%, framing the ATM anchor at 6.98%. Downside insurance is bid, but the tail is not being chased - the wing is priced, not stressed.
Convexity reads steep without the panic premium, which changes the vehicle. Naked puts overpay for a distribution the smile is not actually pricing; the same downside beta lives cheaper inside a put spread, where the far leg finances the near. On the call side, the flat profile says there is zero upside conviction bid - calendars sold into strength are a one-sided trade, buying decay against a curve that has no reason to steepen.
Play the asymmetry as it is quoted: convex on the put side, dead on the call side. Structure downside as spreads, skip the upside calendar, and let the orderly wing do the work.
What it means for your trading
Skew at 1.94% and smile ratio 1.33% mark a convex-but-orderly curve - pay for downside via spreads, not naked puts, and pass on upside calendars while call skew stays flat.
Vol-of-Vol Structure
VVIX prints 87.59 against spot VIX at 14.86, a ratio of 5.89 that reads Low. The vol-of-vol complex is quiet - no urgent gamma bid clustering in the wings, no bimodal tell in the tape. Jump-risk premium is not extreme, and the wings are not being accumulated ahead of the tape.
Read directly: dealers are not paying up for convexity insurance, and neither is the fast money. Sizing guidance reads Standard Size - full clip on premium sales is on the table so far as this metric governs. The vol-of-vol green light removes one veto from the carry trade, though the destabilizing dealer setup below the flip still argues for restraint on the aggregate book.
The tell to watch: VVIX/VIX breaking higher from 5.89 is the first cross-check that regime is shifting. Ratio expansion without a spot VIX pop is the classical fingerprint of wing accumulation ahead of a repricing. Until that prints, treat vol-of-vol as a permissive input, not the binding constraint.
What it means for your trading
Vol-of-vol reads Low at a VVIX/VIX of 5.89 - Standard Size permitted on premium sales, with a widening ratio the first regime-shift tell to fade.
Dispersion Spread
Index vol trades compressed: SPY ATM IV at 10.18% sits well under QQQ at 13.75%, with IWM anchoring the premium end at 14.22%. Correlation reads moderate - enough dispersion in the single-name book to make index carry the cleaner harvest, not enough to force a defensive rewrite.
The trade writes itself: short SPY strangle against long QQQ single-name wings, with IWM held in reserve as the sticky-premium leg. Index carry beats single-name carry on the print, and the mega-cap gamma movers (META, AAPL, NVDA, MSFT, GOOGL) supply the idiosyncratic wing bid that keeps the basket honest.
Dispersion lives, but it is not a fat pitch. VRP is thin across the complex and dealer flow reads destabilizing below the flip - size the index leg to half, keep the single-name wings inside 770.00/745.00, and cut if SPY loses 763.7826541281.
What it means for your trading
SPY IV at 10.18% compressed against QQQ at 13.75% and IWM at 14.22% - the dispersion trade is alive, and short index vol against long single-name wings is the cleanest expression. Size half; thin VRP and destabilizing dealer flow make this an edge trade, not a conviction trade.
Liquidity & Microstructure
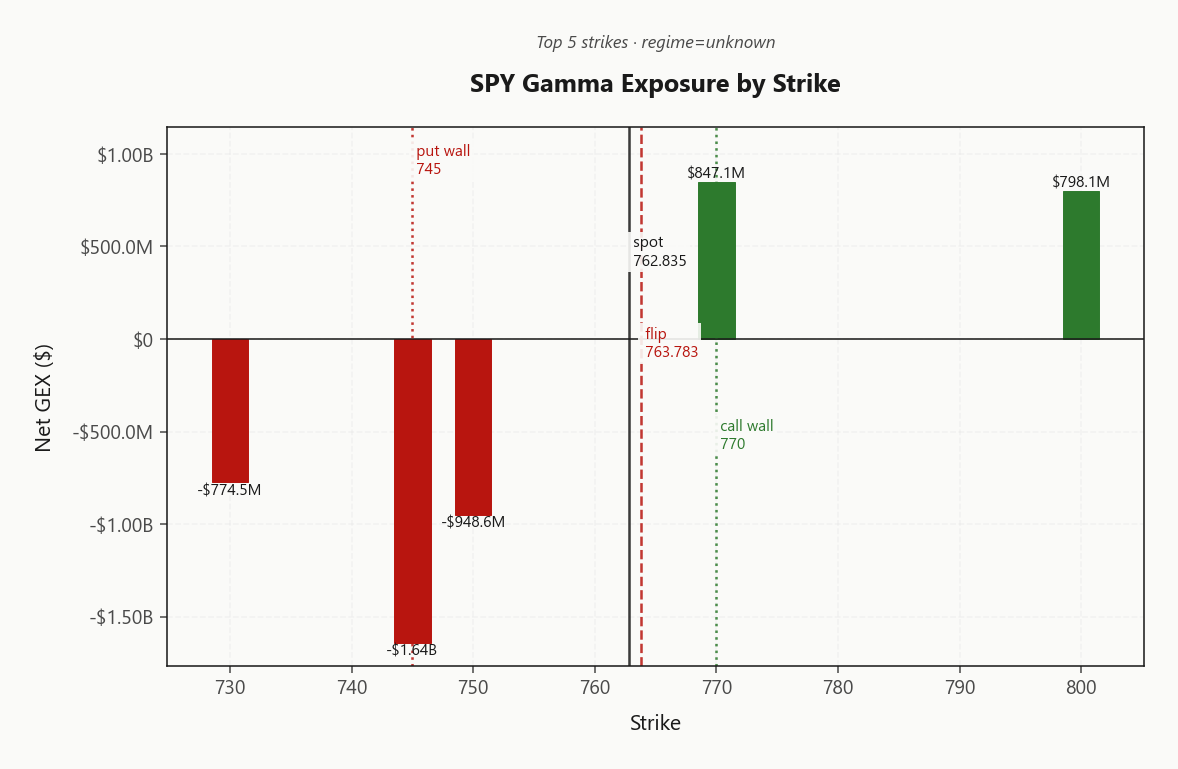
Open interest still anchors to the legacy 525 strike, but that ledger is stale - the live gamma book has migrated up the tape and now sits framed between the put wall at 745.00 and the call wall at 770.00. The top active strike at 745.00 carries -$1.64B of net gamma and defines the intraday pin.
The gamma flip at 763.78 is the single line that matters. Spot at 762.84 trades just underneath it - dealers remain short gamma, so tape moves amplify rather than dampen. The call wall caps every rally attempt into 770.00; the put wall at 745.00 is the trapdoor where the amplifier turns cascade.
Reclaim of 763.78 flips the microstructure from amplifier to dampener - until then, trade the range, not the break.
What it means for your trading
Live gamma book sits framed between 745.00 and 770.00 with the flip at 763.78 as the regime switch. Spot below the flip keeps dealer flow destabilizing - pin the range, respect the walls, and treat a break of 745.00 as the kill trigger.
Trading readNegative net gamma below spot and a hard positive cluster at the call wall - dealers amplify weakness inside the pin range then fade rallies into 770.00. Trade the range, don't chase a break in either direction until the flip is reclaimed.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Charm reads Time decay pushing dealers to sell - pressure into close - into-close decay leans offer, so the last hour tilts against longs while spot trades under the pivot at 763.7826541281. The distance is small, but the sign matters more than the size: below the line, every hedge flow points destabilizing.
Reclaim of 763.7826541281 flips the entire book - vanna and charm convert from foe to friend, and the carry regime finally trades clean. Until then, treat premium sales as a rental, not a residency, and keep the kill switch inside 745.00.
What it means for your trading
Vanna and charm both destabilizing with SPY under the pivot at 763.7826541281 - dealer flow amplifies weakness and leans offer into the close. Reclaim of the flip is the single condition that converts the setup from foe to friend.
Cross-Asset Confirmation
MOVE at 76.22 sits contained - the rates complex is not confirming an equity stress print, and without a bond-market panic bid the tape has no external accelerant. QQQ holds 722.49 and IWM anchors at 284.14; no small-cap capitulation, no mega-cap flush. Cross-asset tone reads Unknown with regime divergence Aligned - the indices point the same direction even as their gamma structures fragment underneath.
Fear & Greed at 29 registers Fear while VIX prints low - the classic contrarian setup, sentiment defensive into a suppressed vol tape. This is positioning fatigue, not systemic risk: hedges stacked, catalyst absent, credit quiet. The trade is to fade the sentiment tell only once spot reclaims the charm pivot at 763.7826541281; until then, defensive positioning owns the tape and the contrarian long is a passenger.
What it means for your trading
Cross-asset stress is absent - MOVE contained, small-caps holding, indices Aligned. Fear reading with VIX low is a contrarian buy tell, but only after the flip level reclaims.
Scenario EV
Scenario EV prints Unknown with VRP assessment Unknown and signal Red - the model green-lights the structure, but the tape does not corroborate. VRP at 1.01% is thin, and net VEX at -$110.22B alongside net CHEX at -$874.3K both read destabilizing while spot sits under the charm pivot at 763.7826541281. Treat the recommendation as guidance, not gospel - size half.
Anchor the DTE window at 21-30: far enough out to dodge the 0DTE noise where net gamma reads $0, close enough in to sidestep the far-dated vega bid still lodged out at 20.25. VVIX at 87.59 with a ratio of 5.89 permits standard clip per Standard Size, but the charm pivot argues restraint. Wings inside 770.00 and 745.00; kill switch a print through 763.7826541281.
Skip entirely if VIX ticks under 12.26 - the roll-down carry has already been harvested and the residual premium does not clear costs.
Regime tag is Low / Carry and VIX contango is steep, but SPY still trades under the flip at 763.7826541281 - dealer bias reads Destabilizing. Carry is on offer, conviction is not. Sell premium in the 21-30 DTE band, structure Unknown, wings pinned inside 770.00 and 745.00. Kill switch is spot losing the pivot - flatten there, no debate.
Skew is orderly at 1.94%, so avoid naked puts - vertical spreads pay the same beta cheaper. Halve any single-name premium sale; index dispersion runs richer against 13.75% single-name IV. Ignore the 0DTE tape - net gamma at $0 is negligible today. Reclaim of the flip flips vanna and charm back to friend; until then, size half.
What it means for your trading
Carry regime Low / Carry with contango pays, but the flip at 763.7826541281 is the single line separating harvest from cascade - trade the range, not the break.
US troop deaths in Iran conflict revised higher - a slow-burn geopolitical premium that keeps a floor under crude and the MOVE index without forcing an equity gap
Cyber-stock profit-taking flagged by the Investing Club - sector rotation tell that idiosyncratic risk is not being hedged by index puts, reinforcing the dispersion trade
Global rates reset, AI angst, oil's long haul commentary - the three macro cross-currents that explain why the term curve stays contango while sentiment reads Fear
Putin targets Nestle Russian assets - reminder that Western-asset seizure risk is a slow-burn tail that keeps European vol bid even when US spot vol collapses
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.81 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at -$2.7B. The gamma flip sits at 763.78, with the call wall at 770.00 and the put wall at 745.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at 763.78 against a spot of 762.84. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.18% with a volatility risk premium of 1.01%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.86. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime