Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 761.05, sitting just below the 764.74 gamma flip in a Negative Gamma regime with net GEX at -$4.03B - dealers short gamma, moves amplified in both directions. Key levels: call wall 765.00, put wall 760.00, max pain 754.00 - spot pinned to the put wall which is acting as the charm pivot. Dealer positioning shows net vanna at -$110.04B - vol up sells delta, amplifying downside if VIX bounces - and charm at -$6.3M pressuring dealers to sell into close. Vol read: VIX at 15.64 (down -9.07%%) with contango slope -11.32%%, VVIX at 90.72 = normal vol-of-vol, VRP at 3.24% = premium sellers paid over 20d RV of 8.65. Bottom line: iron condor 30-45 DTE is the structural fit - VRP is active, term structure supports carry, but stay ready to defend the 760.00 pivot if it breaks.
Negative gamma in SPY/IWM, contango VIX, dealers short vol into 760 put wall
SPY trades at 761.05 in negative-gamma territory below the 764.74 flip, with dealers positioned to amplify moves in either direction. VIX at 15.64 with a contango term structure signals structural vol carry is intact, while VVIX at 90.72 keeps sizing normal. The lead story is regime divergence - QQQ diverges from SPY/IWM, and the 760 put wall is the pivot the tape defends.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
761.05
764.74
-0.48%
765
760
754
-$4.03B
Short gamma
QQQ
714.32
-
-
720
700
705
$920.73M
-
IWM
286.96
294.48
-2.55%
290
285
290
-$6.28B
Short gamma
VIX
15.67
16.26
-3.66%
20
15
20
-$9.80M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.89
8.65
+3.24
9.10
2.53
1.29
QQQ
15.47
11.73
+3.74
3.56
1.44
1.29
IWM
16.63
12.37
+4.26
2.70
2.54
3.10
VIX
78.43
101.60
-23.17
-124.81
0.30
1.16
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
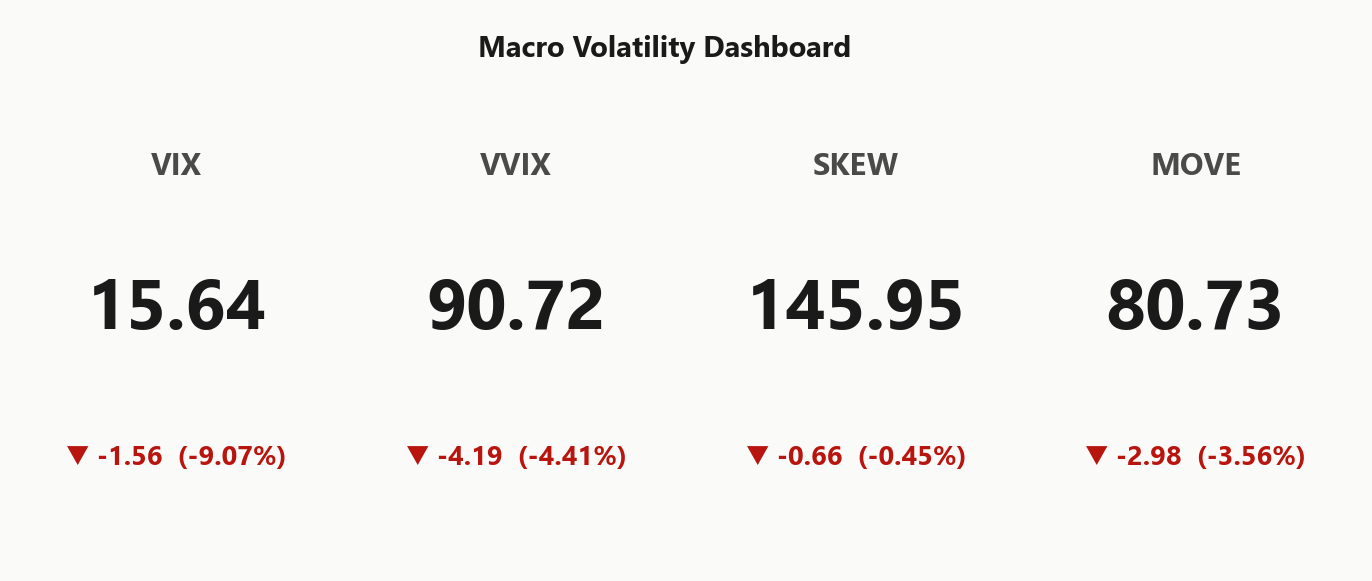
15.64
-9.07%
VVIX
90.72
-4.41%
SPX
7,621.98
+0.93%
SKEW index
145.95
-0.45%
MOVE (bond vol)
80.73
-3.56%
VIX term (9d/30d/3m/6m)
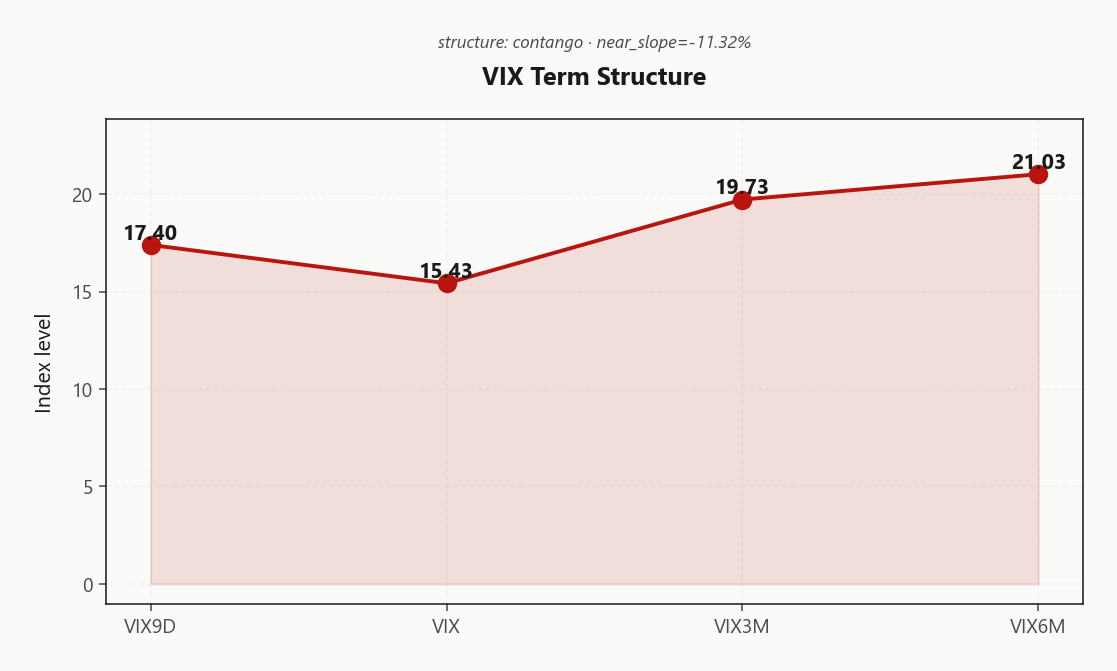
17.40 / 15.43 / 19.73 / 21.03
Flat
VVIX / VIX
5.80
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in an Elevated / Watchful regime with VIX at 15.64 - not benign, not panic, and critically sticky. Half-life on the current state runs 15 sessions, meaning today's setup is the setup you're trading into next week, not something that decays by tomorrow's open. Positioning premium sellers with strict defense lines, not chasing a resolution.
Transition math frames the tails cleanly. Probability of stepping to panic over the next five sessions prints at 0.05 - low but nonzero, which is why the tail hedge stays on rather than getting monetized. Probability of resolving down to a low-vol regime over ten sessions runs materially higher at 0.25, so the base case still tilts toward carry paying, not blowing up.
Cross-asset confirmation reads Unknown with QQQ divergent from the SPY/IWM negative-gamma complex - tech is the shock absorber, small caps the fragile leg. Structure of choice remains Iron Condor in the 30-45 DTE window, sized standard per VVIX, defended at the 760 put wall.
What it means for your trading
Elevated / watchful regime with a 15-session half-life is the read - patient premium collection is paid, but the 760 put wall is the non-negotiable defense line where flow turns hostile.
Trading readVIX easing while VVIX/VIX ratio stays elevated and SKEW holds firm - this is the classic 'quiet on the surface, tail bid underneath' setup that precedes regime shifts. Not a screaming warning, but not all clear either.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints Contango from spot out to six months, with VIX at 15.43, the three-month at 19.73, and the six-month at 21.03. Near slope reads -11.32%, but the VIX9D at 17.40 sits above spot VIX - localized event bid in the front week even as the term carries.
That geometry is the setup: front-week hedge demand fades into structural contango further out, and the belly of the curve is where premium sellers get paid without eating the event kink. Forward vol between the thirty-and-sixty and sixty-and-ninety windows expands into the higher three- and six-month prints, giving the 30-45 DTE window the cleanest carry against the Negative Gamma spot regime.
Term regime flags Flat term structure, so this is carry, not conviction - harvest the belly, avoid the front-week kink.
What it means for your trading
Contango out the curve with a bid VIX9D says sell the belly, not the front week - 30-45 DTE is where forward vol geometry compensates best for the Negative Gamma spot tape.
Trading readContango with a modestly bid VIX9D says near-term hedge demand hasn't gone away even as longer-dated vol carries - vol sellers get paid, but selling naked front-week is where the pain lives.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied at 11.89% against a 20-day realized print of 8.65 leaves the front-end variance risk premium at 3.24% - a Vrp Active read that pays sellers a real, not cosmetic, spread. This is the harvest window: options are demonstrably rich to the moves the tape has actually delivered over the last month, and the deep book underneath supports monetizing it through defined-risk structures rather than naked short vol.
The nuance sits in the longer lookback. HV60 at 11.49 prints within touching distance of ATM IV, meaning the two-month realized regime is materially hotter than the last four weeks let on. Recent chop has anchored short-dated RV low while the longer window still carries the memory of prior expansion - sell the front, but do not extrapolate the calm.
Conditioning matters. SPY trades in Negative Gamma below the 764.74 flip, so realized can converge to implied on any unpin of the 760.00 pivot. Harvest the premium in size-appropriate condors; keep the defense line explicit.
What it means for your trading
VRP at 3.24% is a paid trade with ATM IV materially above HV20, but HV60 near IV and negative gamma below 764.74 mean short-vol only works with the 760.00 defense honoured.
Skew Convexity
The 20.19% put wing prices materially above the 11.09% call wing against an ATM of 20.29% - quarter-delta skew reads 9.1%, ordered downside protection bid but no left-tail panic. This is hedging demand rolling through the front expiry, not a scramble for convexity.
Smile ratio at 1.82% is elevated without being extreme - the wings are paying up relative to the belly, but the shape stays convex-orderly. Call skew flat against the put steepening tells you the market disbelieves an upside breakout above the 765.00 call wall; nobody is chasing gamma to the topside.
Trade the geometry: put spreads are cheaper hedges than naked puts here - you finance the bid wing by selling further-OTM puts that are still rich to calls. Selling the call wing outright is undercompensated given how flat the topside prints.
What it means for your trading
Steep put skew with a flat call wing at 9.1% quarter-delta says downside is being hedged in an ordered, disbelieving-of-upside tape. Structure hedges as put spreads, not naked puts, and don't reach for call wing premium.
Vol-of-Vol Structure
VVIX prints 90.72 against a VIX of 15.64, leaving the vol-of-vol level Normal in absolute terms - no extreme jump-risk bid has arrived, and the sizing regime stays Standard Size. Nothing in the surface says step down.
The tell is the ratio. VVIX/VIX at 5.80 runs rich to where spot vol alone would justify - the market is paying up for convexity on the convexity, a quiet bid for optionality around binary event risk even as headline VIX drifts. Read it as the tape hedging what could reprice VIX rather than VIX itself, consistent with the Contango curve doing the carrying while the front holds a nervous kink.
Trade implication: keep structure sizing at the derived Standard Size line for the recommended Iron Condor in the 30-45 DTE window, but do not sell the wings for scraps - tail hedges retain fair value here, and the elevated ratio is the reason to keep them on rather than monetize.
What it means for your trading
VVIX absolute level is Normal so sizing holds at Standard Size, but the elevated VVIX/VIX ratio at 5.80 says the market is quietly paying for jump convexity - keep tail wings on rather than harvest them.
Dispersion Spread
Index ATM IV sits at 11.89% against a Vrp Active realized vol backdrop, leaving SPY premium demonstrably rich to what the tape is actually delivering. That gap is the cleanest VRP monetization window on the board - index vol, not single-name, is where the harvest pays.
Dispersion reads Moderate, meaning single-name idiosyncratic risk is only partially absorbed by index protection. Selling single-name strangles into that gap forces you long correlation exactly where correlation is soft - the constituent dispersion eats your premium before the index ever moves.
Preferred expression: iron condor or put spread on SPY in the 30-45 DTE window, sized Standard Size per the Normal vol-of-vol read. Defend the 760 pivot; skip the single-name short-strangle temptation while dispersion carries this label.
What it means for your trading
Index IV at 11.89% with Moderate dispersion means SPY premium sales monetize VRP more cleanly than single-name strangles for the same regime cost.
Liquidity & Microstructure
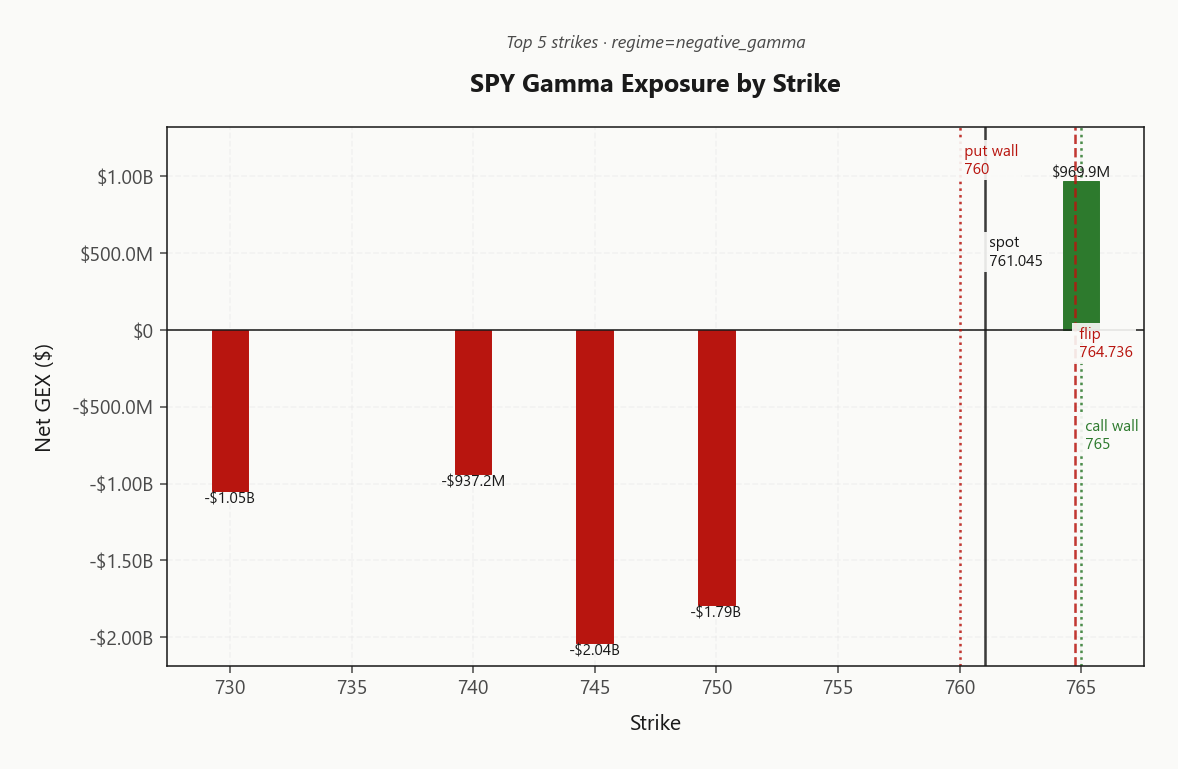
Order-book depth is not the constraint today - the constraint is where the openinterest sits. SPY's highest-OI strike anchors at 525, but the actionable cluster is stacked in downside puts: the top negative-GEX print at 745.00 alone carries -$2.04B of dealer short gamma against 327652 put open interest. Below spot, that concentration is where dealer hedging flow accelerates on any break.
Overhead, the 765.00 call wall is the single supply level capping the chop range, and it sits fractionally above the 764.74 gamma flip. Spot below the flip means dealers sell weakness and buy strength - momentum amplification in both directions, but the asymmetric OI weight is downside. The 760.00 put wall is the pivot the tape defends; hold it and dealer flow stabilizes, lose it and the 745.00 cluster becomes the next magnet.
Execution is clean - depth is there. The trade is respecting the shape of the book, not fighting the liquidity.
What it means for your trading
Book is deep but skewed - downside OI concentration below the 764.74 flip means dealer selling amplifies any break of the 760.00 put wall, while the 765.00 call wall caps the range on the other side.
Trading readNegative-gamma cluster stacked below spot at the 745/750/730 puts and a single positive-gamma block at 765 - this shape says fade rally attempts into 765 and expect amplification on any break below 760.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Charm compounds the setup at -$6.3M. Time decay pushing dealers to sell - pressure into close. Vanna and charm point the same direction, which is the alignment that produces sharp late-session breaks rather than orderly drift. Time itself is now short-delta for the dealer complex into the bell.
The Put Wall at 760 is the pivot. Current bias reads Neutral with spot hugging the level - hold it and dealer hedging stabilizes into pin; lose it and vanna-plus-charm flow flips hostile, with the next liquidity shelf well below. Defend that line or step aside.
What it means for your trading
Vanna at -$110.04B and charm at -$6.3M are aligned negative - a vol spike or the passage of the session both push dealers to sell. The 760 put wall is the binary: above it, pin; below it, cascade.
Scenario EV
The derived scenario engine ranks Iron Condor at the top with a score of 46, tied by the put spread at 46. The optimal window sits in the 30-45 DTE band, where forward vol carry, an active VRP, and normal vol-of-vol at Normal converge on the same structure.
Contango across the VIX curve into 19.73 and 21.03 funds the carry, while VVIX at 90.72 keeps sizing Standard Size. The put spread tie is the tell - a defensive tilt is on the table if the tape breaks the 760 put wall and the regime degrades from Elevated / Watchful.
Structure defense line is the put wall itself: hold it, iron condor harvests through the 15-session regime half-life; lose it, roll into the put spread and cut the call wing.
What it means for your trading
Iron condor 30-45 DTE on SPY is the structural fit - put spread scores match at 46, meaning the defensive pivot is pre-loaded around the 760 put wall.
Actionable Summary
Bottom line: the derived scenario engine prints Iron Condor at 30-45 DTE on SPY as the structural fit for an Elevated / Watchful tape. VRP is active, VIX term structure holds contango, and VVIX at 90.72 keeps sizing standard per Standard Size - collect premium, don't over-lever.
Defense line is the 760 put wall, currently acting as the charm pivot with spot at 761.05. Net vanna at -$110.04B and net charm at -$6.3M mean a break flips dealer flow hostile into the close - cut, don't average. Above, the 765.00 call wall caps the range.
Cross-asset: QQQ regime diverges from SPY/IWM (True) - tech is the stabilizer, small caps the fragile leg. Hedge asymmetry via IWM put spreads if the Russell breaks. Avoid single-name short strangles during moderate dispersion; index VRP monetizes cleaner.
What it means for your trading
Sell Iron Condor at 30-45 DTE on SPY, standard size, and defend the 760 put wall as a hard line. Rotate to IWM put spreads if regime divergence resolves lower through the small-cap complex first.
Fed's first hike in 3 years is the anchor macro event - everything today reads through this lens including the negative-gamma regime we're in
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.67 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 764.74 against a spot of 761.05. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.89% with a volatility risk premium of 3.24%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.64. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime