Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 762.53 sits in a soft-gamma pocket - net GEX -$2.39B with gamma flip unpublished (Weak Shoulders), so dealer response is not smoothing tape. Key levels: call wall 765.00, put wall 760.00, max pain 754.00 - spot is caught between the walls with no clear magnet. Dealers are net short delta into vol spikes (vanna -$118.97B) and short charm -$9.5M, so time decay pressures the tape lower into the close. VIX at 15.62 with term structure in Contango at 11.87% slope means carry favors vol sellers, and VRP is 1.58% points paid over 20d realized. Bottom line: sell premium in 21-30 DTE 21-30, prefer QQQ short vol where dealers are long gamma, and treat any breach below 760.00 as regime-change confirmation.
SPY sits at 762.53 pinned between put wall 760.00 and call wall 765.00 with net GEX negative and gamma flip unpublished. QQQ diverges cleanly - dealers long gamma above flip 716.46 while IWM lags with negative GEX beneath its call wall. Term structure in Contango and VVIX at 88.43 argue for measured short-vol carry, but negative index vanna keeps downside amplification live if VIX pops.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
762.53
-
-
765
760
754
-$2.39B
-
QQQ
716.82
716.46
+0.05%
720
700
705
$3.46B
Long gamma
IWM
287.10
295.06
-2.70%
290
285
290
-$6.42B
-
VIX
15.62
-
-
20
15
20
-$20.10M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
11.16
9.58
+1.58
9.26
2.51
0.98
QQQ
14.81
13.28
+1.53
2.49
1.44
1.28
IWM
15.15
13.07
+2.08
2.73
2.54
1.88
VIX
75.69
99.45
-23.76
-126.42
0.30
0.41
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
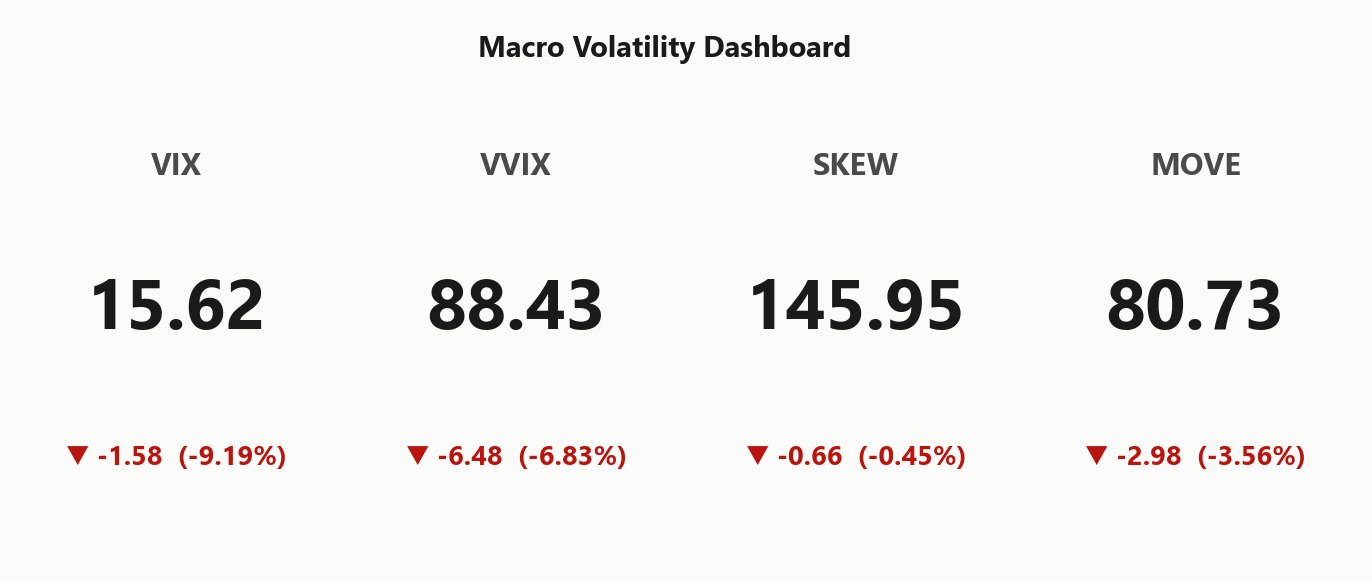
15.62
-9.19%
VVIX
88.43
-6.83%
SPX
7,636.94
+1.13%
SKEW index
145.95
-0.45%
MOVE (bond vol)
80.73
-3.56%
VIX term (9d/30d/3m/6m)
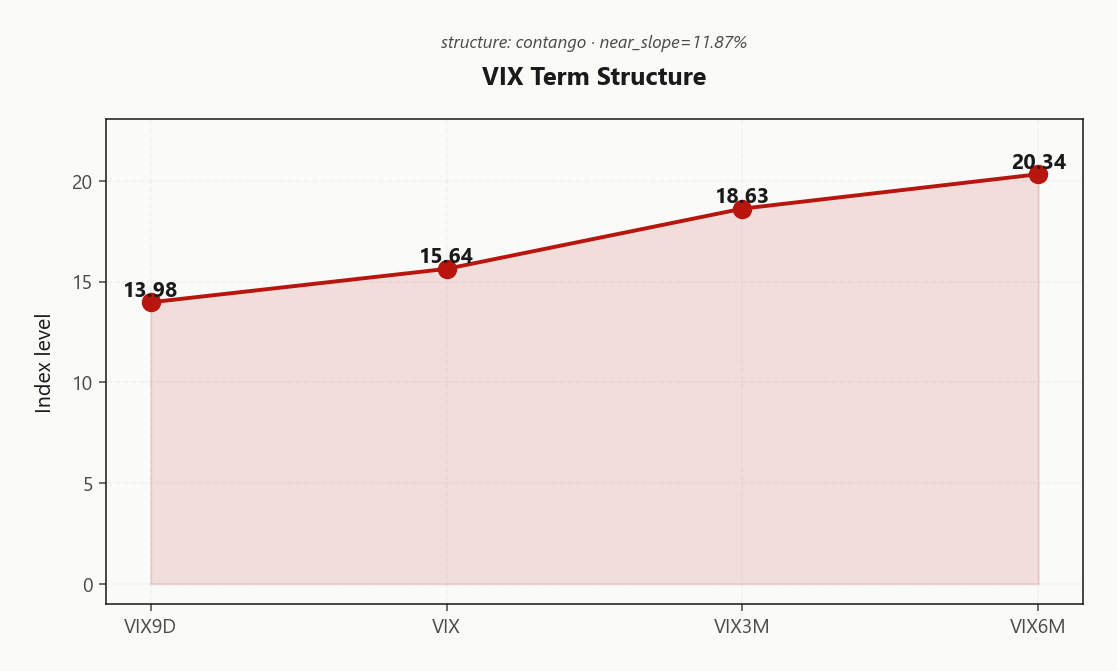
13.98 / 15.64 / 18.63 / 20.34
Steep contango
VVIX / VIX
5.66
Low
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX printing 15.62 - the middle band where dealer flow is unsupportive but tail pricing is quiet. Panic-transition odds sit at 0.05 over five sessions while drift to the low-vol regime runs 0.45 over ten - the base rate favors decay, not escalation.
Half-life is 15 sessions, which is sticky by construction. Rotating short-vol books early forfeits the carry the regime is built to pay; the correct posture is to hold structures into 21-30 DTE and let time do the work. Forward vol reads Steep contango - vol sellers favored and VVIX regime is Low, both aligned with the elevated-but-not-panicked call.
Trigger for reassessment: 760.00 breach flips the state map - until then, treat this as a paid-to-wait tape.
What it means for your trading
Elevated but not stressed - 15-session half-life means the carry regime persists longer than most traders' patience, and a 0.05 five-day panic probability is not the tail worth trading around. Hold short-vol structures; rotate only on a 760.00 breach.
Trading readVIX at 15.62, VVIX 88.43, SKEW 145.95, MOVE 80.73 - all four confirming compression. No divergence flag today; regime is coherent.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure stacks clean: 13.98 at the front, 15.64 at 30D, 18.63 at 3M, 20.34 at 6M - Contango end-to-end with no event bump priced anywhere on the curve. Regime reads Steep Contango, signal Green. Near slope prints 11.87%%, which is the roll-yield vol sellers pocket for holding through decay.
Optimal DTE window for premium sales is 21-30 - that's where forward vol embeds the richest carry without eating the wing on gamma. Longer tenors give up too much convexity to the 20.34 anchor; shorter tenors don't harvest enough slope.
Trading read9D-VIX-3M-6M all in contango with front slope 11.87%% - the vol carry trade is fully live. Backwardation would flip the regime; not there.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV prints 11.16% against 20-day realized at 9.58, leaving 1.58% points of carry paid to premium sellers. The regime reads Vrp Active - options are decisively rich to the tape's actual footprint, and the VRP pocket is wide enough to absorb ordinary intraday chop without eroding edge.
The realized term itself is de-escalating: HV60 at 11.28 sits above HV20 9.58, so the fair-vol ceiling is rolling lower as the older, hotter tape drops out of the window. That geometry favors selling front-month vol against a back-month HV anchor that keeps compressing, not expanding - the direction of realized is the tailwind, not the headwind.
Cross-sectionally, IWM VRP 2.08% pays richer than SPY 1.58% and QQQ 1.53%. Small-caps carry the fattest premium and cleanest short-vol setup; QQQ's positive-gamma backdrop makes it the safer venue for defined-risk structures, while SPY's negative-gamma pocket demands wings, not naked shorts.
What it means for your trading
VRP paid at 1.58% points with HV60 11.28 above HV20 9.58 = premium sellers compensated into de-escalating realized. Rotate the carry to IWM 2.08% for richest edge, QQQ for cleanest gamma-safe execution.
Skew Convexity
The 18.92% put-wing print against 19.31% ATM and a call wing at 9.66% tells the whole story: downside is bid, upside is orphaned. Skew of 9.26% vol points with a smile ratio of 1.96% is ordered protection demand, not scramble - the wing is being accumulated methodically, not chased.
The flat-to-inverted call side is the tell. There is no upside speculation bid financing the surface, which means covered-call overwriters and call-spread sellers face a thin market. QQQ smile ratio at 1.15% runs cleaner than SPY - tech is materially less hedged, consistent with dealers long gamma above 716.46.
Trade the geometry directly: put spreads over naked puts - the wing is too rich to buy outright, and selling the deeper strike recycles the skew premium into the structure. Call spreads finance the put wing at negligible give-up given the flat upside. Avoid naked short puts below 760.00; the ordered bid becomes disordered fast if that level breaks.
What it means for your trading
Skew at 9.26% with smile ratio 1.96% reads as steep-but-controlled - sell the wing via spreads, do not buy it naked. Call side flat means the cheapest financing on the board is right there for structured put protection.
Vol-of-Vol Structure
VVIX at 88.43 against VIX 15.62 prints a ratio of 5.66 - squarely in the Low zone. The vol-of-vol tape is not pricing a bimodal jump; convexity buyers are absent and the wings are not scrambling for gamma-of-gamma cover.
Today's VVIX print eased -6.83%, confirming the retreat after yesterday's Fed-driven spasm. When VVIX collapses into a contango term structure with VRP paid, the carry trade widens - dealers are not paying up for tail insurance on the insurance itself, which is the cleanest green light the vol complex offers for premium sellers.
Sizing guidance resolves to Standard Size. No haircut for jump risk, no leverage bonus for compressed vol-of-vol - run books at book weight. The asymmetry only re-emerges if VVIX punches back through its recent shelf; until then, treat the setup as a standard-carry regime, not a jump-hedged one.
What it means for your trading
VVIX at Low with a ratio of 5.66 means the market is not paying for bimodal outcomes - short-vol structures earn full carry at Standard Size.
Dispersion Spread
Index ATM IV sits at 11.16% with CBOE SKEW still bid at 145.95 - tail hedging demand persists even as spot vol compresses. Cross-strike dispersion reads Moderate: index wings are paying, but the body of the surface is not. That gap is where the trade lives.
Single-name IV continues to trade rich to the index basket - the mag-7 movers (META, AAPL, NVDA) are absorbing hedging flow that never fully aggregates into SPX vol. Sell index premium, own name-level convexity. IWM ATM IV at 15.15% versus SPY 11.16% is the cleanest size gap on the tape - small-cap idio is where the fatter carry sits.
Preferred structure: short SPY straddles or iron condors financed against long single-name gamma in the QQQ complex where regime holds Positive Gamma. Skew stays elevated so wing sellers get paid, but do not naked the put - spread it.
What it means for your trading
Elevated SKEW at 145.95 against compressed ATM 11.16% is the dispersion tell: sell index vol, own single-name convexity, and let the IWM/SPY IV gap fund the wing.
Liquidity & Microstructure
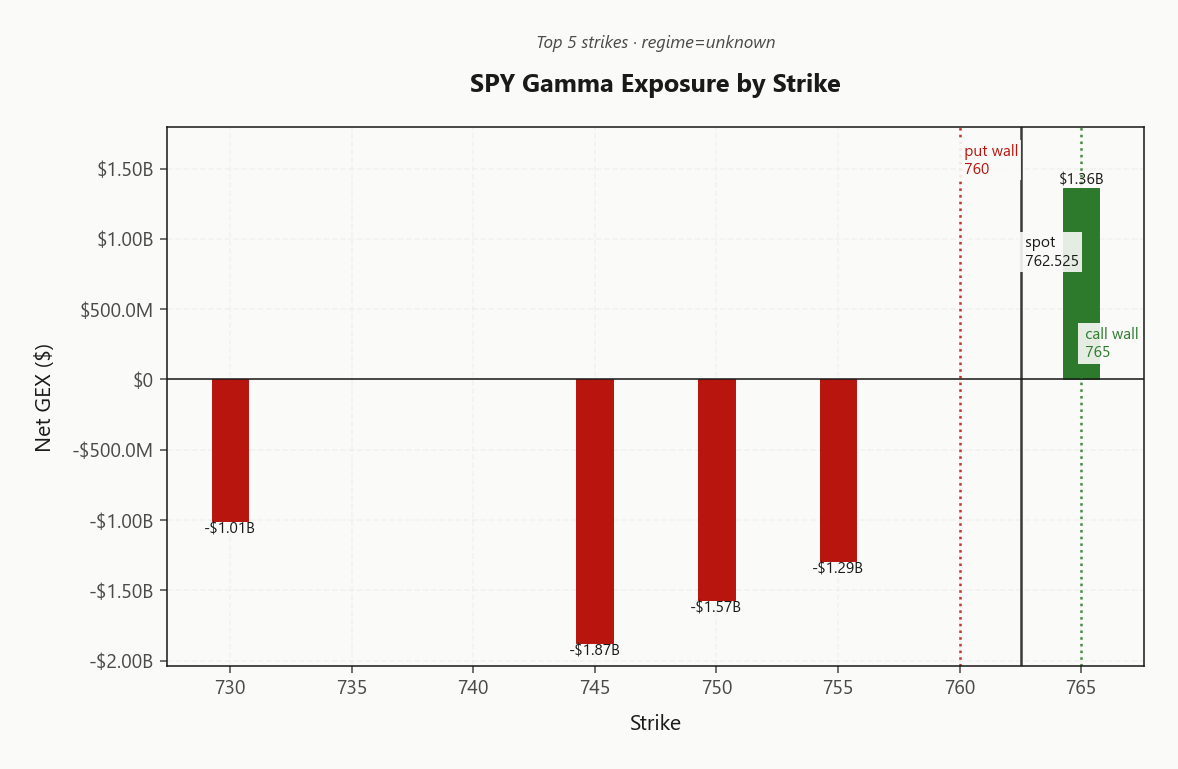
The book anchors at 525 - a deep out-of-money put wall echo that speaks to structural protection rather than fresh directional conviction. The top strike sits at 745.00 carrying -$1.87B of net gamma, and that single-strike concentration reads as heavy put dominance in dealer inventory, not upside speculation.
Above 765.00 the tape hits a ceiling - dealers sell into strength; below 760.00 the trapdoor opens as dealers sell into weakness. The gamma flip itself is Weak Shoulders, leaving the pivot the tape normally leans on unresolved and unreliable. Trade the walls, not the middle.
Zero-DTE carries -101.3% of the chain in the 2026-09-17 expiration - intraday flow is same-day paper. Expect sharp reversion at strike clusters and minimal trend persistence into the close.
What it means for your trading
The book is deep but pivotless - with the gamma flip Weak Shoulders, the 765.00 call wall and 760.00 put wall are the only structural anchors worth trading against. A sustained breach of 760.00 is the regime-change tell.
Trading readSPY dealer flow is negative between 760.00 and 765.00 - dealers amplify moves in either direction inside the range. Only above 765.00 does gamma flip to dampening. Trade the walls, not the middle.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Vanna is the accelerant. Net VEX prints -$118.97B, meaning dealers are structurally short delta into any vol expansion - a VIX pop from 15.62 forces mechanical selling on top of directional weakness. Charm pulls the same direction: net CHEX at -$9.5M bleeds delta out of dealer books as time passes, biasing hedging flow lower into the close.
The pivot sits at 765 - a Call Wall - with spot 0.324579522% below. Current bias reads Neutral, but that label is fragile: a reclaim of the pivot flips dealer flow from selling-into-strength to buying-into-strength, while a rejection compounds the charm drag already priced.
Cross-asset the greeks diverge cleanly. QQQ vanna at -$56.55B against SPY's -$118.97B is the trade: tech dealers dampen, index dealers amplify. Sell QQQ premium where the vanna sign works with you; avoid naked SPY short strangles where it works against you.
What it means for your trading
Vanna and charm are aligned short into the close - the pivot at 765 is the level that flips dealer flow. Until it reclaims, treat rallies as fadeable and downside as un-cushioned.
Cross-Asset Confirmation
MOVE at 80.73 tells the story cleanest - rates vol has gone quiet, printing -3.56% on the session. No credit spillover, no funding stress, no macro tape bomb waiting to detonate. This is an equity-structure adjustment in isolation, and cross-asset confirms it: Fear & Greed reads Fear at 30 - contrarian fuel sitting under the tape, not capitulation.
The index split is the tell. QQQ at 716.82 holds Positive Gamma above its flip while IWM at 287.10 sits beneath its own - SPY/QQQ regime diverged flags True. Tech carries the gamma cushion; small-caps carry the fragility. That is a rotation posture, not a systemic one.
Watch IWM. If it accelerates below 295.06, small-cap fragility broadens into a risk-off tell and the isolated read no longer holds.
What it means for your trading
Cross-asset says isolated equity re-hedge, not macro shock - MOVE dead, F&G at Fear, QQQ above flip while IWM below. Trade the divergence long QQQ vol-short over SPY; treat sustained IWM weakness beneath 295.06 as the confirmation that the regime broke.
Scenario EV
The recommended-structure resolver returned Unknown at signal Red, so treat the headline call as unresolved and lean on the underlying regime facts. VRP is 1.58% paid on SPY with term structure in Contango and VVIX at Low - the carry pocket is live, but SPY's gamma flip is Weak Shoulders and net GEX prints -$2.39B, so naked short vol on the index is the wrong expression.
Route the risk to QQQ, where dealers sit Positive Gamma above flip at 716.46 and hedging dampens moves - a 21-30 DTE iron condor collects the richest carry with a friendly gamma backdrop. IWM earns the put-spread book: VRP prints 2.08%, the fattest of the three, and defined-risk downside respects the sub-flip fragility.
Avoid SPY short strangles until the flip resolves; the vanna print of -$118.97B means a VIX pop accelerates the tape lower before premium decays. Size Standard Size - VVIX is not warning of a jump.
What it means for your trading
Resolver is Unknown, but the regime says sell premium in 21-30 DTE via QQQ iron condors and IWM put spreads - not SPY strangles while the flip is Weak Shoulders.
Actionable Summary
Trade: sell premium in 21-30 DTE iron condors on QQQ, where dealers hold Positive Gamma above flip 716.46 and dampen the tape. Fund the wings at quarter-delta; IWM offers the richest carry at 2.08% VRP if you want a second book.
Avoid: naked SPY short strangles. Gamma flip is Weak Shoulders, net VEX -$118.97B is hostile into vol spikes, and spot sits between put wall 760.00 and call wall 765.00 with no magnet. Watch the charm pivot at 765 (Call Wall) - dealer flow direction flips through it. A close beneath 760.00 is regime-change confirmation; IWM sustained below 295.06 broadens the downside read.
Sell 21-30 DTE vol on QQQ where dealers are long gamma, avoid naked SPY strangles with the flip unresolved, and treat a breach of 760.00 or IWM losing 295.06 as the regime-change trigger.
Bounce-back rally after Fed sell-off matters because it tests whether the negative-gamma pocket in SPY resolves through walls or through structural vol re-pricing.
Bank of England defying the Fed on rates creates cross-currency vol spillover risk and is the kind of policy divergence that has historically preceded MOVE index spikes.
First Fed hike in three years is the anchor event behind today's session - it reframes the entire term-structure carry trade and validates why VRP is bid.
China pressing Iran to rein in Houthis is a de-escalation signal that would compress the geopolitical risk premium currently sitting in oil-linked equities and MOVE.
Boeing 737 Max production delays are the kind of single-name industrial signal that keeps IWM fragile even when SPY holds - supports the small-cap divergence read.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.62 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
Is SPY in positive or negative gamma today?
SPY is in Unknown gamma with net dealer GEX at -$2.39B. The gamma flip sits at N/A, with the call wall at 765.00 and the put wall at 760.00.
Where is the SPY gamma flip level right now?
SPY's gamma flip is at N/A against a spot of 762.53. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 11.16% with a volatility risk premium of 1.58%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.62. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime