Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 762.37 sits just under the 765.41 gamma flip with net GEX at -$4.82B - dealers short gamma, moves amplified until spot reclaims the flip. Call wall 765.00, put wall 760.00, max pain 753.00; the 760 put wall is the pivot - -0.3108726734% away, Neutral bias. Dealer vanna at -$117.34B is deeply negative - a vol spike accelerates selling; charm at -$4.8M adds gentle sell-side pressure into the close. VIX 15.46 down -10.12%%, term structure Contango with 13.84%% near-slope; VVIX 87.98 confirms benign vol-of-vol. VRP at 1.23% favors sellers but the Iron Condor at 30-45 DTE is the fit, not naked shorts. Bottom line: sell premium into strength toward the call wall, hedge the 760.00 break with cheap wing convexity.
SPY at 762.37 sits fractionally below the 765.41 flip in negative-gamma territory, but VIX at 15.46 with steep contango Steep contango - vol sellers favored keeps vol sellers in the driver's seat. IWM confirms fragility with matching negative gamma while QQQ regime is undetermined - the divergence is the tell. Steep short-dated skew (1.94%x smile ratio) says downside protection remains bid even as headline vol compresses.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
762.37
765.41
-0.40%
765
760
753
-$4.82B
Short gamma
QQQ
716.38
-
-
720
700
705
$968.11M
-
IWM
285.23
293.76
-2.90%
290
285
290
-$7.21B
Short gamma
VIX
15.44
15.34
+0.66%
20
15
20
$13.36M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.90
9.67
+1.23
8.89
2.49
0.98
QQQ
14.74
13.31
+1.43
1.59
1.44
1.35
IWM
15.16
12.55
+2.61
2.54
2.53
2.33
VIX
79.61
101.37
-21.76
-129.29
0.30
0.48
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
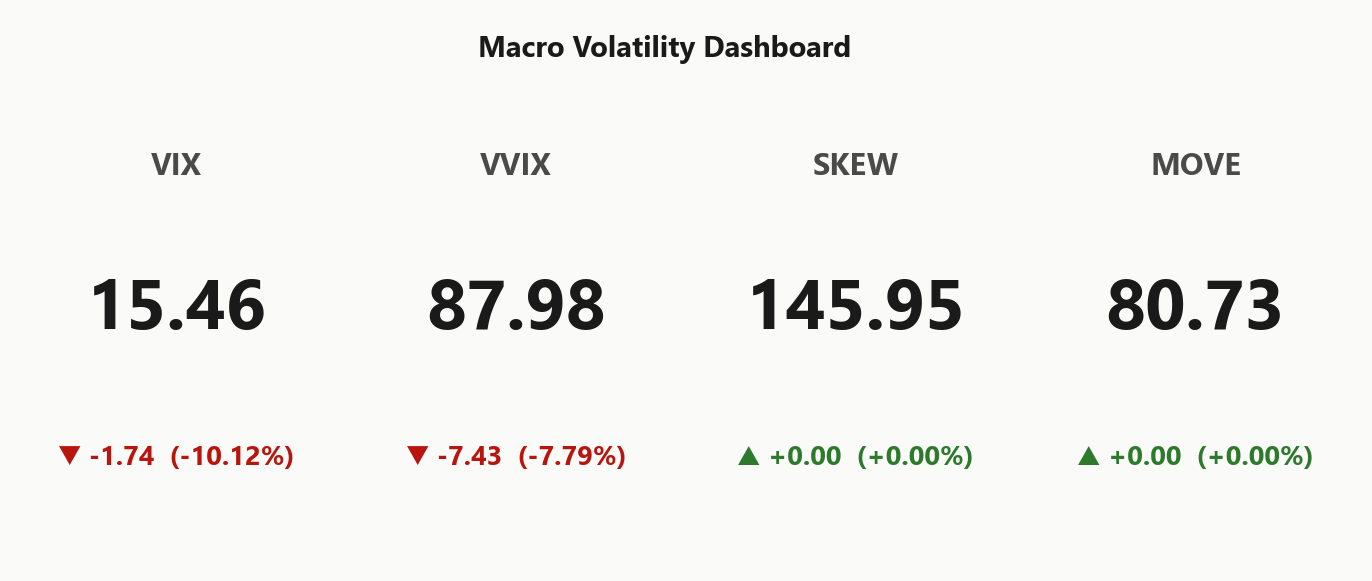
15.46
-10.12%
VVIX
87.98
-7.79%
SPX
7,637.76
+1.14%
SKEW index
145.95
0.00%
MOVE (bond vol)
80.73
0.00%
VIX term (9d/30d/3m/6m)
13.58 / 15.46 / 18.50 / 20.26
Steep contango
VVIX / VIX
5.69
Low
Regime
Elevated / Watchful
Regime Assessment
Current regime prints Elevated / Watchful with VIX anchored at 15.46 - watchful, not panicked. The transition probability toward panic over the next five sessions sits at 0.05, a low bar that keeps vol-selling posture defensible while dealers remain short gamma below the flip.
Decay probability toward the low-vol regime within ten sessions runs 0.45 - a meaningful drift path if forward-vol contango holds and VVIX stays benign. Half-life of the current state is 15 sessions, which reframes this as sticky rather than transitional; positions need to survive multi-week persistence, not a one-print reversion.
Practically: size premium sales for staying-power, not for a quick regime flip. The elevated label caps aggression, the low panic-transition probability licenses standard sizing, and the 15-session half-life argues for structures that carry through 30-45 DTE without needing an early exit.
What it means for your trading
Regime is Elevated / Watchful and sticky at a 15-session half-life - plan for multi-week persistence with vol-selling posture, not for a fast round-trip to low-vol.
Trading readVIX and VVIX both dropped hard, SKEW held bid, MOVE subdued - the vol complex isn't confirming panic anywhere. Divergence to watch: SKEW staying elevated as VIX falls means tail hedgers didn't unwind.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
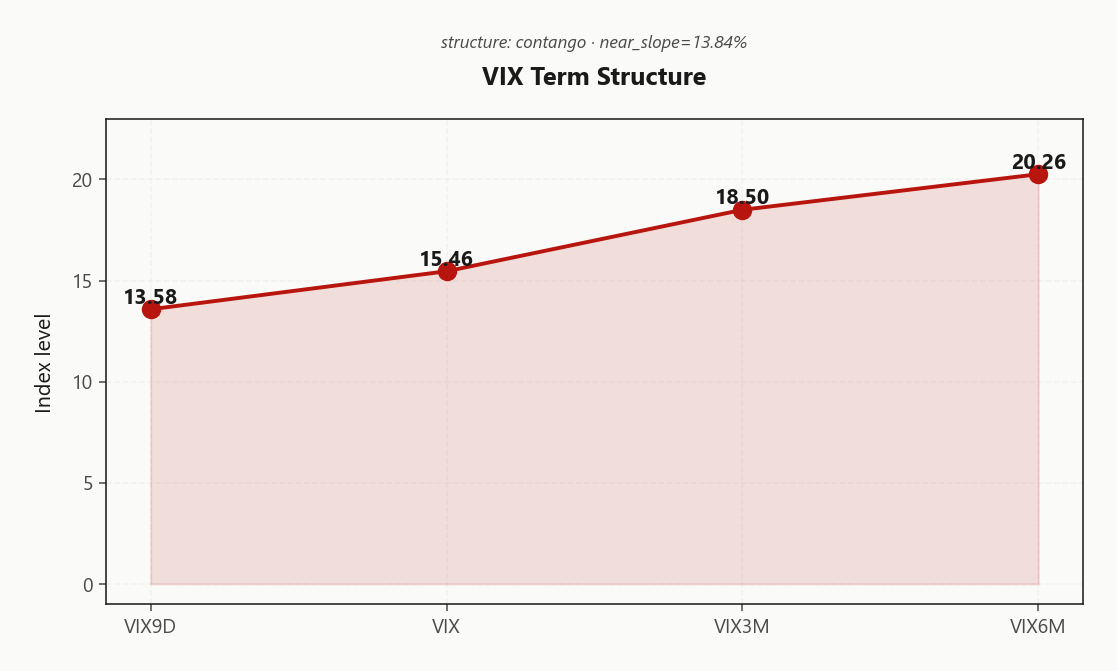
The VIX complex is textbook Contango - VIX9D at 13.58 trades below spot VIX at 15.46, which itself sits well beneath VIX3M at 18.50 and VIX6M at 20.26. Near-slope of 13.84%% confirms the regime as Steep contango - vol sellers favored - a green light for vol carry, but the shape of the curve is the tell, not the level.
The bend between the front and the belly is what matters: near-term VIX pricing calm while VIX3M/VIX6M lift shows the market quietly building 3-6 month event premium. Forward 30-60 implied at 19.8461381634 and forward 60-90 at 21.8788756567 both sit meaningfully above spot - the back end is not cheap, it is compensating for something.
The trade is short-dated premium harvesting, not multi-month shorts. Calendar rolls that sell the front-week collapse and own the back-month event premium capture the curve's shape without renting duration risk into a bid that may prove correct.
What it means for your trading
Steep contango with front below spot and back-end bid means vol sellers get paid up front while the market quietly pays for multi-month tails - sell the front, don't short the back.
Trading readSteep contango with near-slope 13.84%% is a green light for vol carry - front-month sellers get paid, but the 20.26 back-end says multi-month event risk is being quietly priced.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Realized is running well under implied and the carry is real. HV20 at 9.67 sits below ATM IV 10.9%, and HV60 at 11.3 above HV20 says realized has been decelerating into this print - the tape has quieted while options continue to price the memory of prior weeks.
The VRP at 1.23% is positive and material, which pays sellers directly. Short-dated ATM IV remains elevated versus what SPY has actually delivered, meaning the front-week premium is compensating for a weekend that, on realized evidence, may not arrive.
Read this as IV over-reaching, not under-pricing. The edge is harvesting the spread - but with SPY sub-flip and skew steep, size sales as defined-risk structures, not naked shorts.
What it means for your trading
Realized decelerating from 11.3 to 9.67 while ATM IV holds 10.9% makes VRP 1.23% a live carry - collect it through spreads while the negative-gamma regime keeps naked shorts off the table.
Skew Convexity
Front-week smile ratio sits at 1.94%x with quarter-delta put IV at 18.32% versus ATM 8.38% - a panic-style downside bid that refuses to unwind even as headline vol collapses. The tail is not cheap here; hedgers are still paying up for protection while the tape drifts.
Call-side quarter-delta IV prints 9.43%, effectively flat to ATM - zero upside conviction being expressed through options. The smile is one-sided: buyers of downside, no chasers of upside. Skew index at 145.95 and 25-delta differential of 8.89% vol points confirm the tail bid is structural, not a stale print.
With smile ratio above the steep threshold and the underlying below the 765.41 flip, naked put selling gives away the wing convexity the market is actively repricing. Spread the puts - sell the meat, own the tail - and let call skew's flatness fund the structure through defined-risk condors rather than open-ended shorts.
What it means for your trading
Skew is steep and one-sided: downside paying 1.94%x the ATM vol while upside sits flat, with SKEW at 145.95 confirming the tail bid. Sell premium as spreads - the wings are too rich to give away naked.
Vol-of-Vol Structure
VVIX prints 87.98 against VIX 15.46, a ratio of 5.69 that classifies as Low - jump risk is not signaling, and the vol-of-vol complex is offering no binary regime warning. VVIX fell -7.79% on the session, confirming the compression is dynamic, not stale.
A ratio in this zone is the classic vol-selling green light - the second derivative of vol is not paying up for convexity, so the tail bid is contained even with steep front-week skew elsewhere in the book. Sizing guidance reads Standard Size, not defensive - no VVIX-driven halving needed, no gap-risk premium to build into strike selection.
Paired with the Steep contango - vol sellers favored forward-vol regime, this is the setup where premium sellers run full clip rather than skeleton size. The vol-of-vol channel is quiet enough that structured shorts can be built at policy weight instead of stress weight.
What it means for your trading
VVIX at 87.98 and a ratio of 5.69 put jump risk firmly in the Low bucket - size premium sales at Standard Size, not half-clip.
Dispersion Spread
Index vol has been beaten flat - SPY ATM IV sits at 10.9% with QQQ at 14.74% and IWM at 15.16%, a compressed complex that leaves headline premium looking cheap versus the single-name tape underneath it. The mover leaderboard tells the other half of the story: META printed a Positive gamma shift at the top of the board, with AAPL, MSFT, and NVDA stacked right behind - persistent dealer positioning churn in mega-cap while index-level vol grinds lower.
Correlation is sitting moderate, not high - which is precisely the regime where index protection under-prices single-name tail. Buy the index and you get diversification-diluted vega; own the underlyings and you carry idiosyncratic gamma that isn't being subsidized by the basket bid. Dispersion is live even if the screen doesn't shout it.
The trade shape follows: sell index premium where VRP and compressed ATM IV pay you, and hedge idiosyncratic risk with single-name spreads on the top movers rather than assuming the index wrapper covers it. Naked single-name shorts don't get compensated for the correlation gap.
What it means for your trading
Compressed index IV around 10.9% alongside a live single-name gamma leaderboard led by META flags a moderate-correlation regime where dispersion is real. Harvest premium at the index level; carry idiosyncratic tail with defined-risk single-name structures, not naked shorts.
Liquidity & Microstructure
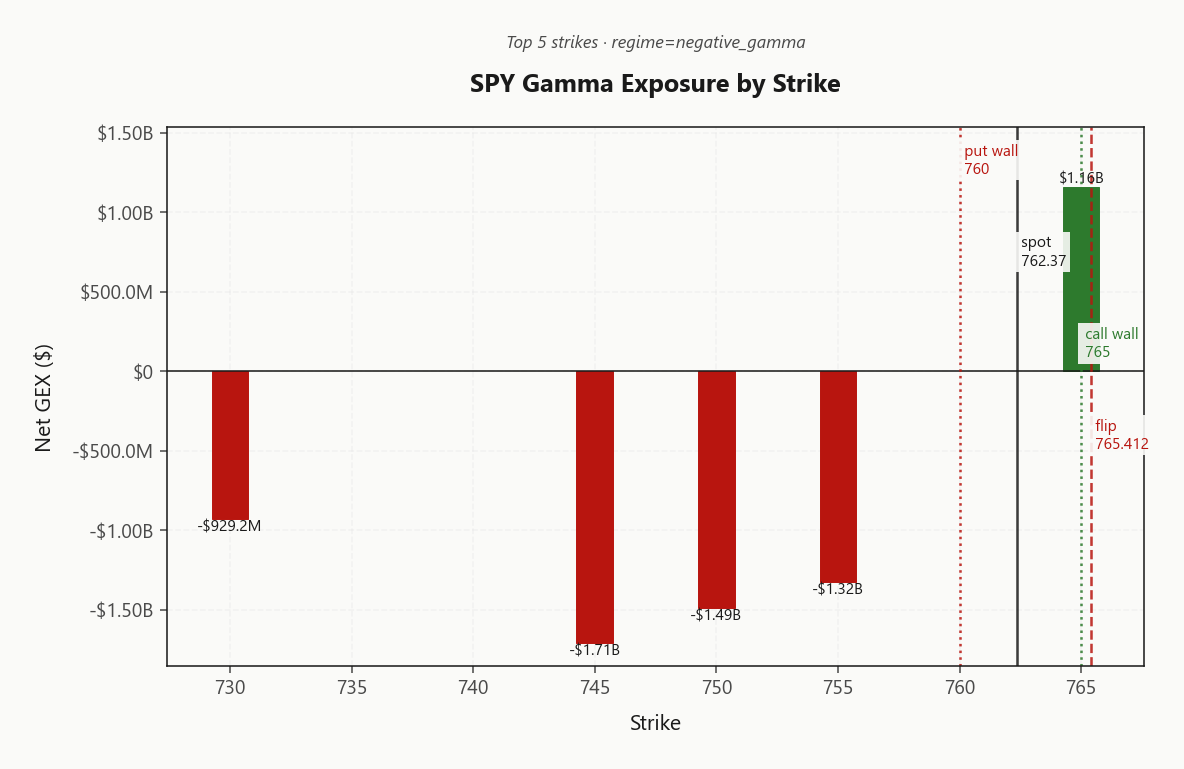
The book's center of gravity sits at 745.00, where -$1.71B of negative gamma against 381336 of open interest anchors the amplification zone directly beneath spot. This is the strike doing the work - every tick lower forces dealers to sell more, every tick higher forces them to cover. The legacy 525 OI cluster is a museum piece at this range, irrelevant to today's flow.
The 765.41 flip is the single level that matters. Above it, dealer hedging supports rallies and dampens moves; below it, dealer selling accelerates weakness into a reflexive loop. Spot trades under the flip now - the tape's character is amplify-down, mean-revert-up only on reclaim.
The 765.00 call wall caps upside as a magnet-then-resistance, while the 760.00 put wall is the operative pivot for downside - the charm anchor and the level where dealer flow character flips. Structure trades around these two rails; the flip decides which one is in play.
What it means for your trading
The 745.00 negative-gamma cluster under spot is the amplification engine, and the 765.41 flip is the binary switch between mean-revert and trend-follow regimes. Trade the 765.00 / 760.00 rails and treat any break of the put wall as a regime-change signal, not noise.
Trading readDeep negative gamma clustered right under spot at the 745.00 strike says any weakness gets amplified - dealer selling accelerates below the flip; above it, the 765.00 call wall becomes the magnet.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna prints -$117.34B - deeply negative and the dominant second-order risk on the book. Every uptick in implied vol pushes dealer delta more negative, meaning a VIX spike doesn't just widen ranges, it forces mechanical selling on top of it. This is the accelerant that turns an orderly pullback into a gap.
Charm sits at -$4.8M - modestly negative, a slow bleed of long delta into expiry that adds gentle sell-side pressure through the close rather than a violent flow. On its own charm is noise; layered over negative vanna and sub-flip gamma it compounds the downside-skewed reaction function.
The pivot is the 760Put Wall, sitting -0.3108726734 from spot with bias currently Neutral. Hold that level and vanna/charm stay dormant background flows; breach it and the same exposures flip from latent to kinetic, with dealers hedging the vol spike and the delta bleed in the same direction.
What it means for your trading
Vanna at -$117.34B is a downside accelerant, not a directional call - the 760Put Wall is the line where Neutral bias flips negative and dealer hedging turns reflexive.
Cross-Asset Confirmation
The cross-asset tape refuses to confirm equity fragility. MOVE at 80.73 keeps rates vol pinned, credit spreads have not blinked, and Fear & Greed prints 29 (Fear) - a contrarian floor-building signature, not a risk-off cascade. This is equity microstructure fragility in isolation, not a macro shock leaking into stocks.
The tell is the index split. SPY sits sub-flip in negative gamma while QQQ at 716.38 reads True on the SPY/QQQ regime divergence check - mega-cap tech gamma from META, AAPL, MSFT, and NVDA is masking the underlying dealer short-gamma posture that IWM at 285.23 confirms cleanly. Small caps mirror SPY's fragility; tech is the anaesthetic.
Trade the divergence: sell index premium where cross-asset calm subsidizes the carry, and treat any QQQ reclaim of its flip as the confirmation that the mega-cap gamma bid is real rather than a positioning artifact.
What it means for your trading
Cross-asset stays orderly with MOVE subdued and Fear & Greed at Fear - the fragility is equity-microstructure only, not systemic. QQQ regime undetermined vs SPY/IWM negative gamma is the divergence to fade, not chase.
Scenario EV
The scorecard lands on Iron Condor at 30-45 DTE as the highest-EV structure, best score 31 against short put spread's 30 - a razor-thin lead that reflects a two-sided setup, not a directional one. Steep contango (Steep contango - vol sellers favored) pays the front-month seller, VRP at 1.23% is live, and vol-of-vol at Low keeps sizing guidance at Standard Size - no VVIX-driven half-size defense needed.
The 30-45 DTE window threads the term-structure sweet spot: long enough to harvest the 13.84%% near-slope decay, short enough to sidestep the multi-month event premium building into the 20.26 back end. Wing the condor around the 765.00 call wall and 760.00 put wall; if a directional bias emerges as SPY reclaims 765.41, roll into the short put spread as the runner-up.
Avoid naked short strangles while SPY trades below the flip - the -$117.34B vanna profile turns a vol spike into a delta accelerant. Defined risk only.
What it means for your trading
Iron condor at 30-45 DTE is the trade, put spread at score 30 is the pivot if regime constructively resolves above 765.41. Standard size - the signal is Yellow, not green, so lean disciplined not aggressive.
Actionable Summary
Bottom line: preferred structure is an Iron Condor around SPY 765.00 / 760.00 at 30-45 DTE, sized standard while the regime reads Elevated / Watchful. Use the 760 put wall as the pivot for adjustments - that's the charm flip where dealer flow inverts.
Watch the 765.41 flip: reclaim shifts SPY back to positive gamma and takes the amplification out of the tape. Avoid naked short strangles below the flip and short-dated call sales into the 765.00 wall - the vanna profile at -$117.34B punishes anything undefined. Hedge with cheap OTM put wings; front-week skew at 1.94%x smile ratio is still paying for downside convexity.
Escalate size only if VIX presses back toward 13.58 and the flip is reclaimed on volume. Until then, sell premium into strength, defend the 760.00 break, and let the 15-session regime half-life work.
What it means for your trading
Sell the wings, not the middle: iron condor around 765.00/760.00 at 30-45 DTE with the 760 pivot as the adjustment trigger. Reclaim of 765.41 is the green light to lean size.
Portfolio color from CNBC's Investing Club - chip and pharma leadership captures the day's rotation into cyclical semis and defensive healthcare, useful color on where post-Fed money went.
The 'top 10 things to watch' framing signals institutional focus on a Fed-driven bounce - dealer positioning suggests the bounce is being sold into the call wall, not chased.
Bank of England defying the Fed's rate path matters for cross-asset volatility - a rates-vol divergence keeps MOVE subdued but is a slow-burn setup for FX-linked equity moves.
Trump's 'towards end' of Iran war comment is the geopolitical vol suppressant of the day - helps explain the VIX collapse and why front-week skew stayed bid as tail hedgers unwound.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.44 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Unknown across SPY, QQQ, and IWM.
SPY's gamma flip is at 765.41 against a spot of 762.37. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.9% with a volatility risk premium of 1.23%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.46. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime