Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 758.82 with net GEX at -$10.67B - dealers are short gamma, so intraday moves get amplified rather than dampened. Call wall sits at 760.00, put wall at 750.00, gamma flip up at 764.56 - spot below flip means selling accelerates on breaks and rallies get faded until we reclaim it. Dealer vanna at -$85.39B and charm at -$4.9M both lean hostile: a vol pop forces dealers to sell delta, and time decay pushes selling into the close. VIX at 16.95 sits inside a contango curve (Contango, -2.73% near slope) with VVIX at 94.37 - carry is intact, vol-of-vol is Normal, VRP stays 5.02%. Fear and Greed reads Fear at 28, so sentiment is on the defensive even as futures grind. Bottom line: fade rallies into 760.00, respect 750.00 as the line that opens the trapdoor, and structure premium sales as iron condors in the 30-45 DTE bucket rather than naked wings.
Negative gamma across index complex with contango vol curve and Elevated / Watchful regime
SPY at 758.82 trades below the 764.56 gamma flip, keeping dealers short gamma and moves amplified. VIX term structure remains in contango with Normal vol-of-vol, so vol sellers still get paid but the 3.9% put skew warns the tail isn't cheap. Iron condors in the 30-45 DTE window score best against a Elevated / Watchful regime.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
758.82
764.56
-0.75%
760
750
755
-$10.67B
Short gamma
QQQ
708.44
714.61
-0.86%
710
700
705
-$3.68B
Short gamma
IWM
286.50
294.24
-2.63%
290
285
290
-$5.67B
Short gamma
VIX
16.95
18.22
-6.98%
20
16
19
-$26.18M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
13.83
8.81
+5.02
3.90
2.59
1.29
QQQ
18.26
13.05
+5.21
5.00
1.47
1.17
IWM
19.84
12.86
+6.98
5.12
2.54
1.24
VIX
74.33
92.16
-17.83
-94.44
0.34
0.64
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
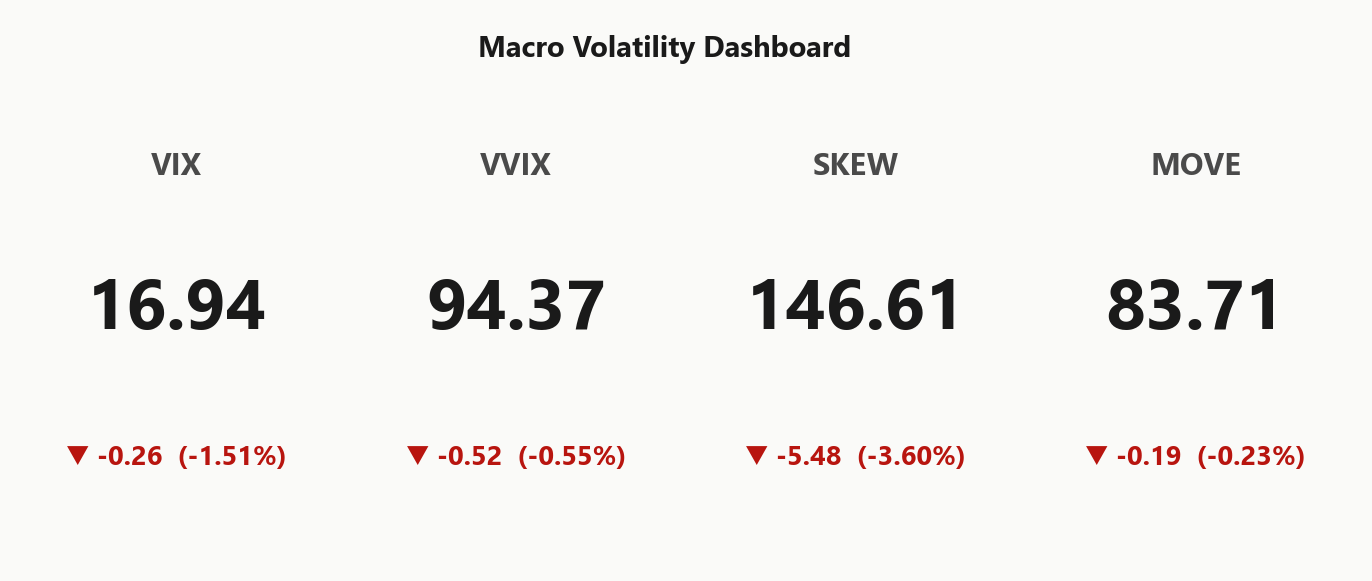
16.94
-1.51%
VVIX
94.37
-0.55%
SPX
7,599.14
+0.18%
SKEW index
146.61
-3.60%
MOVE (bond vol)
83.71
-0.23%
VIX term (9d/30d/3m/6m)
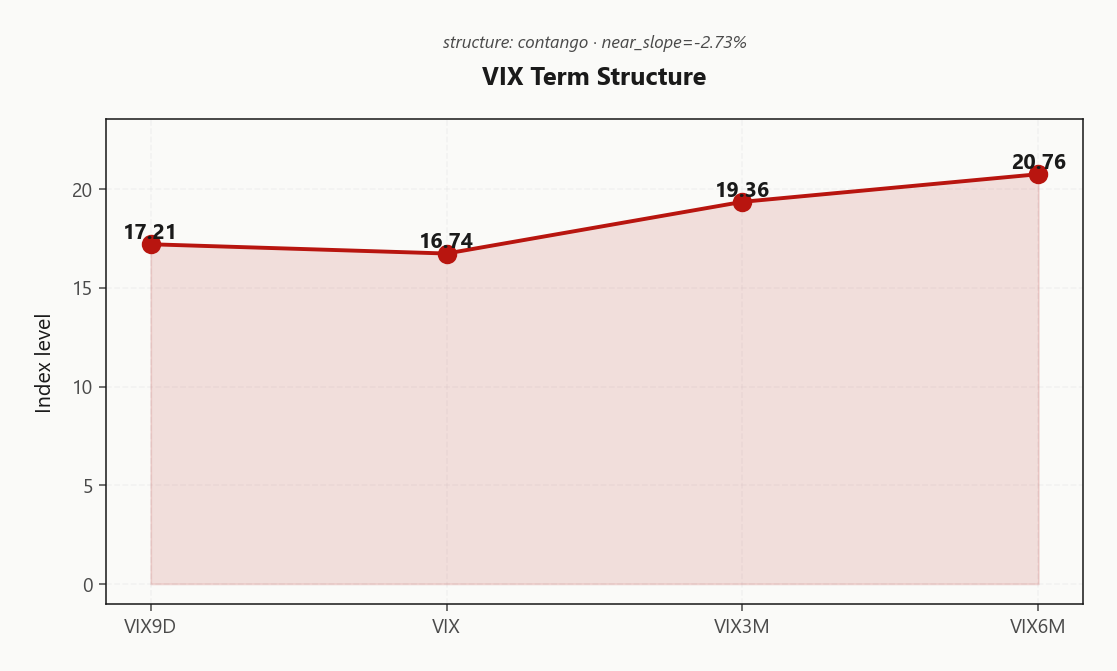
17.21 / 16.74 / 19.36 / 20.76
Flat
VVIX / VIX
5.57
Normal
Regime
Elevated / Watchful
Regime Assessment
VIX prints 16.94, parking the tape squarely in Elevated / Watchful territory. This isn't the panic bucket and it isn't the complacency bucket - it's the sticky middle, the regime that grinds sideways while premium sellers get paid and hedgers keep bleeding theta.
Half-life reads 15 sessions, so mean reversion is slow - this doesn't melt into a low-vol print on its own. Transition math confirms the stickiness: probability of a panic escalation over five sessions sits at 0.05, while the odds of easing into a low-vol regime over ten sessions run 0.25. Odds favor staying put, but the easing path is meaningfully thicker than the stress path.
Trade the regime you're in: Elevated vol pays carry without demanding tail insurance at every roll. Size for a range, not a break.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - sticky mid-range vol that rewards patient carry over directional tail bets.
Trading readVIX modest, VVIX Normal, SKEW at 146.61, MOVE benign - everything confirms suppressive regime, but the SKEW-VIX gap is the divergence to watch as the leading indicator.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX complex prints Contango from VIX9D at 17.21 through spot VIX at 16.74 up to VIX3M at 19.36, with the near slope at -2.73%. Term shape reads Flat - carry is intact for vol sellers rolling down the curve, but the shape isn't steep enough to reward front-end shorts blindly.
Forward 30-60 vol sits at 20.545087004 and 60-90 at 22.0713751271, anchoring the DTE bucket where structurally short-vol expressions get paid. Front-week IV at 19.75 is a poor sell against further-dated vol - event-loaded and thin on carry - while the 30-45 DTE window captures the fattest premium relative to forward realized.
Sell the belly, not the wings of the curve. Iron condors in 30-45 DTE monetize the Contango carry without paying the front-end tax.
What it means for your trading
Term structure is Flat and Contango, so vol sellers earn carry - but the trade lives in 30-45 DTE, not the front week.
Trading readContango at -2.73% near slope pays vol sellers to roll - carry trade intact, but respect the front-end pop as a warning if the slope compresses.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied at 13.83% prints a clean premium over trailing HV20 at 8.81, pushing VRP to 5.02%. The IV-RV engine grades this a Healthy Premium setup - the desk is paid to be short vol, not chasing a compressed spread.
The realized cross tells the accelerator story: RV5 at 9.58 sits above RV20 at 8.81, so realized is drifting higher into the print rather than bleeding out. Premium is fat, but the tape is not going quiet - short-vol structures need defined wings, not naked strangles.
Net: harvest the VRP, but respect the RV5-over-RV20 tilt. Iron condors in the 30-45 DTE bucket monetize the spread without leaving the book exposed if realized keeps grinding toward implied.
What it means for your trading
IV-RV grades as Healthy Premium with VRP at 5.02% and RV5 running above RV20 - sell the premium, but keep wings on.
Skew Convexity
Quarter-delta put IV at 21.92% sits well above ATM at 19.65%, while the call wing at 18.02% trades below ATM - a textbook hedging-demand smile, not tail panic. Skew_25d at 3.9% with a smile ratio of 1.22% is steep, but nowhere near the crisis wings.
The read: downside is bid because books are running paid protection into a negative-gamma tape, not because the market prices a jump. Upside conviction is absent - nobody is paying up for the call wing, so overwrites earn little and lottery calls are a bad use of premium. Naked long puts bleed against this decay curve; put spreads monetize the steep near-money put without funding the flat far wing.
Structure the hedge as a vertical financed by the quarter-delta call, not a lottery ticket. The shape says: respect the tail, but pay for it efficiently.
What it means for your trading
Steep but orderly put skew with a flat call wing - hedge with put verticals financed by the 18.02% call wing, not naked long puts or upside lottery.
Vol-of-Vol Structure
VVIX at 94.37 against VIX at 16.94 pins the ratio at 5.57 - squarely inside the Normal vol-of-vol envelope. The convexity market isn't pricing a binary jump; it's pricing an orderly grind, which is why Standard Size is the right posture on the short-vol book rather than a defensive halving.
Read that alongside the Contango curve and the Elevated / Watchful regime and the message is consistent: carry is intact, tail is not being paid up, and the standard iron condor in the 30-45 DTE bucket sizes normally. The trigger to reprice is a VVIX push through 110 - that's when convexity starts leading spot, and that's when the short-vol book needs its wings tightened, not before.
What it means for your trading
VVIX/VIX at 5.57 keeps vol-of-vol Normal, so Standard Size on short-vol structures - escalate hedges only if VVIX breaks above 110.
Dispersion Spread
Index ATM at 13.83% pairs with Moderate cross-name correlation - the dispersion print says single-name idiosyncrasy is live enough that an SPY hedge won't fully absorb name-specific tape. Cross-strike dispersion at 66.35 against cross-expiry at 2.37 confirms the smile is doing the work, not the term.
Keep SPX/SPY as the preferred vol-sell vehicle: the index carries the Elevated / Watchful regime with Contango carry, and correlation is high enough that condors in the 30-45 DTE bucket still harvest cleanly. Where alpha lives is the other side - buy single-name vol into earnings and idiosyncratic catalysts, particularly across the mega-cap gamma-rebuild cohort where dispersion widens fastest.
Do not assume an index hedge captures name-level risk today. Fund short single-name premium in AI-complex leaders with the SPY iron condor sale; that is the dispersion trade this print asks for.
What it means for your trading
Sell index vol at 13.83%, buy single-name vol - Moderate dispersion means an SPY hedge underprices name-specific tape.
Liquidity & Microstructure
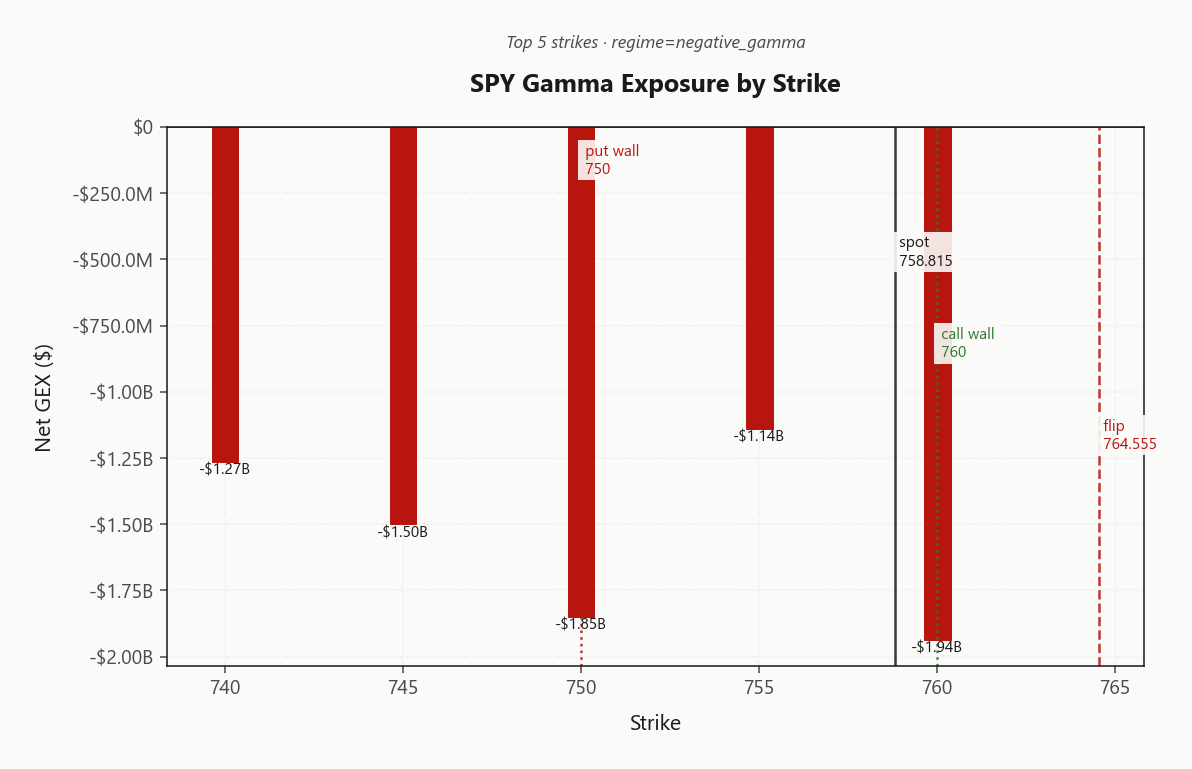
The book anchors at 525 for headline open interest, but that print is legacy LEAP overhang - the strike doing work today is 760.00, carrying -$1.94B of net GEX and sitting exactly where the call wall lives at 760.00. Spot at 758.82 trades under the 764.56 flip, so dealer hedging is amplifying rather than dampening, and every push toward the wall meets the heaviest gamma-negative pocket on the sheet.
That geometry brackets the tape: 750.00 defines the trapdoor, 760.00 caps the rally, and 764.56 is the line where dealer flow flips from accelerant to stabilizer. Charm pivot at 760 confirms the same level as the flow-flip axis, reading Neutral at 0.156164546 distance.
What it means for your trading
Fade rallies into 760.00 where the -$1.94B gamma-negative pocket sits, defend 750.00 as the downside line, and treat any reclaim of 764.56 as the signal that dealer flow turns supportive.
Trading readGamma-negative stack from 750.00 up through 760.00 means dealers amplify moves in both directions inside the range - expect trending breaks, not chop, until spot reclaims the 764.56 flip.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna prints -$85.39B - deeply negative, which means a vol pop forces the street to sell delta into weakness rather than absorb it. That's the accelerant setup: any VVIX push higher compounds directional flow instead of dampening it.
Charm layers on the same side at -$4.9M, drip-feeding supply into the close as short-dated theta decays dealer long-delta exposure. The charm pivot sits at 760 - reclaim it and hedging flow flips constructive, fail it and the late-tape bid thins out fast.
Current read: bias is Neutral at 0.156164546 from the pivot, with spot pressed just under. Structure trades around this line - fade rips into 760.00, respect 750.00, and size short-vol standard rather than heroic while dealer greeks lean this hostile.
What it means for your trading
Vanna and charm are aligned as accelerants, not stabilizers - a vol pop or a close-of-day drift both pull dealer supply the same direction. The 760 pivot is the single tactical line: above it flow turns friendly, below it every rally gets faded and every break gets extended.
Cross-Asset Confirmation
Cross-asset tape reads coherent, not fractured. MOVE at 83.71 keeps rates vol subdued - no credit contagion bleeding into equity gamma, so today's fragility is positioning, not plumbing. Fear & Greed prints 28 (Fear), a defensive sentiment read against a grinding tape - the classic setup where hedgers pay premium and short-vol structures collect the carry.
QQQ at 708.44 and IWM at 286.50 both sit in negative gamma alongside SPY - regime divergence reads Aligned across the index complex. No lead-lag break to trade, no sector fracture leading the tape lower; every core index amplifies moves the same direction, which keeps index vol the cleaner harvest than single-name. Cross-asset tone: Unknown.
Bottom line - subdued rate vol plus aligned equity gamma plus defensive sentiment defines a mean-reverting bias inside the established range. Fade the extremes, sell index premium, and don't overpay for cross-asset tail hedges the correlation isn't confirming.
What it means for your trading
MOVE at 83.71 subdued and QQQ/IWM regimes aligned with SPY confirm equity-only positioning risk, not systemic - Fear & Greed at Fear keeps hedgers paying and short-vol structures paid.
Scenario EV
The structure screen prints Iron Condor as the top-ranked expression with a score of 59, clearing the put spread alternative at 53. That gap isn't cosmetic - it reflects a tape where both wings are payable, not just the downside, so the four-legged structure captures premium the two-legged version leaves on the table.
The 30-45 DTE window is where the math works: far enough out to sit behind front-week event pricing, close enough to harvest theta before the Contango curve can compress. VRP reads Unknown against Normal vol-of-vol at a 5.57 VVIX/VIX ratio - carry intact, tail not pricing binary. Book Standard Size, brackets around 760.00 and 750.00, and let the Elevated / Watchful regime do the work.
What it means for your trading
Iron condor is the ranked trade at 59, and the 30-45 DTE bucket paired with Standard Size sizing is where the risk-reward compounds in your favor.
Levels do the work: fade rallies into 760.00, defend 750.00 as the trapdoor, and treat the charm pivot at 760 as the flow-flip. Spot below the 764.56 flip keeps dealers amplifying, so avoid naked long calls, front-week IV sales, and oversized single-leg tail hedges.
Watch VVIX push through triple-digit stress and any MOVE break from 83.71 - either tightens the short-vol book fast. Until then, this is a Elevated / Watchful tape with a 15 session half-life: sticky, not melting.
What it means for your trading
Structure premium as Iron Condor in 30-45 DTE, bracket the range between 750.00 and 760.00, and let 760 arbitrate the intraday bias.
Ten-year Treasury above 5% into a Fed decision is the single most macro-relevant catalyst on the tape - sets the rate-vol backdrop for every equity vol trade this week.
House takes up Russia sanctions bill - sanctions escalation risk feeds directly into MOVE and oil-linked equity vol; watch for tail-hedge bid if it advances.
US officials meeting Houthis in Oman signals diplomatic de-escalation attempt - a mean-reversion catalyst for geopolitical risk premium in energy and rates vol.
Iran war cost hitting $38B with $3B monthly burn rate is a durable macro overhang - sustained fiscal pressure that keeps duration premium and defensive positioning bid.
Bessent-He Lifeng meeting is the highest-signal US-China event this weekend - trade and tariff headline risk that can reprice cross-asset correlation in a single tape.
China urging US-Iran restraint is a de-escalation input for the geopolitical vol premium currently pinning skew steep.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 16.95 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 764.56 against a spot of 758.82. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 13.83% with a volatility risk premium of 5.02%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 16.94. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime