Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed at 760.67, sitting below the gamma flip at 767.21 - dealers are short gamma with net GEX at -$11.95B, so moves get amplified, not dampened. Key levels: call wall 770.00, put wall 760.00, max pain 756.00 - spot pinned right on the put wall means any break lower unlocks the negative-gamma sell chain toward 760.00. Dealer positioning is hostile: net VEX at -$107.87B means a vol pop forces more delta selling (vanna accelerant), and charm is pushing dealers to sell into close. Vol read: VIX at 17.09 up 7.89%%, VIX9d/VIX/VIX3M at 16.45/16.86/19.15 still in Contango, ATM IV 13.49% vs HV20 8.83 = fat VRP at 4.66% but skew 2.17% says downside is being paid up. QQQ and IWM confirm - all three flagship ETFs are Negative Gamma and cross-asset regime is Aligned. Fear & Greed at 31 = Fear. Bottom line: sell VRP on the 21-30 DTE window via Short Put Spread above the put wall, avoid naked short strangles while spot is beneath 767.21 - the pivot is 760.
Index complex short gamma below flip 767.21 with contango intact and VIX at 17.09
SPY closed at 760.67, below the flip at 767.21, putting dealers firmly short gamma with put wall stacked at 760.00. VIX popped to 17.09 into the AI-hardware unwind, but term structure stays in Contango and VVIX at 94.78 is only normal - no jump-risk repricing yet. Bias is defined-risk downside spreads while the tape stays under the flip.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
760.67
767.21
-0.85%
770
760
756
-$11.95B
Short gamma
QQQ
709.43
718.28
-1.23%
720
700
707
-$5.49B
Short gamma
IWM
287.84
295.95
-2.74%
290
285
290
-$4.96B
Short gamma
VIX
17.10
17.11
-0.07%
20
17
19
-$14.05M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
13.49
8.83
+4.66
2.17
2.70
1.23
QQQ
17.87
12.92
+4.95
2.64
1.46
1.56
IWM
18.71
12.63
+6.08
10.41
2.41
1.03
VIX
75.81
94.42
-18.61
0.34
0.34
0.40
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
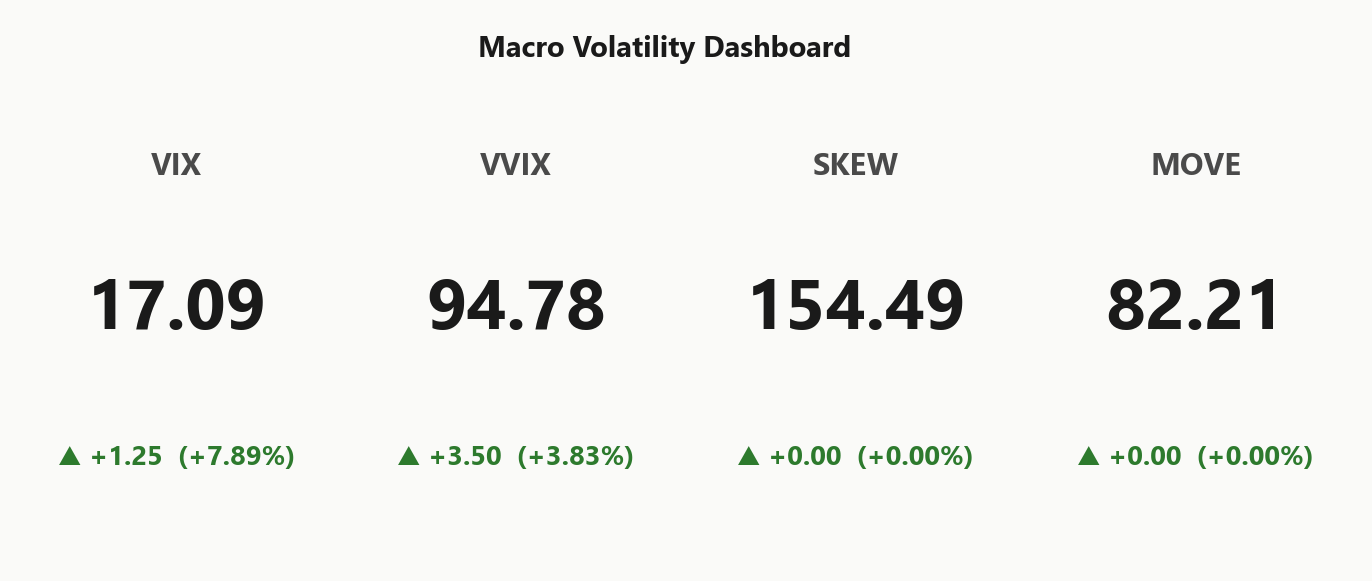
VIX
17.09
+7.89%
VVIX
94.78
+3.83%
SPX
7,619.98
-0.48%
SKEW index
154.49
0.00%
MOVE (bond vol)
82.21
0.00%
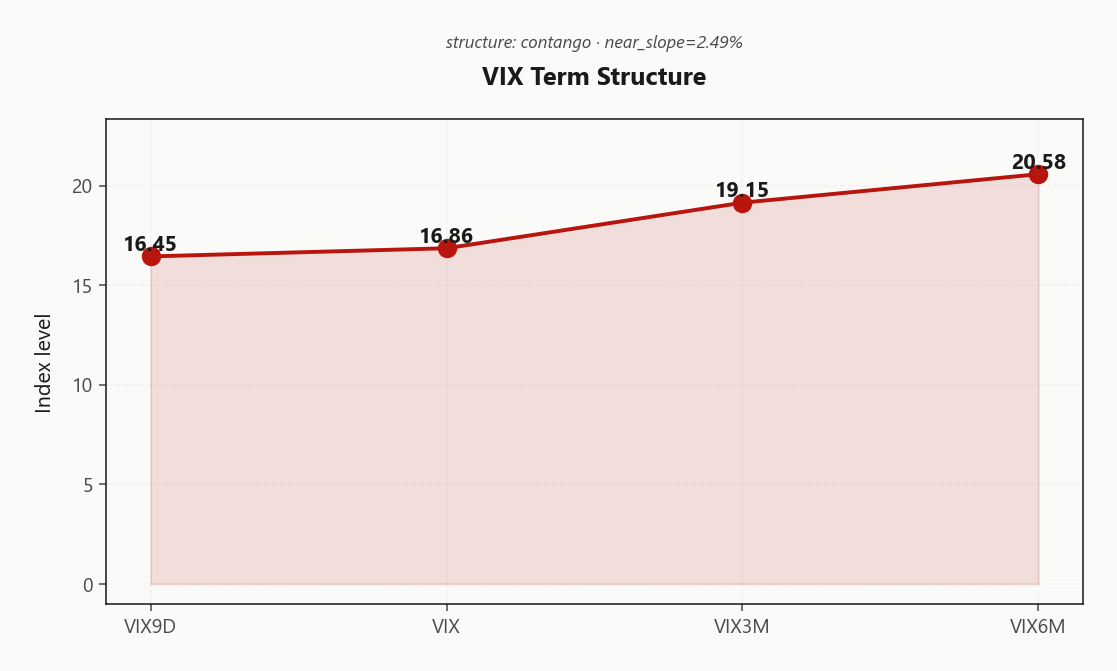
VIX term (9d/30d/3m/6m)
16.45 / 16.86 / 19.15 / 20.58
Steep contango
VVIX / VIX
5.55
Normal
Regime
Elevated / Watchful
Regime Assessment
Regime prints Elevated - Elevated / Watchful - with spot VIX anchored at 17.09. This is the sweet spot where the carry trade still functions: vol is bid enough to pay sellers a meaningful premium, but the tape is not pricing bimodal outcomes. Transition probabilities confirm the read - 0.05 odds of escalating to panic over the next five sessions against 0.45 odds of decaying back to a low-vol state over ten. The distribution is asymmetric toward normalization, not blow-off.
Half-life sits at 15 sessions, which is the operative number for position management. That stickiness gives vol sellers runway to rotate expiries, roll strikes, and harvest theta without being forced into a panic-mark exit. Regimes that decay slowly reward patience; the tape is telling you to size around drift, not around a jump.
Bigger risk is drift lower, not immediate spike. Cross-asset regime prints Aligned and vol-of-vol tags Normal - the ingredients for a disorderly repricing are absent. Trade the elevated-but-sticky read with defined-risk downside structures; avoid confusing watchful with panicked.
What it means for your trading
Regime tagged Elevated / Watchful at VIX 17.09 with half-life 15 sessions - carry still viable, and the asymmetric transition odds favor decay over escalation.
Trading readVIX rising, VVIX confirming, MOVE quiet, SKEW elevated - three of four vol gauges say equity-specific stress; MOVE saying no macro contagion. That divergence is the tell that this is a rotation event, not a crisis.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints 16.45 at the 9-day, 16.86 at the 30-day, 19.15 at the 3-month and 20.58 at the 6-month - a textbook Steep Contango that survived the intraday vol pop intact. Near-slope holds at 2.49%, so despite spot VIX pressing higher, the term structure never inverted and vol sellers keep positive carry across the curve.
Forward vol between 30 and 60 sits at 20.1978699372 versus 21.9168953093 in the 60-90 window - no event bulge, no macro premium building into the belly. The curve is telling you today's stress is spot-anchored, not term-priced. That leaves the 21-30 DTE bucket as the harvest sweet spot: forward vol rolls down toward spot with the curve intact, delivering both theta and roll-down yield.
Curve is in Steep Contango with forward 30-60 vol at 20.1978699372 rolling down toward spot - sell premium in the 21-30 DTE window where roll-down does the heavy lifting.
Trading readContango holding despite the VIX pop tells you the market is treating today as a spot problem, not a structural repricing - vol-carry trades still function, but you want DTE further out than the noisy front week.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV sits at 13.49% against HV20 of 8.83 and HV60 at 11.53 - a fat variance risk premium at 4.66% that keeps vol sellers structurally paid. Realized has not caught implied even through the AI-hardware unwind, so the premium is honest carry rather than a stale mispricing. The catch: dealers sit negative_gamma, so a realized-vol acceleration would rip through the VRP cushion faster than the term structure suggests.
QQQ prints the tech-specific damage - VRP at 4.95% with ATM IV of 17.87% over HV20 12.92, richer than SPY as post-selloff realized bleeds into the index. IWM carries the fattest premium in the complex at 6.08%, flagging small-cap fragility being paid up.
Cross-asset regime is Aligned - the VRP spread across SPY, QQQ and IWM is a live dispersion setup: sell the richest premium (IWM), lean against index vol.
What it means for your trading
Implied is decisively rich to realized across the complex - SPY VRP at 4.66%, QQQ at 4.95%, IWM the fattest at 6.08% - but negative-gamma positioning means defined-risk vol sales, not naked wings, are the way to harvest it.
Skew Convexity
SPY quarter-delta skew prints 2.17% with the smile ratio at 1.19% - the put wing at 13.8% trades a full vol above ATM at 11.86%, while the call wing sits below ATM at 11.63%. Downside is being expensively bid; upside conviction is absent from the surface.
IWM carries the extreme end of the complex - quarter-delta skew at 10.41% and smile ratio 1.86% mean the small-cap tail is being hedged with real conviction, not token protection. QQQ skew at 2.64% is steep but nowhere near IWM's tension - small caps are the cleanest read on fragility.
Structurally this is a defined-risk regime: short put spreads harvest the fat put-wing premium without inheriting the negative-gamma tail. Naked puts underwrite a market whose smile geometry is telling you it expects to move against you, and call-side sales into flat skew earn nothing worthwhile above 770.00.
What it means for your trading
Put skew is paid and call skew is dead - monetize the wing with defined-risk spreads rather than naked puts, and treat IWM's smile ratio at 1.86% as the complex's fragility tell.
Vol-of-Vol Structure
VVIX prints 94.78 against spot VIX at 17.09, putting the vvix/vix ratio at 5.55 - squarely in the Normal zone. Translation: the market is repricing vol, not repricing the distribution of vol. No bimodal tail is being bid, no panic convexity premium on the VIX complex itself.
But watch the direction, not just the level. VVIX drifting higher alongside VIX at 17.09 is the quiet signature of tail insurance being accumulated - not screamed for, but bid in size behind the tape. That is consistent with the AI-hardware unwind reading as an equity rotation event rather than a macro shock, corroborated by MOVE at 82.21 staying subdued.
Sizing implication: Standard Size. No vol-of-vol premium to force position cuts, but no cushion either - if VVIX breaks convexity higher while spot VIX stalls, that is the tell to de-gross before the tape does it for you.
What it means for your trading
Vol-of-vol reads Normal at ratio 5.55 - carry trades still function at Standard Size, but a rising VVIX under a stable VIX would flip the read from benign to hostile.
Dispersion Spread
Index premium sits calmer than the single-name tape. SPY ATM IV prints 13.49% while QQQ carries 17.87% and IWM tops the complex at 18.71% - a clean spread that says AI-hardware pain is still idiosyncratic, not bleeding uniformly into broad-index premium. Cross-asset regime tags Aligned, so the dispersion is a name-selection story, not an index breakdown.
QQQ carries the sector-specific damage - that's where the Anthropic-driven de-gross and semi unwind concentrate, and where realized has genuinely stepped up. IWM's premium isn't tech contagion; it's small-cap fragility being repriced independently, which is why its skew and IV both sit richer than SPY without matching flow evidence.
Preference: harvest index vol via SPY/SPX rather than chasing single-name premium here. Single-name IV is compensating for real event risk; index IV is compensating for correlation that hasn't broken. Sell what's overpaid for the wrong reason, own - or avoid - what's paid for the right one.
What it means for your trading
SPY IV at 13.49% sits meaningfully below QQQ 17.87% and IWM 18.71%, so the dispersion favors index vol sales over single-name during this regime - the AI-hardware repricing is doing the work in tech and small-caps while the index correlation stays intact.
Liquidity & Microstructure
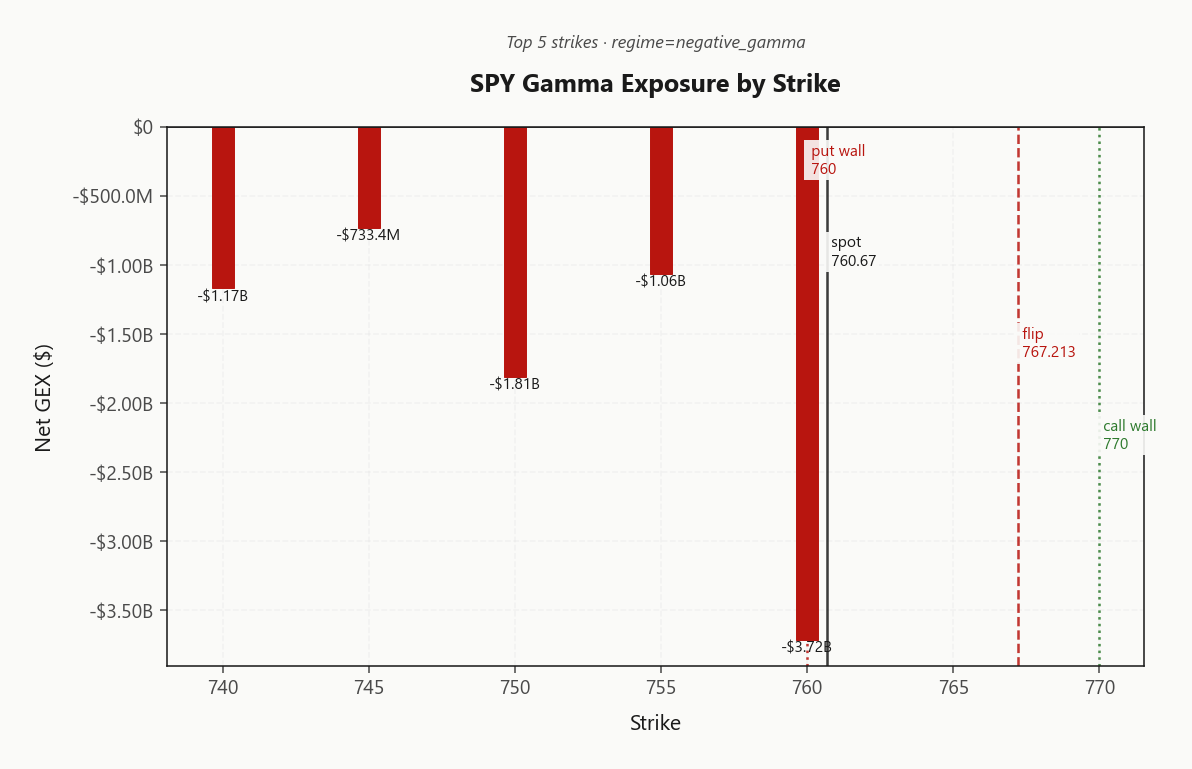
Open interest still anchors at 525 from legacy long-dated positioning, but that's tourist geography - the tactical fight is stacked at 760.00, where net gamma prints -$3.72B. Spot is pinned directly on the 760.00 put wall, and the flip sits overhead at 767.21. That gap defines today's tape: dealers are hedging with direction, not against it.
The put wall is doing double duty as magnet and trapdoor. Hold it and the pin dynamic keeps range compressed while premium bleeds; lose it and the concentrated short-gamma pocket at 760.00 unlocks a mechanical sell chain with no dealer bid underneath until the next strike cluster resolves. Above, the 770.00 call wall caps any reflex rally and provides the natural short strike for anyone fading strength back into the flip.
Regime label: Negative Gamma. Book depth is Deep - the levels will hold their shape, but the flow around them is amplifying, not absorbing.
What it means for your trading
Spot sitting exactly on 760.00 with the flip at 767.21 makes this a single-level decision: pin above, cascade below. Trade defined-risk around the put wall until spot reclaims the flip.
Trading readThe heaviest negative gamma is stacked right where spot is trading - meaning dealers will chase every move today rather than fade it. Break the put wall and the sell chain unlocks toward the next strike cluster; hold above and the flip becomes the target on any bounce.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer greeks are stacked hostile. Net vanna sits at -$107.87B - a short vanna book of that size means any tick higher in 17.09 forces desks to sell delta into the move, not fade it. That is the accelerant sitting under the tape while spot trades beneath the flip at 767.21.
Charm compounds the problem. With net charm at -$3.5M, the daily decay bleed pushes dealers to sell into the cash close rather than buy it back - the opposite of the pin-and-dampen behavior that governs positive-gamma tape. Combined with short gamma, there is no offsetting force in the greek stack today.
Everything routes through one line: 760, which is also the put wall. Bias reads Neutral here, but that is a knife-edge label - hold and dealer flow stabilizes, break and vanna plus charm fire in the same direction toward 760.00. Trade defined-risk downside; avoid naked short wings while the pivot holds.
What it means for your trading
Short vanna at -$107.87B plus charm at -$3.5M means a VIX push higher forces dealer selling and end-of-day flow leans offered - 760 is the single line that decides whether the accelerant fires.
Cross-Asset Confirmation
Bond vol is the tell: MOVE at 82.21 is subdued while equity vol pops - this is an equity/AI-hardware unwind, not a credit event. When Treasuries stay calm through a tech de-gross, the contagion channel is closed and the tape can heal without a macro repricing.
Cross-asset regime prints Aligned: QQQ at 709.43 and IWM at 287.84 both flag Negative Gamma alongside SPY. Broad short-gamma stance across the flagship ETFs means fragility is index-wide, but with MOVE anchored the trigger stays sector-local - dispersion setups over macro hedges.
Fear & Greed at 31 (Fear) sits mid-range with VVIX still normal - the classic contrarian setup if VIX peaks near-term and spot reclaims the flip. Below the flip, sentiment doesn't matter; dealer flow does.
What it means for your trading
Quiet MOVE against a bid VIX confirms an isolated equity event with cross-asset regime Aligned - trade the rotation, not a macro tail.
Scenario EV
Structure ranking puts Short Put Spread at the top with a score of 57, edging the iron condor at 54. The condor loses because the call wing is dead weight - with spot pinned at 760.00 and the tape sitting beneath the flip at 767.21, the upside premium doesn't compensate for the drag on breakeven or the wing risk that never gets tested.
Optimal window is 21-30 DTE - far enough out to let forward vol roll down from 20.1978699372, close enough to still monetize the fat VRP at 4.66% and the steep put skew at 2.17%. Defined-risk downside is the point: dealers stay short gamma while spot lives under 767.21, so naked short puts carry an amplification tail you don't want to wear.
Sizing stays standard - VVIX at 94.78 is Normal, no bimodal jump-risk repricing to force a haircut.
What it means for your trading
Short put spread wins on score and on regime fit - you harvest the 4.66% VRP and pay up for steep put skew without wearing the short-gamma tail. Trade it in the 21-30 DTE window at standard size.
Actionable Summary
Trade the Elevated / Watchful regime with defined-risk structures while dealers stay pinned short gamma beneath the flip at 767.21. Preferred expression: Short Put Spread in the 21-30 DTE window, harvesting the fat VRP at 4.66% without leaving the call wing exposed to a vanna-accelerated squeeze.
Anchor the book to the pivot at 760 - the put wall doubles as today's decision line. A clean break of 760.00 unlocks the negative-gamma sell chain toward 760.00; hold above and mean-reversion targets the flip. Standard sizing per the normal VVIX read at 94.78 - no bimodal repricing to force position cuts yet.
Avoid naked short strangles, undefined-risk wings, and chasing weakness under the flip. With net VEX at -$107.87B and cross-asset regime Aligned, tail insurance is quietly bid - respect it.
Rotation into defensives while tech breaks - confirms the theme that this is a sector unwind, not an index-wide risk-off event, which is exactly what MOVE and VIX term structure are pricing.
A near-certain Fed rate hike is now the base case - bond vol and equity term structure will care more about the December path from here than the November print itself.
The Anthropic safety warning is the proximate trigger for AI-hardware repricing - determines whether today's move is a one-day de-gross or a structural repricing that widens VRP across QQQ.
The buy-the-dip framing from mainstream financial media is the sentiment tell - often marks short-term bottoms in sector-specific unwinds when dealers are already short gamma.
Framing today's oil resilience as a marathon, not a sprint, matters for the persistence of the energy-vs-tech rotation trade underlying today's regime.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.10 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.21 against a spot of 760.67. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 13.49% with a volatility risk premium of 4.66%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.09. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime