Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 758.14 sitting below the gamma flip at 762.49 with net GEX at -$16.52B - dealers are unambiguously short gamma and any move gets amplified. Call wall 770.00, put wall 755.00, max pain 757.00 - spot is pinned inches from max pain but the flip is the level that matters, and we're below it. Dealer vanna at -$76.04B means a further VIX pop from 17.71 forces more delta selling; charm at -$470.2K keeps late-day pressure to the downside unless we reclaim flip. VIX9D 15.59 vs VIX 17.74 vs VIX3M 18.87 - still Contango at 13.79%%, so vol sellers still get paid the curve; VRP 7.52% confirms options rich to realized. Bottom line: fade the vol pop with defined-risk Short Put Spread in the 21-30 DTE band; do NOT chase downside naked below flip - reclaim of 762.49 flips the tape back to mean-revert.
Negative gamma across SPY/QQQ with VIX spike above 17.71 - dealer flow amplifies moves, oil shock in play
SPY at 758.14 is trading beneath the gamma flip at 762.49, flipping dealers short-gamma just as VIX pops to 17.71 on a Middle East oil shock. QQQ mirrors the same negative-gamma posture at 708.76, while VIX term structure remains in Contango - the market is stressed near-term but not yet pricing regime break. With VRP still active at 7.52% and VVIX only 98.19, this is a fadeable spike, not a crush event - but sizing must respect the Elevated / Watchful regime.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
758.14
762.49
-0.57%
770
755
757
-$16.52B
Short gamma
QQQ
708.76
713.40
-0.65%
720
700
705
-$7.44B
Short gamma
IWM
288.39
-
-
300
285
290
-$5.53B
-
VIX
17.73
-
-
20
17
19
$19.74M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
15.92
8.40
+7.52
-12.87
2.61
-
QQQ
23.63
12.81
+10.82
-22.90
1.41
-
IWM
20.46
12.84
+7.62
-17.50
2.37
-
VIX
75.47
82.13
-6.66
-5.32
0.36
-
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
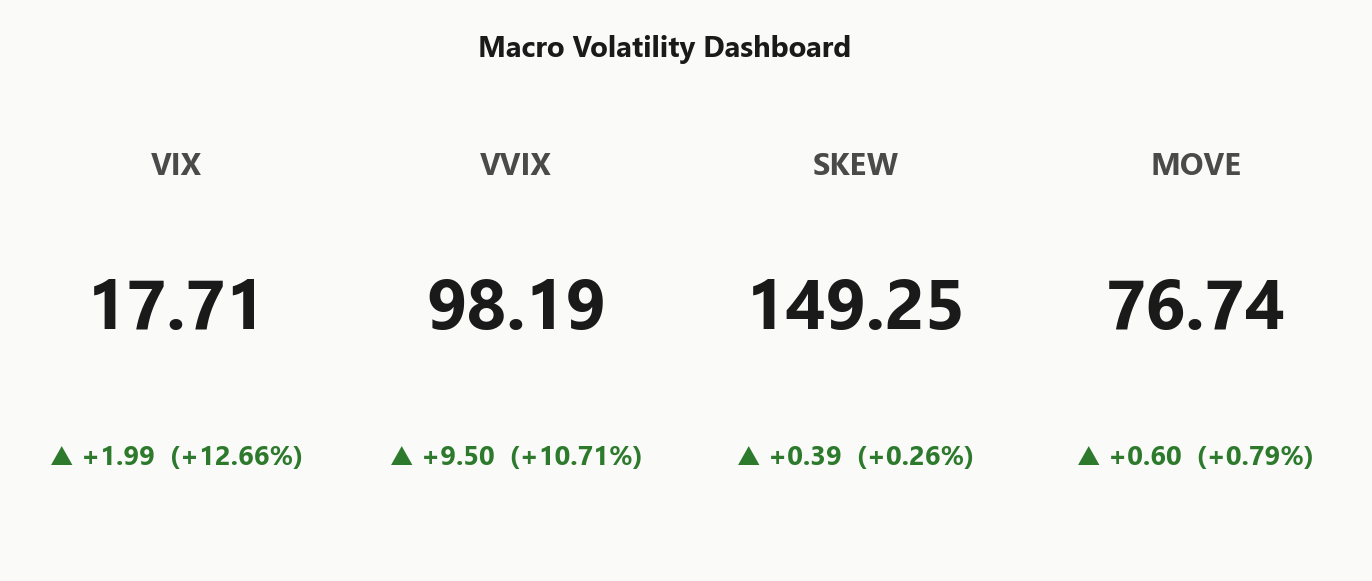
17.71
+12.66%
VVIX
98.19
+10.71%
SPX
7,597.02
-0.52%
SKEW index
149.25
+0.26%
MOVE (bond vol)
76.74
+0.79%
VIX term (9d/30d/3m/6m)
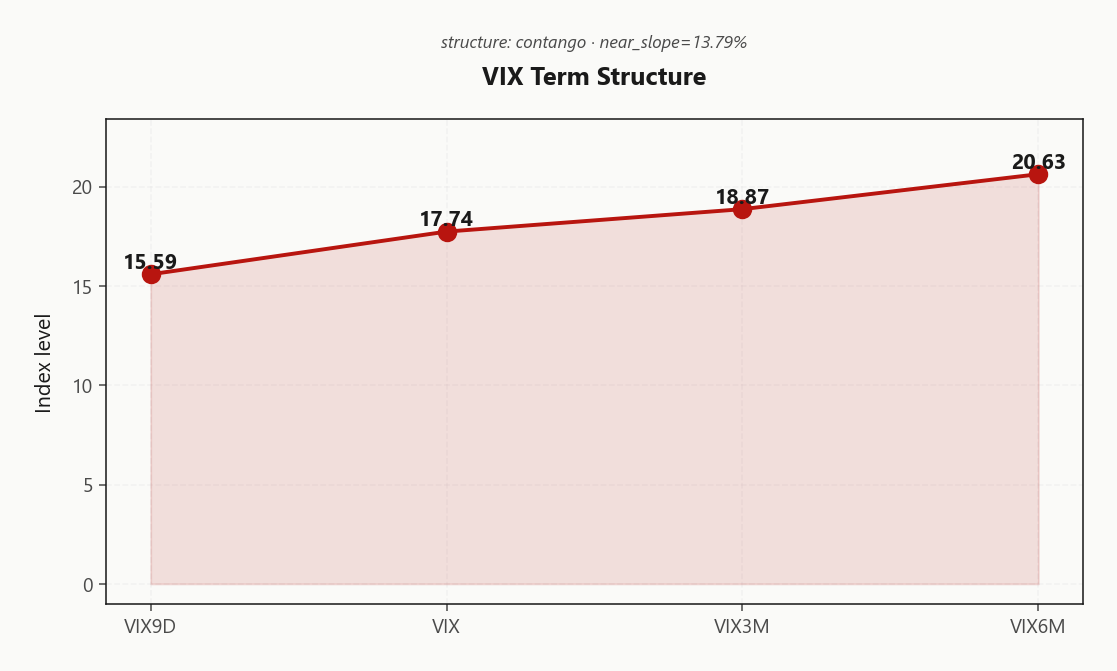
15.59 / 17.74 / 18.87 / 20.63
Contango
VVIX / VIX
5.54
Normal
Regime
Elevated / Watchful
Regime Assessment
The tape sits in Elevated / Watchful territory with VIX anchored at 17.71 - elevated enough to demand respect, not so extreme that structural short-vol carriers should capitulate. Modeled half-life of 15 sessions says this vol level persists but does not compound: panic-regime probability sits at 0.05 over five sessions, while return-to-low prints 0.45 over ten. Base rate favors decay, not escalation.
Regimes this sticky punish directional courage. Fading the VIX pop with defined-risk is paid - chasing it naked is not. The upgrade triggers are cleanly defined: VVIX push through the century-plus zone, MOVE break higher out of its benign range, or VIX term structure inversion out of Contango. Absent those, Yellow signal governs - watchful, not defensive-max. Size structures at Standard Size, harvest the VRP, and let the half-life do the work.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - elevated vol sticks around but does not spiral, so structural short-vol carry stays paid until VVIX, MOVE, or term structure inversion flips the signal.
Trading readVIX up hard, VVIX up in sympathy but not extreme, SKEW steady, MOVE benign - this is an equity-only vol pop, not a broad cross-asset shock. Divergence between MOVE and VIX historically fades toward MOVE, not the other way.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure is holding Contango through the front-end pop - VIX9D at 15.59 still prints beneath VIX 17.74, with VIX3M 18.87 anchoring the belly. The curve is telling you this shock is being priced event-specific, not regime: no crisis bid rolling into the back, no inversion signaling sustained stress.
Near-slope at 13.79%% keeps structural short-vol carry funded, and long-dated demand is steady with VIX6M at 20.63 - no panic hoarding of convexity out the curve. Forward 30→60 implied at 19.4103464678 confirms roll-down remains profitable for carriers willing to sit through the front-end noise.
Signal reads Contango - structural carry available at Green - treat this spike as fadeable. Best edge sits in the 21-30 DTE band where implieds compress hardest into the contango carry, away from the gamma-amplifier zone up front.
What it means for your trading
Curve shape says episodic shock, not regime break: Contango intact with forward vol at 19.4103464678 keeping short-vol carry paid. Sell the belly, not the front.
Trading readStructure Contango with near slope 13.79%% - vol carry trade still funded and market NOT pricing sustained stress; sellers of front-end vol collect the roll-down premium.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV sits at 15.92% against HV20 of 8.4, leaving VRP wide at 7.52% - options remain rich to realized even after today's tape. HV60 at 12.2 confirms the recent path nowhere near what implieds are demanding; sellers of premium are still being paid to sit through the shock as long as spot mean-reverts around the 757 pivot.
Cross-index, QQQ VRP 10.82% prints even wider - the NDX complex is the richer harvest, and dispersion setups favor selling QQQ vol over SPY here. IWM VRP 7.62% is the tightest of the complex, so short-vol carry there does not compensate for the small-cap oil-shock beta - skip it.
The risk to the trade is realized catching up: if today's intraday range breaches the ATM straddle, VRP compresses fast and the short-vol edge evaporates. Monitor tape range against implied and be ready to cover if HV20 starts closing the gap to 15.92%.
What it means for your trading
VRP at 7.52% keeps short-vol structures paid despite the gamma-flip break, with QQQ VRP 10.82% the richest harvest and IWM the one to skip. Watch realized vs ATM straddle intraday - a range breach collapses the edge.
Skew Convexity
Front-expiry 25-delta skew prints -12.87% with smile ratio at 0.53% - puts are firmly bid but the wing is ordered, not panicked. Put 25d IV at 14.27% against ATM 37% and call 25d 27.14% traces a smile where left-tail hedges pay up meaningfully but the marginal buyer is disciplined institutional, not a tail-grab.
QQQ carries steeper convexity at -22.9% - tech is leading the fear-pricing complex as mega-cap concentration risk repriates faster than broad index. SKEW index at 149.25 corroborates: tail-hedging demand is elevated but stable, not the vertical bid you see at true panic thresholds.
Structure edge: the shape rewards put spreads over naked puts - skew is paying you to sell the far wing on the short leg while owning defined convexity closer to spot. Naked long puts overpay for a tail the market is already hedging in ordered fashion; the spread monetizes the steepness rather than fighting it.
What it means for your trading
Skew at -12.87% with smile ratio 0.53% says left-tail is bid but ordered - sell the wing via put spreads to harvest steepness, don't chase naked puts into a hedge already priced.
Vol-of-Vol Structure
VVIX prints 98.19 against VIX at 17.71 - a jump of 10.71% in sympathy with the front-end pop, but the absolute level stays Normal. No bimodal outcome being priced here; the vol-of-vol tape refuses to bid jump risk to the extremes that mark genuine regime breaks.
The VVIX/VIX ratio at 5.54 sits squarely in the normal zone - vol-selling structures are unimpaired and short-convexity carry remains intact. Signal reads Green, which is the tell: dealers may be short gamma on spot, but the second-derivative complex is not screaming for protection. Sizing guidance stays Standard Size on high-conviction shorts.
Trigger to reassess is unambiguous: a push through the triple-digit VVIX handle marks the first warning, and a decisive break above the mid-hundred-and-tens tier is the regime-shift line. Below that, this is a fadeable vol pop - not a crush event demanding defensive-max positioning.
What it means for your trading
Vol-of-vol at Normal with VVIX/VIX ratio 5.54 greenlights Standard Size on defined-risk short-vol structures - watch VVIX for the regime-flip trigger, everything below is a fade.
Dispersion Spread
Index vol geometry is telling us where the edge lives: SPY ATM IV at 15.92% trails QQQ at 23.63% by a spread that keeps widening, and IWM sits between them at 20.46%. That gap is not diversification at work - it is mega-cap concentration bleeding through, single-name idiosyncratic risk failing to net down into the index basket the way a healthy correlation regime would deliver.
Read it as a dispersion setup: long single-name premium, short index vol. QQQ carries the richest implied because AAPL, META, MSFT, NVDA are each running their own tape today - dealer flow is repositioning stock-by-stock and the index is inheriting the sum. SPY, by contrast, is where the VRP still gets paid cleanly against realized. IWM's premium reflects the small-cap tail from the oil pass-through, not a broad-basket bid.
Cross-asset alignment - SPY and QQQ both Negative Gamma, tone Aligned - kills the case for basket hedges here; correlations are too high for the index put to isolate the mega-cap risk. Sell SPY vol structures, harvest the wide leg; leave single-name premium alone or own it.
What it means for your trading
QQQ IV premium to SPY at 15.92% reflects unpriced mega-cap concentration - the dispersion trade is long single-name, short index vol, with SPY the cleanest short-vol vehicle. Basket hedges lose efficacy while cross-asset regime stays Aligned.
Liquidity & Microstructure
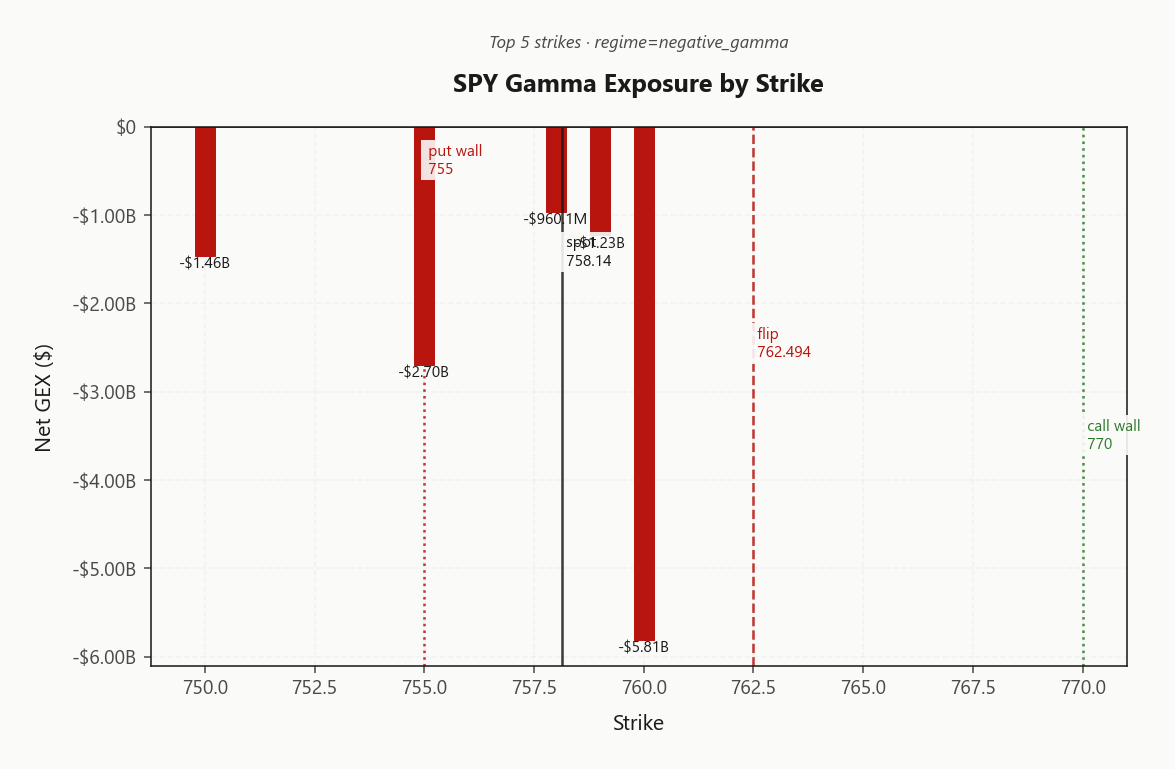
SPY prints 758.14 beneath the gamma flip at 762.49 - dealers are unambiguously short gamma here, and every tick lower forces mechanical selling that begets more selling. The pain zone is anchored at 760.00 where net GEX sits at -$5.81B, the single largest concentration in the book and the strike that governs today's tape.
Above spot, the 770.00 call wall is the reclaim target - get back through it and dealer flow flips supportive, regime rotates back to positive gamma. Below, the 755.00 put wall is the first tier where dealer selling exhausts and mean-reversion bids show up. Deeper still, the highest-OI strike at 525 flags where index-hedging longs have parked size - that's structural protection, not directional puppy-chasing.
P/C OI at 2.606 confirms the defensive tilt is institutional hedge flow, not panic. Book is deep - trade the levels, not the middle.
What it means for your trading
Below the flip at 762.49, dealer hedging amplifies rather than dampens; 755.00 is the first exhaustion tier and 770.00 is the reclaim that flips the regime. P/C OI at 2.606 says the flow is hedged, not panicked - trade the walls.
Trading readDeep negative gamma stacked at 760.00 and 755.00 - dealers amplify selling below the 762.49 flip, so any break lower gets faster, not slower. Watch for reclaim of flip as the switch back to mean-reversion tape.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net vanna at -$76.04B is the accelerant here - dealers get progressively shorter delta as implied vol climbs, so any further push in VIX from 17.71 mechanically forces additional index selling on top of an already Negative Gamma book. This is the second-derivative problem: it's not just that dealers are short gamma, it's that the short-gamma grows with vol.
Charm sits at -$470.2K with the pivot anchored at 757 - pivot type Max Pain, current bias Neutral. Reclaim of 757 and charm flips supportive into the close as time-decay unwinds dealer short-delta. Stay below it and late-session charm bleeds stack directly on top of the negative-gamma amplifier - that's when the tape gets ugly fast.
Vanna at -$76.04B makes any VIX push from 17.71 self-reinforcing to the downside; charm at -$470.2K keeps late-day pressure negative unless spot reclaims the 757 pivot, at which point time decay flips into a tailwind.
Cross-Asset Confirmation
MOVE sitting at 76.74 is the tell - bond vol is not confirming the equity spike, so this tape reads as an equity/energy shock rather than a credit event. Fear & Greed at 36 rated Fear tells you sentiment came in already defensive, which caps the marginal panic bid and favors mean-reversion into fade setups.
QQQ printing 708.76 and IWM at 288.39 are co-selling with SPY - cross-asset tone is Unknown and regime posture Aligned, so there's no divergence to hide behind but also no credit-market amplifier. Historically, geopolitical/energy shocks mean-revert on a session-to-week horizon; credit shocks compound.
IWM regime Unknown vs SPY Negative Gamma - small-caps carry the fatter oil pass-through beta and are the leading edge if this cracks further. Watch IWM for the first tell; fade in the mega-cap complex.
What it means for your trading
Bond vol at 76.74 refusing to confirm the equity spike, combined with Fear & Greed already at Fear, frames this as a fadeable energy shock rather than a compounding credit event - lean mean-reversion, watch IWM as the leading break signal.
Scenario EV
Highest-EV structure on the board is a Short Put Spread scoring 71 - defined-risk short vol below spot lets you harvest the 7.52% VRP without eating naked exposure to further gamma amplification beneath the 762.49 flip. Sell the spread below the 755.00 put wall and cap risk at the prior tier - the wall is where dealer selling exhausts, not where it accelerates.
Iron condor prints 65 - viable but demands wider wings given skew at -12.87%; the wing you sell has to survive a re-test of the flip. Optimal tenor is the 21-30 DTE band where contango carry compresses hardest into expiry. Sizing stays Standard Size per the VVIX read at 98.19 - no jump-risk premium bid means full-size on high-conviction shorts is intact.
Signal is Green - highest-EV setup available today, VRP assessment Unknown. Reclaim of 757 flips the tape back to mean-revert; break of 755.00 is the cover trigger.
What it means for your trading
Sell the Short Put Spread in 21-30 DTE below the 755.00 put wall at Standard Size - defined-risk beats naked here because dealers amplify below the flip. Iron condor at 65 only works with wider wings given skew.
Actionable Summary
Bottom line: with SPY beneath the gamma flip at 762.49 and dealers unambiguously short gamma at -$16.52B, the trade is Short Put Spread pitched below the 755.00 put wall in the 21-30 DTE band - harvest the 7.52% VRP with defined risk, not naked exposure.
Levels do the talking: reclaim of the 757 pivot flips charm supportive and swings the tape back to mean-reversion; a break of 755.00 unlocks the next tier of dealer selling as vanna at -$76.04B forces more delta out on any further VIX push from 17.71. Regime reads Elevated / Watchful - watchful, not panic, with VVIX at 98.19 and MOVE at 76.74 refusing to confirm.
Do: defined-risk put spreads, and treat 757 as the intraday flip tell. Avoid: naked short vol, chasing puts below flip, or upsizing before VVIX/MOVE align. Watch: reclaim of 762.49 - that is the switch back to mean-revert structures.
What it means for your trading
Sell defined-risk put spreads in the 21-30 DTE band below 755.00 to harvest 7.52% VRP; a reclaim of 762.49 flips the regime back to mean-reversion while a break of 755.00 accelerates dealer selling.
Cramer framing the tape around oil above $100 signals mainstream focus on the energy-shock narrative - retail/institutional attention converges on the same trigger, amplifying flows.
Oil to $105 on Middle East tanker attacks is the direct catalyst for today's vol pop and equity selloff - energy pass-through into inflation expectations reprices Fed path.
Houthi seizure of a Yemeni Red Sea port threatens global energy flows and shipping insurance premia - a structural risk-premium bid that persists beyond intraday headline.
Oracle earnings setup with unusual options activity is a bellwether for AI capex trade - a beat could re-anchor mega-cap tech and pull QQQ back above its flip.
Yields rising into wholesale inflation print stacks with oil shock - a hot PPI would compound the equity-vol narrative and validate the negative-gamma tape.
CNBC noting VIX starting to attract hedges into historically volatile part of calendar validates the setup - flows chasing protection right as VRP is still wide is the dispersion opportunity.
China-Iran sanctions-evasion story keeps Iran risk premium anchored - supply-side uncertainty stays in the tape longer than a headline pop
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.73 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 762.49 against a spot of 758.14. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 15.92% with a volatility risk premium of 7.52%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.71. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime