Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 758.04, sub-flip at 764.26 - dealers are short gamma and net GEX runs -$13.7B, so every push gets amplified rather than fought. Call wall 770.00, put wall 755.00, max pain 759.00 - with spot below flip, expect trend-follow toward the put wall unless we reclaim 764.26 and hand dealers back the long-gamma buffer. Net DEX at -$8.68B plus net VEX -$60.27B means any further vol pop mechanically forces more selling - vanna is hostile until VIX rolls over. VIX at 17.70 (12.6%% today) with VVIX 99.43 - but term structure stays Contango and VRP still runs 6.46%, so front premium is expensive relative to realized 8.52. Bottom line: harvest premium with iron condors in the 30-45 window, respect 755.00 as the trapdoor, and stand down chasing directional puts here - the wings are already paying up.
SPY under gamma flip in negative-gamma amplification, VIX popping to 17.70 but term structure holds contango
SPY at 758.04 sits below the gamma flip at 764.26, flipping dealers short-gamma and amplifying every intraday impulse. VIX popped to 17.70 with VVIX at 99.43 - the pain trade is real, but the term structure at Contango says this is repricing, not regime break. Iron condor sits at the top of the strategy stack with a 30-45 sweet spot; keep sizing standard and respect the 755.00 put wall.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
758.04
764.26
-0.81%
770
755
759
-$13.70B
Short gamma
QQQ
709.62
717.43
-1.09%
720
700
708
-$6.02B
Short gamma
IWM
288.21
-
-
300
285
290
-$5.05B
-
VIX
17.70
-
-
20
17
19
-$13.60M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
14.98
8.52
+6.46
2.30
2.62
1.29
QQQ
20.63
12.90
+7.73
3.61
1.48
1.28
IWM
21.48
12.74
+8.74
2.16
2.42
1.63
VIX
78.68
82.35
-3.67
-74.57
0.36
0.15
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
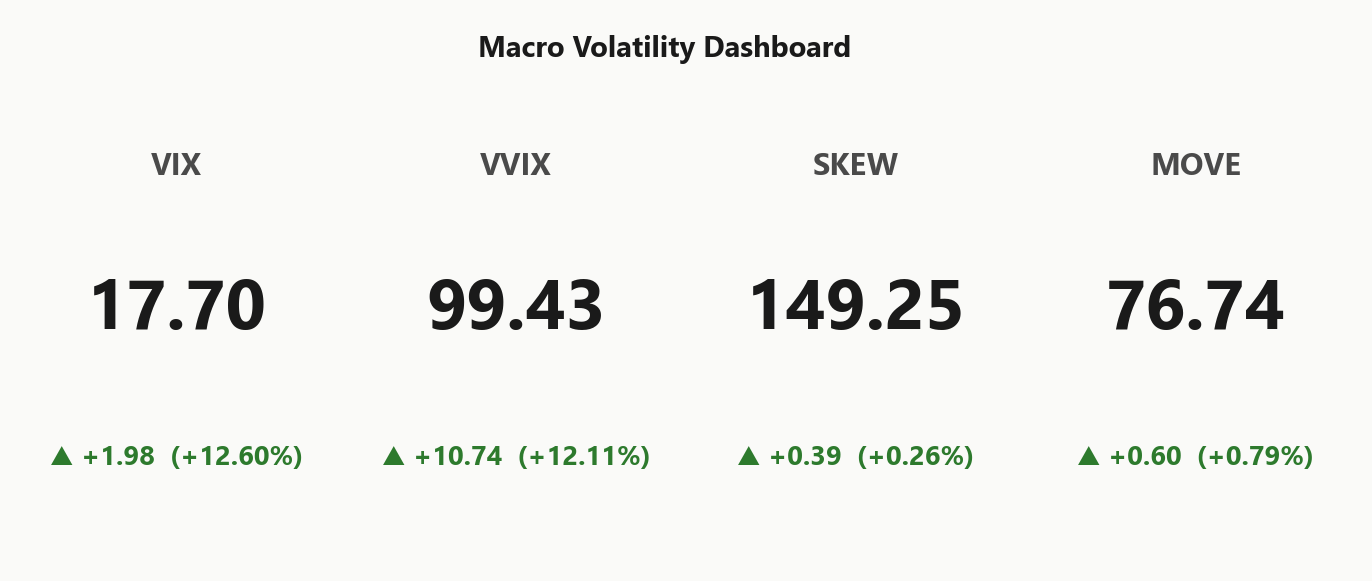
17.70
+12.60%
VVIX
99.43
+12.11%
SPX
7,593.20
-0.57%
SKEW index
149.25
+0.26%
MOVE (bond vol)
76.74
+0.79%
VIX term (9d/30d/3m/6m)
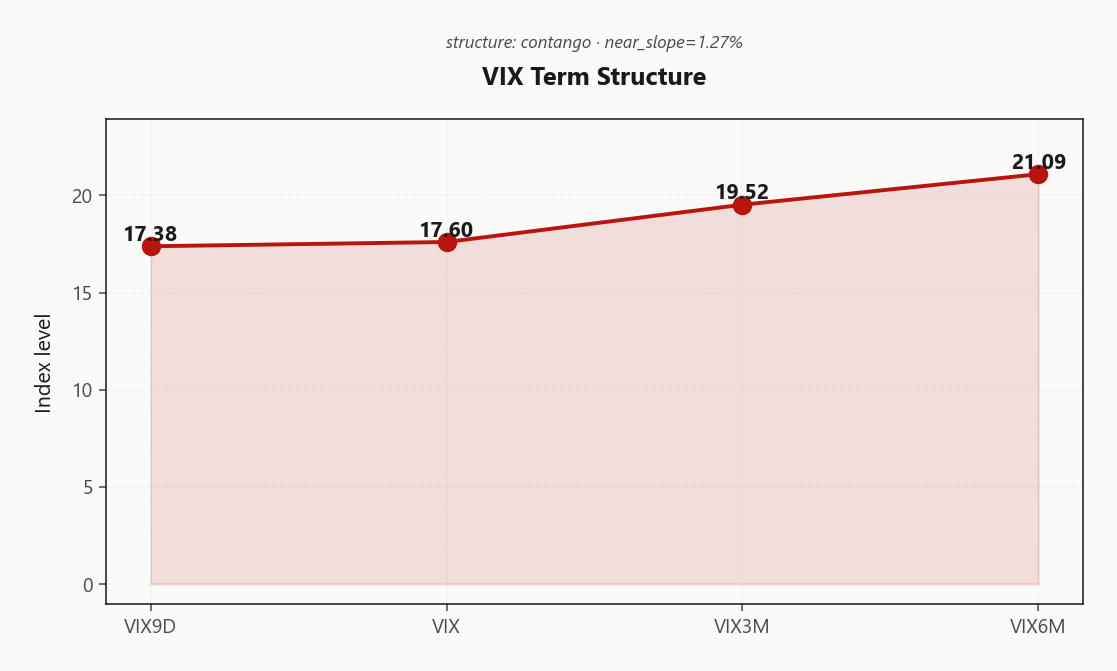
17.38 / 17.60 / 19.52 / 21.09
Steep contango
VVIX / VIX
5.62
Normal
Regime
Elevated / Watchful
Regime Assessment
The regime tape reads Elevated / Watchful with VIX anchored at 17.70 - squarely in the yellow-zone corridor between benign and panic. The transition matrix does the talking: probability of a jump to panic over the next five sessions sits at just 0.05, while the drift-back-to-low probability over ten sessions runs 0.45. Asymmetry favors mean reversion, not escalation.
Half-life clocks 15 sessions - this is a sticky elevated state, not a fragile one perched over a cliff. That distinction matters for structure selection: sticky elevated pays vol sellers who can sit through the noise, while fragile elevated punishes anyone short gamma into a phase transition. The Markov math here is pro-carry.
Bottom line: low panic-transition odds validate the vol-selling stance, and the 0.45 drift-to-low reading makes mean reversion the base case rather than the hope case. Plan the book for elevated conditions into the next couple of weeks - do not price this as a one-day squall that resolves by Friday.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - sticky, not fragile, so premium sales sized standard beat directional hedges. Panic-transition probability of 0.05 against a 0.45 drift-back-to-low reading makes mean reversion the base case.
Trading readVIX and VVIX both spiking together - proportional, not cascading. SKEW moved little and MOVE is calm - no confirmation from tail hedging or from credit that this is anything more than an equity-local vol repricing.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The full VIX curve holds Contango despite the intraday front-vol pop - VIX9D 17.38 sits under VIX 17.60, which sits under VIX3M 19.52 and VIX6M 21.09. That's Steep Contango - the market is repricing the front without believing the back.
Forward 30-to-60 prints 20.4123883953 and 60-to-90 prints 22.5509600683 - vol sellers keep structural roll-down carry even as spot vol spikes. Front slope 1.27%% reinforces the geometry: fear is front-loaded, not term-embedded.
Steep contango - vol sellers favored - the thickest carry sits in the 30-45 DTE window, outside the gamma landmine and inside the vega blowup zone. The curve, not the spot print, is the tell. Until VIX3M rolls over the front, this is a squall, not a regime shift.
What it means for your trading
Curve stays in Steep Contango with VIX9D 17.38 anchored under VIX3M 19.52 - front-vol repricing without back-end confirmation keeps roll-down carry alive. Sell premium in the 30-45 band; watch VIX3M for the regime-flip signal.
Trading readCurve stays in contango despite the intraday front-vol pop - market is pricing today as a squall, not a regime break. As long as VIX3M holds above VIX, the roll-down trade lives; a flat or inverted curve is the signal to flatten short vol.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
SPY ATM IV prints 14.98% against HV20 8.52 and HV60 11.74 - the IV-RV wedge is wide open and VRP at 6.46% is doing the talking. Realized has not accelerated the way implied just did; today's spike is fear-priced, not delivered, and that is the textbook premium-seller setup so long as you don't sit naked into unresolved macro.
The cross-asset carry stack tilts richer as you move down the cap curve. QQQ VRP at 7.73% runs hotter than SPY against a modest HV20 of 12.9 - tech RV has not confirmed the panic bid. IWM at 8.74% is the fattest tribute of the trio, small caps paying the widest fear premium into a tape that hasn't yet delivered the moves.
The tripwire is realized catch-up: if SPY breaches 755.00 the carry trade breaks - RV prints in, VRP compresses, and short-vol books get run over. Until then, harvest.
What it means for your trading
IV is paying you well above what tape is delivering across SPY, QQQ, and IWM - carry is live and small-caps offer the fattest edge, but only while spot holds above 755.00.
Skew Convexity
Quarter-delta puts print 20.26% against calls at 17.96%, with skew running 2.3% and smile ratio 1.13%. Put wing sits over ATM at 19.67% - ordered hedging bid, not tail-chase capitulation. Book is paying up for downside protection but the curve isn't screaming, which is exactly the setup where verticals dominate outright wings.
QQQ skew steepens to 3.61% - tech downside carries a fatter premium than SPY, unsurprising with the mega-cap trio driving the vanna reshuffle. Call side stays flat across the board: no upside conviction bid, so call-spread sales beat strangles for harvesting the asymmetry. Naked long puts fight both the near-wing premium and contango roll - a losing carry profile absent a MOVE confirmation.
Ordered skew stacked on top of steep contango and elevated VRP argues one direction: put spreads over naked puts, iron condors over strangles. The wings are already paying up - buy them defined, sell them richer.
What it means for your trading
Skew is bid but orderly - puts at 20.26% vs ATM 19.67% reflect hedging demand, not panic - so defined-risk verticals extract the premium without paying the wing tax. QQQ skew at 3.61% runs steeper, making tech condors the richer harvest if you can stomach the vega.
Vol-of-Vol Structure
VVIX at 99.43 popped 12.11%% alongside VIX 17.70 - VVIX/VIX ratio prints 5.62, squarely in the Normal band. The market is repricing spot vol, not the vol of vol - no binary premium being loaded into the wings yet.
The pop is proportional, not cascading: VIX +12.6%% against VVIX +12.11%% keeps the ratio pinned inside its normal envelope. That is the tell that gives you license to keep sizing at Standard Size on the iron condor book rather than flinching to half-size. Jump risk is elevated but still uni-modal - the tape is pricing a wider range, not a two-state outcome.
The line to watch is a VVIX push toward the 120 shelf on further downside - that is where jump risk goes bimodal and short-vol carry stops being carry. Until then, the vol-of-vol regime is Normal and the trade is standard.
What it means for your trading
VVIX at 99.43 with a 5.62 ratio keeps the regime Normal - sizing stays Standard Size. Cut to half-size only on a VVIX breach of the 120 shelf coincident with further spot downside.
Dispersion Spread
Index vol pricing runs uneven across the trio: SPY ATM IV at 14.98% sits well below QQQ at 20.63% and IWM at 21.48%. QQQ carries the richest single-name overlay premium of the mega-cap complex, while IWM prints the fattest term premium of the group - small caps paying the widest tribute to fear despite realized action that hasn't caught up.
With correlation still elevated at moderate and cross-asset tone Aligned, the dispersion trade skews cleanly toward selling index vol on SPY rather than fighting rich single-name IV on the QQQ/IWM books. SPY iron condors deliver the cleanest vega/gamma balance - tight spreads, deep liquidity, and a symmetric wing structure that the small-cap and tech-heavy books simply can't match at these prints.
Trade construction: index shorts do the heavy lifting, single-name puts stay strictly hedged rather than expressed as fresh directional risk. Index vol only partially offsets single-name exposure here - do not treat SPY condors as a full hedge for a tech-loaded book.
What it means for your trading
QQQ at 20.63% and IWM at 21.48% both trade richer than SPY at 14.98%, but SPY offers the cleaner vega/gamma balance for the size trade. Sell index vol on SPY, keep single-name puts as hedges only.
Liquidity & Microstructure
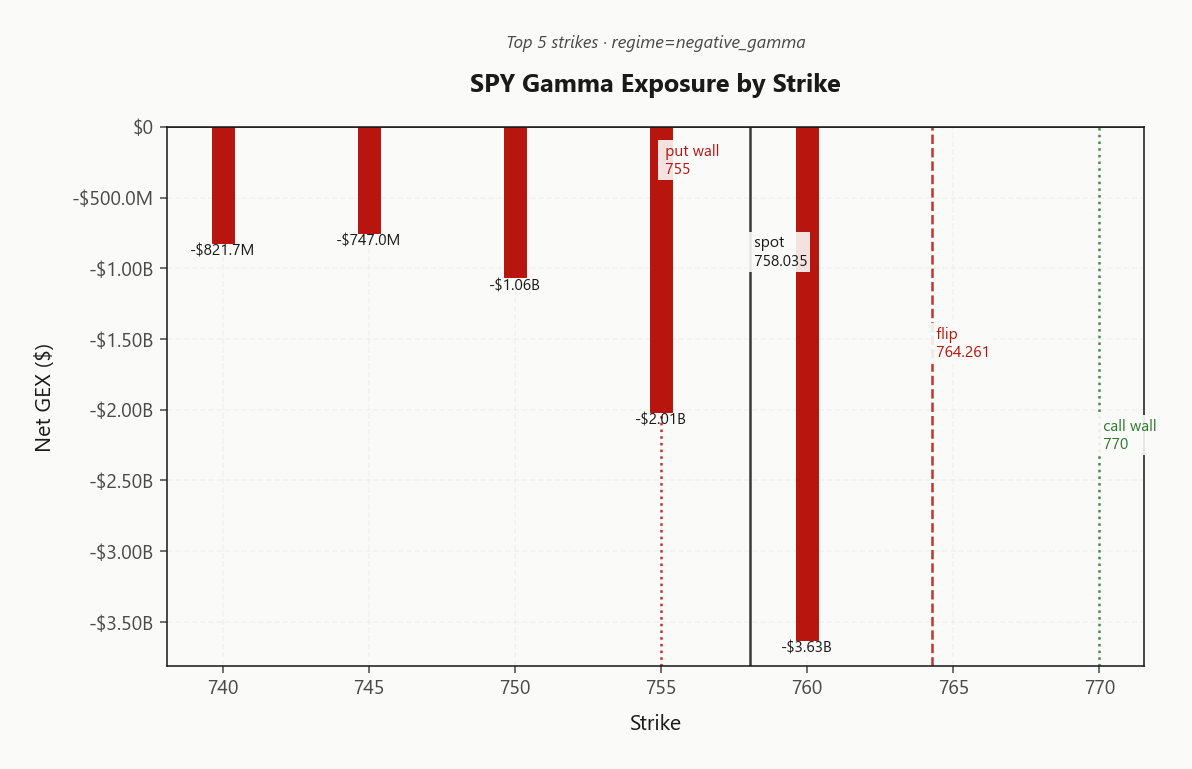
The book's center of mass sits at 525 on OI, but the live battle is compressed around the gamma flip at 764.26 - spot below, dealers short, every impulse amplified rather than absorbed. The intraday magnet is 760.00, carrying -$3.63B of net GEX and acting as the gravity well under current print.
Between the 770.00 call wall and the 755.00 put wall, the fade-strength / respect-the-trapdoor rules apply: sell rallies into any 764.26 reject from below, don't chase lower until the tape actually tests 755.00. Through the put wall, dealer selling stops damping and starts accelerating - that's when the mechanical bid disappears.
OI-weighted DTE at 89.8 tells you the book leans back-month; close-in gamma is thinner than the headline exposure suggests, which is exactly why intraday impulses print larger than the aggregate stack implies.
What it means for your trading
Structure is deep but the gamma that matters right now is thin and negative - treat 764.26 as the pivot, 755.00 as the trapdoor, and 760.00 as the intraday magnet drawing price under spot.
Trading readDeep negative gamma stacked under spot with the biggest single strike at 760.00 - dealers amplify moves in this zone, so treat rallies as fadeable into 764.26 and treat sells as accelerating toward 755.00. Trend follows until the flip is reclaimed.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX at -$60.27B is deeply negative - this is the hostile-vanna configuration where any further pop in 17.70 mechanically forces dealer selling rather than damping it. The reflexive loop is live: vol up, hedges lower, spot down, vol up again. Until VIX rolls over, vanna is an accelerant, not a shock absorber.
Charm tells a quieter story. Net CHEX at -$22.5K reads close to neutral - no strong pin gravity, no time-decay slide into the bell. The charm pivot sits at 759, and current bias reads Neutral. That single level is the switch: reclaim it and charm flow starts buying back into the close; stay under it and dealer flow keeps leaning the wrong way.
Trade the trigger, not the tape. A VIX rollover is what flips the vanna book from accelerant back to constructive - until then, sizing stays disciplined and long-vol chases stay off the sheet.
What it means for your trading
With net VEX at -$60.27B and charm neutral at -$22.5K, dealer flow amplifies further vol pops but offers no natural pin - the 759 pivot is the level to watch for a regime flip back constructive.
Cross-Asset Confirmation
Rates vol is not confirming the equity wobble. MOVE at 76.74 sits muted while VIX rips to 17.70 - that divergence is the tell. When credit and equity vol move in lockstep you get regime shifts; when only equity vol pops, you get squalls. This is the squall footprint, not the credit event.
Fear & Greed prints Fear at 36 - mid-fear, not capitulation. There is real room to fall further before the contrarian-bounce setup fires; do not reach for reversal trades on the current print. If a subsequent leg drives F&G into extreme territory with MOVE joining the party, that's the moment tails start paying - not before.
Index complex is Aligned. QQQ at 709.62 and IWM at 288.21 both track the SPY drawdown - no lead-lag divergence to lean on, cross-hedges balanced. Trade the index, not the spread.
What it means for your trading
Absent a MOVE confirmation and with F&G still in mid-fear at 36, this is an equity-local vol repricing - a squall - not a credit event. Aligned SPY/QQQ/IWM regime removes the cross-asset divergence trade; premium sales beat directional puts until rates vol wakes up.
Scenario EV
Scenario engine crowns Iron Condor at score 64, edging the put spread at 57 - you get paid on both wings with front premium this rich, and the call side is too flat to justify giving up half the carry. VRP reads Unknown against a Steep Contango curve, so the structure that harvests both sides of the smile wins the risk-adjusted contest.
Target the 30-45 DTE window - outside the 0-2DTE gamma landmine where 764.26 whipsaws grind theta into losses, inside the vega blowup zone where a further VVIX push would gap the structure. Center around 759.00, wings outside 770.00 and 755.00.
Sizing stays Standard Size - VVIX/VIX ratio sits in the Normal band, not the cascading regime that would force cuts. Skip strangles until VVIX at 99.43 confirms non-cascading action; defined-risk wings only until vol-of-vol rolls over.
What it means for your trading
Iron condor at score 64 in the 30-45 DTE window is the trade - rich front-month VRP pays for both wings, and defined-risk structure survives a VVIX squeeze that would gap naked strangles.
Actionable Summary
Bottom line: regime is Elevated / Watchful, dealers sit short-gamma under the charm pivot at 759, and the 755.00 put wall is the trapdoor. Scenario engine picks Iron Condor at score 64 in the 30-45 DTE window - that's the carry sweet spot where VRP is thickest and vega stays manageable.
DO: sell iron condors centered around max pain at 759.00, wings outside the 770.00 call wall and 755.00 put wall; fade strength if spot rejects the flip at 764.26 from below. AVOID: naked long premium - VRP at 6.46% pays you to be short, not long - and stop chasing puts unless MOVE at 76.74 confirms the panic.
Watch: reclaim of 764.26 flips the regime back to positive-gamma damping; loss of 755.00 hands dealers the accelerant lower.
What it means for your trading
Elevated but not panicked - harvest the 6.46% VRP with defined-risk iron condors in the 30-45 window and let the 755.00 put wall define your trapdoor. Long vol here is the losing side of the contango-plus-VRP carry until the term structure at Contango breaks.
ECB rate hike layered on top of geopolitical inflation angst - bond-side hawkishness while equity vol is spiking amplifies the risk-off tape but keeps the vol repricing macro not idiosyncratic.
Oil topping $100 with Cramer flagging equity risk-off - commodity-push inflation reflex is a live threat to the rate-cut narrative and to any V-shaped equity bounce.
Oracle options positioning ahead of earnings - the AI-trade barometer prints today, and given NVDA is a top-5 GEX mover, an Oracle miss or beat radiates into the whole complex.
Wholesale inflation data due - the market is holding vol premium precisely because this print is unresolved; a hot number rolls the VIX curve toward backwardation.
Direct meta-signal: hedges flowing into VIX ahead of a historically volatile part of the calendar - confirms this is not just noise, it is calendared-in tail buying.
Macy's beat and raised guidance - quiet reminder that the consumer isn't broken, which caps the recession-panic bid in vol and supports mean reversion
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.70 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 764.26 against a spot of 758.04. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 14.98% with a volatility risk premium of 6.46%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.70. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime