Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed 758.62, sitting below gamma flip 766.51 - dealers in Negative Gamma with net GEX -$11.24B, moves amplified from here. Key levels: call wall 770.00 caps upside, put wall 755.00 is the acceleration line, max pain 758.00 is roughly where price is pinned intraday. Dealer positioning is hostile - net DEX -$13.02B, net VEX -$64.51B, vanna and charm both pulling dealers to sell as vol rises. Vol read: VIX 17.98 up 14.38%%, VVIX 102.88 up 8.87%% flagging jump-risk pricing, term structure Contango with front slope 1.25%%. VRP still positive at 6.71% vol points, but VVIX pop says premium is being paid for reason. Bottom line: iron condor scored 60 at 30-45 DTE - sell defined-risk premium around the 755.00/770.00 rails, skip naked strangles until VVIX cools.
Negative gamma across SPY/QQQ with VIX popping 14.38%%, contango intact - iron condor regime at 30-45 DTE
SPY closed at 758.62 - meaningfully below the gamma flip at 766.51, flipping dealers into negative-gamma amplify mode with net GEX at -$11.24B. VIX popped to 17.98 (+14.38%%) with VVIX spiking to 102.88, yet VIX term structure remains in Contango - vol carry still pays despite the intraday shock. Regime: elevated but not panic, iron condor at 30-45 DTE scores 60, the defined-risk premium harvest of choice.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
758.62
766.51
-1.03%
770
755
758
-$11.24B
Short gamma
QQQ
709.03
717.91
-1.24%
720
700
707
-$4.64B
Short gamma
IWM
287.86
-
-
300
285
290
-$4.78B
-
VIX
17.84
-
-
20
17
19
-$1.75M
-
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
15.27
8.56
+6.71
3.36
2.63
1.37
QQQ
20.93
12.97
+7.96
4.60
1.48
1.37
IWM
22.93
12.93
+10.00
3.66
2.45
2.20
VIX
80.32
83.98
-3.66
-78.43
0.36
0.16
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
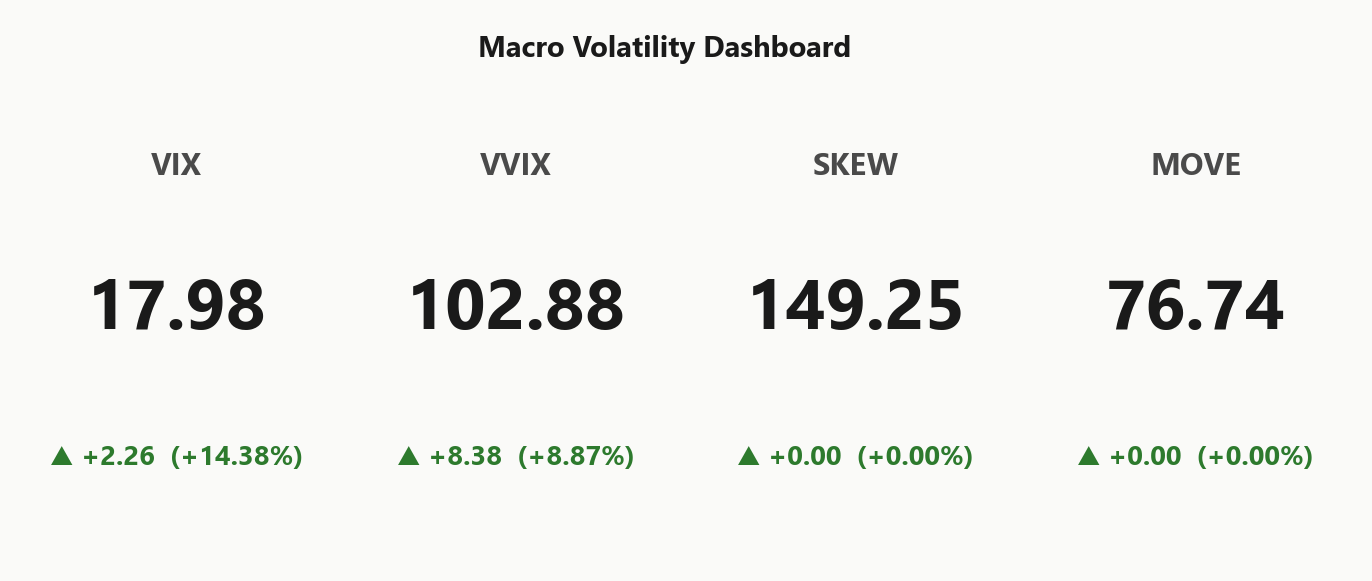
17.98
+14.38%
VVIX
102.88
+8.87%
SPX
7,591.70
-0.58%
SKEW index
149.25
0.00%
MOVE (bond vol)
76.74
0.00%
VIX term (9d/30d/3m/6m)
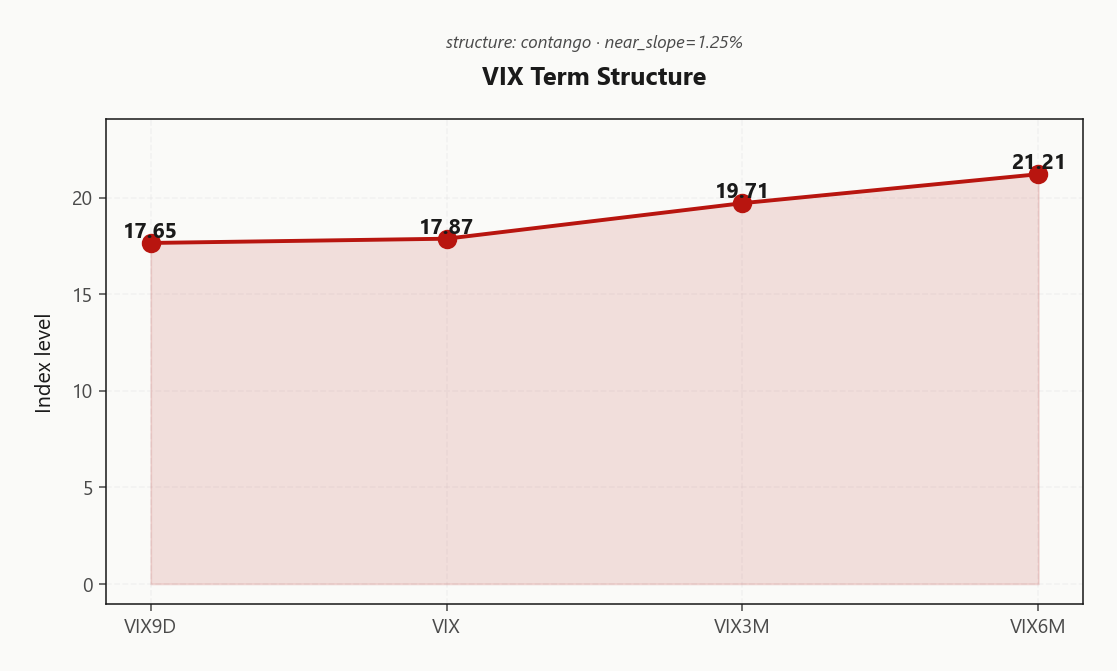
17.65 / 17.87 / 19.71 / 21.21
Steep contango
VVIX / VIX
5.72
Normal
Regime
Elevated / Watchful
Regime Assessment
Current regime prints Elevated / Watchful with VIX anchored at 17.98 - the classification that sits between benign carry and defensive posture. Signal color Yellow is the operative frame: this is a state to respect, not one that demands panic hedges or forced deleveraging. The vol pop is real, the regime shift is real, but the tape is not broken.
Transition probabilities are the tell. Escalation to panic over the next five sessions runs only 0.05 - structurally low, and consistent with contango intact and MOVE muted. Mean-reversion to a low-vol regime over ten sessions prices at 0.45, a meaningful pull toward normalization. The path of least resistance is drift-lower in vol, not another leg higher.
Half-life of 15 sessions is the sizing anchor - plan positions on a two-to-three-week horizon, not a one-day fade. Sticky enough to keep VRP rich, transient enough that the iron condor at 30-45 DTE captures the roll-down before the regime unwinds. Watchful, not defensive.
What it means for your trading
Regime is Elevated / Watchful - sticky at a 15-session half-life but with only 0.05 panic-escalation odds, so the correct posture is defined-risk premium harvest sized for a two-to-three-week window, not tail-hedge accumulation.
Trading readVIX and VVIX popping in unison but MOVE flat and SKEW steady = an equity-vol-only event, no cross-asset regime signal yet - divergences to watch are MOVE rising or SKEW spiking further.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve holds Contango despite today's spot pop - Steep contango - vol sellers favored. VIX9d at 17.65 sits below spot 17.87, three-month 19.71, and six-month 21.21 - a clean monotonic upward stack with the front slope pinned at 1.25%%. The curve refused to invert on the shock, and that refusal is the trade.
Forward 30-to-60 implied prints at 20.5683664884, opening a premium expansion window where roll-down still compensates the seller. The best-priced forward vol lives in the 30-45 DTE bucket - short enough to harvest steep decay, long enough to escape the front-end kink where the spot pop polluted pricing. Regime signal: Steep Contango, vol sellers favored.
The tell is what didn't happen: no backwardation flip, no term inversion, no panic bid across the belly. That is the geometry of a mean-reverting event, not a regime break - a spike being priced, not a repricing being installed.
What it means for your trading
Curve stayed Contango through the pop with forward 30-to-60 at 20.5683664884 - sell 30-45 DTE where roll-down is steepest and the front-end noise is behind you.
Trading readEven with today's spot VIX pop the curve holds Contango - the term structure is calling this a spike, not a regime break, keeping the vol-carry trade thesis intact.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV sits at 15.27% against 20-day realized of 8.56 - a 6.71% vol-point premium that is structurally rich by any historical measure. Options are pricing today's shock into forward realized, but the tape hasn't delivered the moves to justify it. Sellers get paid handsomely here, provided the risk is defined.
The tell is the term of realized itself: HV60 at 11.75 sits above HV20 at 8.56, meaning actual volatility is decelerating even as IV reprices the intraday vol pop. That's the classic setup where implied overshoots and mean-reverts into the seller - the VRP isn't a warning, it's an invitation.
Cross-asset the premium is even richer down the cap stack - IWM VRP 10% and QQQ VRP 7.96% - but small-cap liquidity punishes the harvest. SPY is the sweet spot: rich premium, deep books, and defined-risk structures let you monetize the VVIX pop without wearing it.
What it means for your trading
VRP of 6.71% vol points with realized decelerating is a premium-seller's regime - but the VVIX pop mandates defined-risk expression, not naked shorts.
Skew Convexity
The 25-delta skew sits at 3.36% vol points with a smile ratio of 1.19% - put wing bid at 21.18% against ATM 18.81% and calls left flat at 17.82%. This is ordered left-tail demand, not capitulation - institutions rolling protection, not chasing it.
The asymmetry matters: put IV carries a clean premium to calls, meaning the downside wing is overpriced relative to upside optionality. Naked long puts pay a steep tax to the skew; put spreads finance the same directional view at a fraction of the theta bleed. Call skew flat confirms zero conviction being paid for upside - no one is reaching for gamma above spot, which caps any convexity-driven melt-up.
SKEW index at 149.25 corroborates: institutional tail hedging is steady, not spiking. This is a structural premium environment, not a panic bid. Sell the wing via defined-risk structures - put spreads over outrights, condors over strangles - and let the skew work for you rather than against you.
What it means for your trading
Steep-but-ordered put skew at 3.36% vol points with SKEW at 149.25 - the wing is overpriced relative to calls, favoring put spreads over naked puts and defined-risk premium sale over long-vol structures.
Vol-of-Vol Structure
VVIX prints 102.88 up 8.87%% against VIX at 17.98 - a ratio of 5.72 that reads Normal on absolute level, but the rate of change is what matters here. Vol-of-vol is expanding materially faster than vol itself, and that gap is the market's way of paying up for optionality on the next move in VIX rather than the level of VIX today.
Translation: jump risk is being repriced without an outright panic bid. The convexity buyers are active, the outright hedgers are not - yet. Skew steepening in the underlying corroborates the signal: tail demand is ordered, not indiscriminate.
Sizing guidance is Standard Size - the ratio hasn't broken into stress territory, so the premium-harvest thesis stands. But there is no case for leveraging up. VVIX leading VIX is the classic pre-shock tell; respect it by keeping wings defined and gross exposure at book-standard until the ratio compresses.
What it means for your trading
VVIX/VIX at 5.72 sits at Normal levels but is trending higher - sizing stays Standard Size, no leverage-up, keep structures defined-risk until vol-of-vol cools.
Dispersion Spread
Index vol prints a clean dispersion ladder: SPY ATM at 15.27%, QQQ at 20.93%, IWM at 22.93%. Small-caps carry the fattest premium as expected - the risk is real, but IWM chain liquidity punishes anyone trying to harvest that premium at size. QQQ sits in the middle, tech beta bleeding into the index vol pop without offering enough width over SPY to justify the concentration risk in a negative-gamma tape.
SPY is the sweet spot. VRP at 6.71% vol points is rich, chain depth is institutional-grade, and defined-risk structures around the 755.00 / 770.00 rails clear the microstructure hurdle IWM can't. Prefer index-level vol selling here to capture the correlation floor - when VIX pops and cross-asset tone reads Aligned, single-name dispersion edge collapses because everything moves together.
Skip the single-name overwrite/short-strangle book until correlation rolls back off. Idiosyncratic vol premium requires idiosyncratic movement; you don't get paid for name-level risk when the index is the trade.
What it means for your trading
Dispersion ladder is clean but the play is index-level: sell SPY VRP with defined-risk wings, skip IWM on liquidity and single-name on correlation. When the index is doing the moving, single-name dispersion is a dry well.
Liquidity & Microstructure
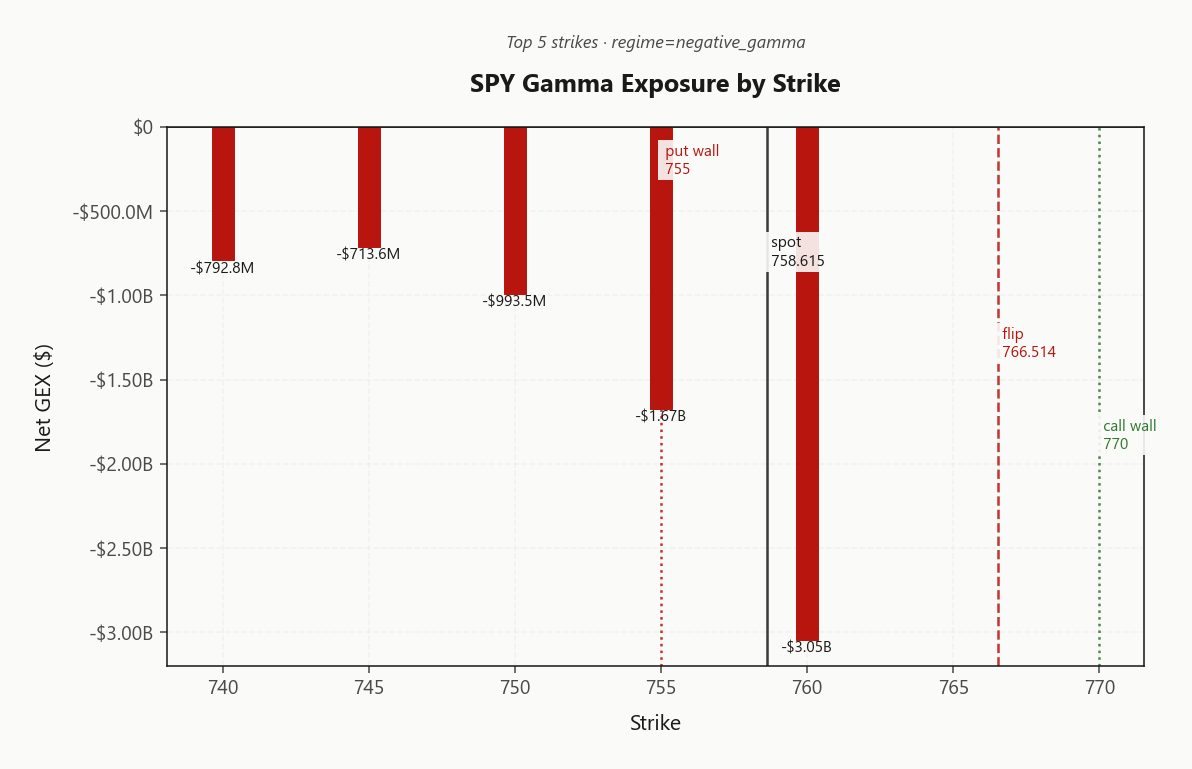
The book pins around 760.00, where total OI stacks to 370078 and net GEX sits at -$3.05B - this is the amplification node, not a support shelf. With spot printing below the gamma flip at 766.51, dealers are hedging into weakness at that strike rather than against it, which is why intraday drift keeps returning to the pin and then leaking lower on any push.
The 770.00 call wall is the ceiling on any relief bounce - dealer short-gamma above thickens fast and caps upside momentum. Below, the 755.00 put wall is the next acceleration line: a clean break there uncorks a second layer of dealer selling and the tape stops behaving orderly. The 525 OI anchor is LEAP-territory noise and carries no intraday signal.
Everything routes through 766.51. Reclaim it and dealer flow flips supportive, gamma turns constructive, and the mean-reversion setup activates. Fail it and the 755.00 magnet takes over.
What it means for your trading
Structure the wings of the Iron Condor around 755.00 and 770.00 - those are the dealer-defended rails. 766.51 is the single line that flips the regime; trade posture pivots there, not at the pin.
Trading readNegative gamma stacked at 760.00 and below means dealers amplify weakness on any push toward the put wall - fade rallies into 770.00, respect that 755.00 is a magnet-and-flush zone if breached.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Charm layers on top: Time decay pushing dealers to sell - pressure into close. Time decay through the session drags dealer delta lower into the close, so the vanna accelerant and charm bleed are firing in the same direction. There is no offsetting greek here - this is a clean, unambiguous sell-side alignment, not a noisy mixed signal.
The pivot sits at 758 with spot only -0.0810687898% away, so tape bias reads Neutral - coiled, not committed. Reclaim the pivot and the charm/vanna pressure eases into pin behavior; lose it and both greeks accelerate the flush toward 755.00. Trade the pivot, not the middle.
What it means for your trading
Vanna and charm both hostile with net VEX -$64.51B and net CHEX -$820.2K - vol-up amplifies downside, time-decay drags dealers to sell into close. Pivot 758 is THE line: bias Neutral until it's reclaimed or lost.
Cross-Asset Confirmation
MOVE sits at 76.74 - rate vol is not confirming the equity vol pop. Bond desks are pricing this as an equity positioning event, not a credit-cycle inflection. That divergence is the single most important tell on the tape: when SPX vol spikes without MOVE, the historical playbook is mean-reversion, not contagion.
Fear/Greed prints 35 in Fear territory - sentiment is already defensive going in, which caps the incremental de-risking flow that typically fuels a second-leg flush. QQQ at 709.03 and IWM at 287.86 are both trading below their respective flip levels, so the equity complex is uniformly hostile - no index is acting as a release valve.
Cross-asset tone reads Unknown with regime direction Aligned. Aligned equity weakness plus a quiet bond tape is the textbook mean-reverting setup - sell defined-risk premium, do not chase tail hedges here.
What it means for your trading
Equity-only vol event: MOVE at 76.74 stays muted while SPY/QQQ/IWM align below their flips and Fear/Greed reads Fear - no credit contagion, high probability of mean-reversion, defined-risk premium sale is the trade.
Scenario EV
Scoring resolves cleanly this session: Iron Condor tops the ledger at 60 across the 30-45 DTE window, with the put spread trailing at 55. VRP reads Unknown but the premium is unambiguously there - sold richly against a decelerating realized tape - and VVIX at 102.88 is elevated without tipping bimodal, exactly the regime where defined-risk beats naked strangles on risk-adjusted terms.
Structure the wings around the dealer rails: short puts anchored near 755.00, short calls capped at 770.00, letting the gamma flip at 766.51 do the pinning work. Long protective legs finance the vega exposure and cap the tail - critical while Normal vol-of-vol still trends up. The put spread at 55 is the directional alt if conviction skews bearish, but the neutral condor captures both sides of the mean-reversion setup the term structure is telegraphing.
Sizing stays Standard Size. Skip naked strangles into the VVIX pop, skip calendars where the steep skew punishes the long-vol leg - the edge is defined, symmetric, and paid.
What it means for your trading
Iron condor at 30-45 DTE scoring 60 is the defined-risk VRP harvest of choice - wings pinned to 755.00 / 770.00, size Standard Size, no naked shorts while VVIX trends.
Actionable Summary
Trade:Iron Condor at 30-45 DTE, short strikes anchored to the 755.00 put wall and 770.00 call wall. VRP is rich, VVIX is elevated but not extreme, and defined-risk beats the naked strangle by a wide margin here.
Watch: gamma flip at 766.51 is THE line - reclaim flips dealer flow supportive and green-lights risk-on; a clean break lower opens the flush toward 755.00. Avoid naked strangles with VVIX up 8.87%% and long-vol calendars where the steep put skew punishes the long leg.
SizeStandard Size - do not lever into expanding vol-of-vol. Regime reads Elevated / Watchful with a half-life of 15 sessions; plan the book on a two-week horizon, not an intraday one. Charm pivot at 758 keeps bias neutral until the flip resolves.
What it means for your trading
Sell defined-risk premium around the 755.00/770.00 rails at 30-45 DTE, size Standard Size, and treat 766.51 as the binary trigger between mean-reversion and flush. Regime is Elevated / Watchful - watchful, not defensive.
ECB hike into an Iran-war inflation backdrop is a global monetary tightening confirmation - supports MOVE floor and puts a lid on any dovish pivot rally.
Oracle options positioning into earnings is a real single-name AI-trade tell - dispersion signal for the mega-cap complex.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 17.84 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 766.51 against a spot of 758.62. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 15.27% with a volatility risk premium of 6.71%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 17.98. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime