Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed at 765.80, sitting below the 770.62 gamma flip with net GEX at -$5.95B - dealers are short gamma and every move gets amplified. Key levels: call wall at 770.00 caps rallies, put wall at 760.00 is where dealer selling would accelerate, and 770.62 is the line that flips the tape from trend to mean-revert. Dealer positioning is hostile - vanna at -$131.21B means a vol spike forces more delta selling, and charm (-$1.3M) adds pressure into the close. Vol read: VIX at 15.69 with a Steep contango - vol sellers favored term structure and VVIX at 88.57 - front-end vol is bid but the curve says no regime break. VRP at 2.58% with contango carry favors Iron Condor in the 30-45 DTE window. Bottom line: fade extension into 770.00, respect 760.00 as the acceleration zone, and sell premium into the contango - don't chase direction below the flip.
SPY at 765.80 closed below the 770.62 flip with dealers short gamma across the index complex, meaning today's downside was mechanically amplified. Yet forward vol geometry (Steep contango - vol sellers favored) and a benign VVIX at 88.57 say the market isn't pricing a break - just paying up for near-term hedges. The tension: negative gamma below, contango above, Fear sentiment - a setup that rewards patient premium sellers, not directional chasers.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
765.80
770.62
-0.63%
770
760
760
-$5.95B
Short gamma
QQQ
717.98
718.44
-0.06%
730
700
708
-$1.05B
Short gamma
IWM
294.74
297.87
-1.05%
300
290
290
-$2.72B
Short gamma
VIX
15.73
16.25
-3.19%
20
15
19.50
-$33.03M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.82
8.24
+2.58
2.98
2.65
1.24
QQQ
16.55
12.83
+3.72
4.36
1.41
1.37
IWM
16.02
12.08
+3.94
1.89
2.41
1.75
VIX
77.85
79.69
-1.84
-101.37
0.37
0.32
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
15.69
+7.98%
VVIX
88.57
+4.92%
SPX
7,673.52
-0.58%
SKEW index
151.58
0.00%
MOVE (bond vol)
73.10
0.00%
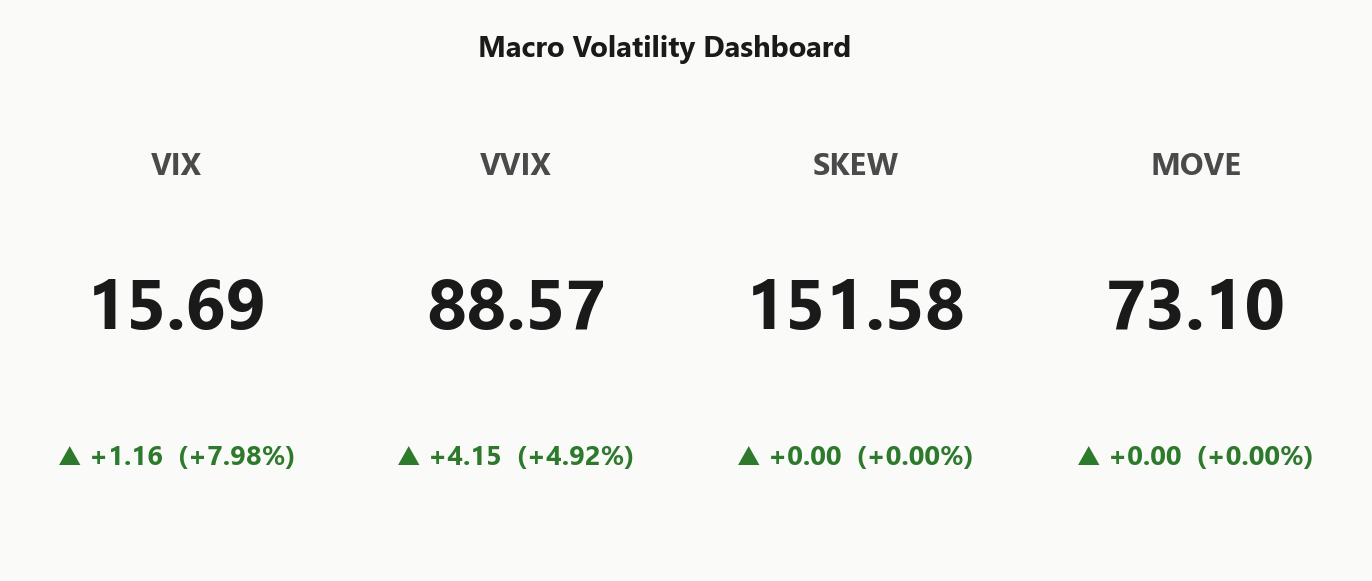
VIX term (9d/30d/3m/6m)
14.40 / 15.47 / 18.29 / 20.30
Steep contango
VVIX / VIX
5.64
Low
Regime
Elevated / Watchful
Regime Assessment
Regime read: Elevated / Watchful with VIX anchored at 15.69. The transition matrix does the talking - probability of escalation to panic over the next five sessions sits at 0.05, while the ten-session path back to a low-vol state carries 0.45. The base case is normalization, not escalation.
Stickiness is the operative word. Half-life of 15 sessions means this Elevated state fades slowly - long enough to pay patient premium sellers, short enough that reactive traders get chopped up trying to time each intraday flare. Anchor exposure to the regime, not to the tape.
Playbook: carry short vol into the contango, size to the mean-revert scenario, and treat any VVIX regime shift as the trigger to cut. The math favors sitting still.
What it means for your trading
Regime is Elevated / Watchful with a 15-session half-life - the base case is drift back to low vol, not escalation, and patient carry beats reactive trading here.
Trading readVIX bid, VVIX quiet, MOVE quiet, SKEW elevated - vol of vol and rates vol are NOT confirming the equity vol move. That's the classic setup where the equity vol pop mean-reverts quickly rather than escalating into a genuine regime break.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
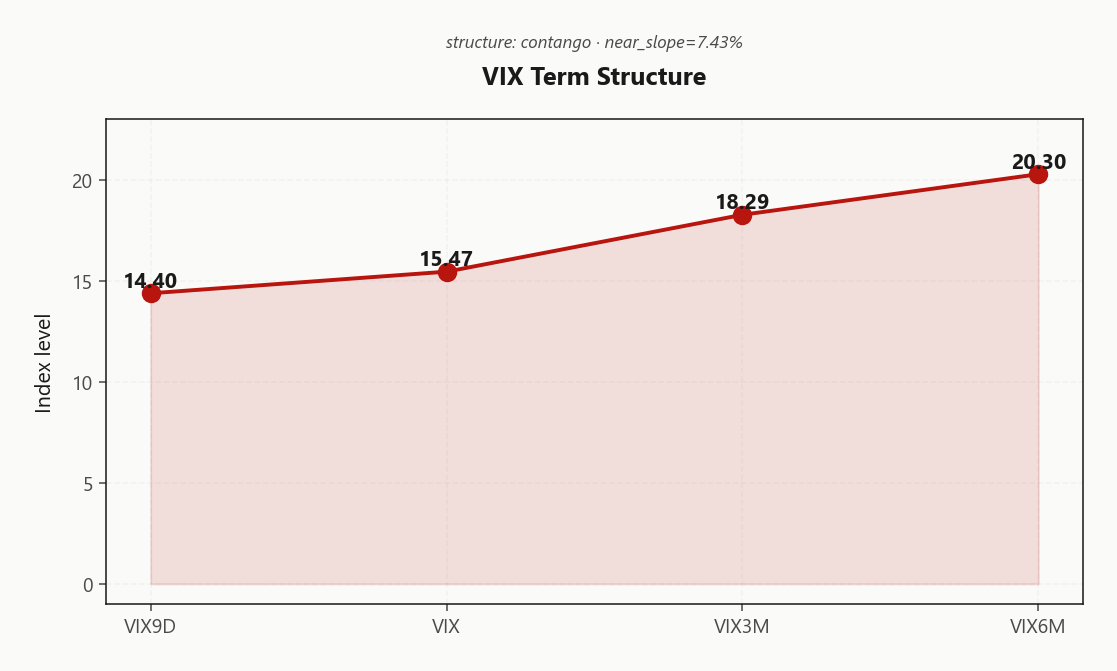
The vol curve is doing the talking: 14.40 at the front, 15.47 spot, 18.29 at three months, and 20.30 at six - textbook Contango, no panic bid. The near-slope prints at 7.43%%, the kind of structural pitch that pays systematic sellers to sit and collect roll-down while the back end quietly discounts a normalization the front hasn't earned yet.
Forward vol geometry reads Steep contango - vol sellers favored. The 30-to-60 forward sits meaningfully above spot VIX - the market is pre-paying for a vol path it doesn't actually expect to realize, which is exactly the mispricing carry harvesters exist to monetize.
Trade the curve, not against it: concentrate short-vol risk in the 30-45 DTE window where the slope is steepest and roll is richest. Front-week is too twitchy given negative gamma below; beyond sixty the curve is already fat and the edge decays. Signal: Steep Contango - sellers favored, but respect the geometry.
What it means for your trading
Curve shape is Steep contango - vol sellers favored with near-slope at 7.43%% - the paid trade is short front-vol in the 30-45 DTE bucket, sized around the curve rather than fighting it.
Trading readSteep contango - vol sellers favored - the vol carry trade is alive and paying, but the front-end steepness means near-dated selling gets the best carry-to-risk ratio. Roll systematically, don't over-tenor.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied at 10.82% against 20-day realized of 8.24 leaves a live premium on the table - the VRP prints 2.58% and that is a statistical edge, not a narrative one. Combined with the Steep contango - vol sellers favored curve behind it, this is precisely the geometry systematic vol harvesters wait for: rich front-end options, benign realized, and roll-down carry paying you to stay short.
The nuance sits at the back of the tape: 60-day realized at 12.17 prints above ATM implied, meaning the market has already forgotten the last stress episode and is pricing forward vol below what recently occurred. That is asymmetric - tail hedges are cheap enough to carry as a byproduct of the primary short-premium book, not as a competing trade.
Structure preference: the IV-to-RV spread underwrites iron condors and defined-risk short strangles in the belly, financed by the VRP. Long premium loses the carry fight here; keep optionality only where the curve is giving it to you for free.
What it means for your trading
With ATM IV at 10.82% rich to HV20 at 8.24 and VRP printing 2.58%, the edge is short-premium defined-risk in the belly - while HV60 above IV makes tail hedges a cheap byproduct worth carrying.
Skew Convexity
Quarter-delta put skew sits at 2.98% vol points with a smile ratio of 1.29% - the downside tail is bid but ordered, not the panic-steepened footprint you'd expect if real fear were loading. Put wing prints 13.22% against ATM at 11.38%, a healthy premium but not a capitulation bid.
The tell is the call wing at 10.24% - flat to inverted versus ATM. Nobody is hoarding upside convexity, which is textbook for a tape trading below the flip with Elevated / Watchful sentiment. When call skew crushes like this, the right-tail is effectively on sale relative to the left.
Structure that: finance downside via risk reversals, buying put spreads and selling the crushed call wing to cheapen the hedge. Naked puts overpay for the ordered skew; the risk reversal harvests the asymmetry directly. Layer inside the 30-45 DTE window where curve carry stacks with the skew edge.
What it means for your trading
Put skew at 2.98% vol points with smile ratio 1.29% shows an ordered bid for downside, not panic - and a flat call wing at 10.24% makes risk reversals the cost-efficient way to own protection.
Vol-of-Vol Structure
VVIX at 88.57 is sitting on the low side of its distribution and the VVIX/VIX ratio at 5.64 parks squarely in benign territory - the market is not pricing a bimodal outcome. No jump premium is being paid, no fat right tail is being hoarded, and the vol-of-vol tape confirms a Low regime. That's the green light we wait for before leaning into short vol structures at full weight.
Sizing guidance follows the read: Standard Size - no need to shave, no need to hedge convexity of convexity. The reflex to cut risk when spot VIX pops higher gets the trade wrong here; without VVIX confirming, the vol move is a positioning event, not a regime break. Iron condors and defined-risk premium sellers carry standard notional into the contango.
The one caveat: VVIX moved 4.92% today, so the tape is not static. Line in the sand is a VVIX print above 110 - cross that and cut size in half immediately, no debate. Below it, the carry trade runs with full risk.
What it means for your trading
VVIX at 88.57 and a VVIX/VIX ratio of 5.64 confirm a Low vol-of-vol regime - Standard Size on short vol structures, with a hard cut above 110 VVIX.
Dispersion Spread
Index vol screens modestly rich to realized with SPY ATM IV at 10.82% versus QQQ at 16.55% - correlation is elevated enough that the classic dispersion trade (long single-name vol, short index vol) is not the edge today. The complex is Aligned in negative gamma, which mechanically compresses single-name dispersion as macro flow dominates idiosyncratic price action.
The venue call is straightforward: sell index vol, not single-names. Index premium is where the reliable carry sits when the correlation regime is up - SPY and SPX offer the deepest books, tightest spreads, and the cleanest VRP to harvest. If a concentrated single-name book needs coverage, buy protection at the name level and finance it by selling the correlated index vol, not the other way around.
Long-single-name / short-index setups get punished in this regime - the correlation grind means the short-index leg pays out too little to offset gamma bleed on the longs. Stay at the index level for premium collection and use single-name hedges surgically.
What it means for your trading
Elevated correlation with SPY ATM IV at 10.82% and QQQ at 16.55% kills the dispersion edge - sell index vol, hedge single-names only where concentrated exposure demands it.
Liquidity & Microstructure
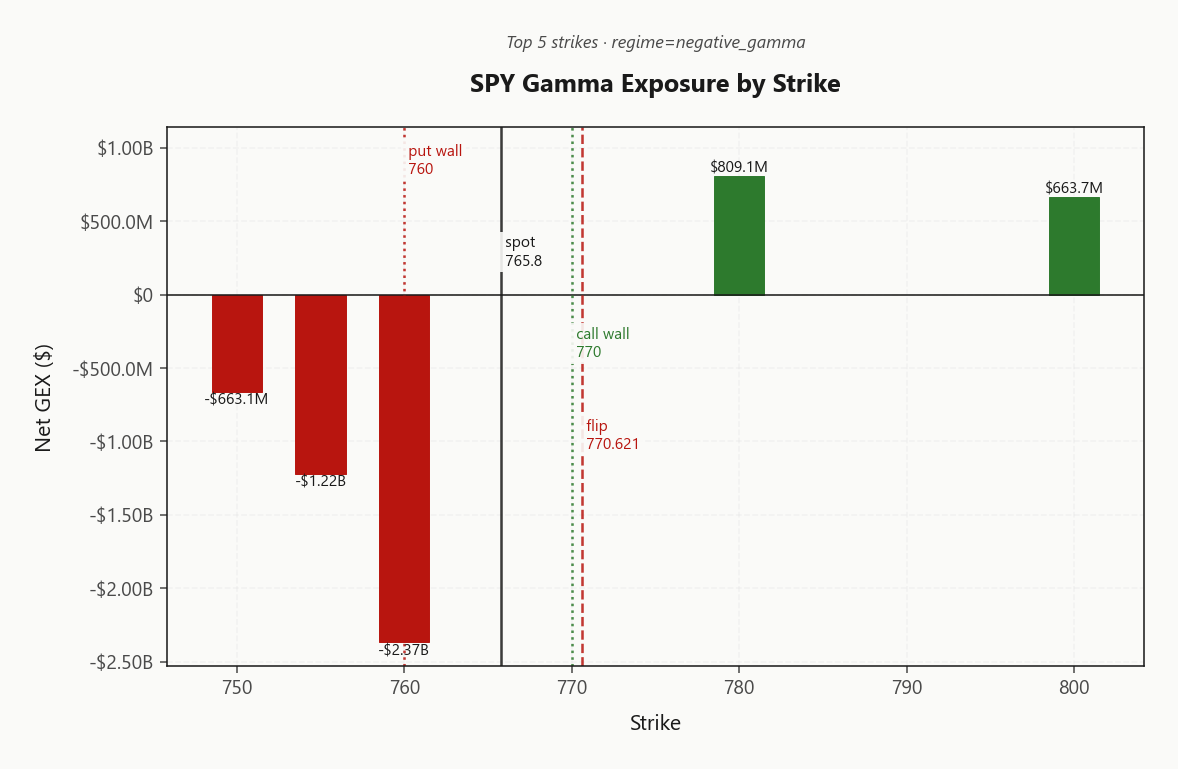
The 525 open-interest peak is a stale artifact - ignore it. The live map runs off the 770.62 gamma flip, and with spot at 765.80 sitting 0.5484460695% away, dealer flow is in amplify mode below and suppress mode above. That single level dictates whether today's tape trends or reverts.
Overhead, the 770.00 call wall acts as a magnet ceiling - rallies into it get sold as dealers hedge sticky short-call inventory. Underneath, the 760.00 put wall is the trap door: a print through it unlocks accelerated dealer selling into an already-negative-gamma book. The heaviest gamma pocket sits at 760.00 carrying -$2.37B of net GEX - that strike is the microstructure.
Playbook: fade extensions into 770.00, respect 760.00 as the acceleration zone, and treat any reclaim of 770.62 as the regime pivot - not a level to lean against, but the line that flips the mechanics.
What it means for your trading
The 770.62 flip is the only level that matters - spot below it means moves amplify, with the 770.00/760.00 corridor bracketing the actionable range.
Trading readThe gamma landscape sits below the flip with the biggest short-gamma pockets clustered near 760.00 - every downside tick between here and there gets mechanically amplified, while the 770.00 call wall caps any relief rally. Trade the range, don't chase either edge.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits at -$131.21B - deeply negative and the mechanical accelerant nobody's pricing. A VIX pop from here forces dealers to sell delta into the move, compounding any drawdown before discretionary flow even has time to react. This is the hostile geometry: 15.69 firming while the book is structurally short vanna means every vol tick translates directly into supply.
Charm at -$1.3M layers a second bleed on top - dealer support decays each session toward expiry, and with spot below the flip that decay works against the tape rather than pinning it. The one level that matters is 770, the Call Wall: reclaim it and vanna flips from accelerant to cushion; hold below and flows compound the pain into the close.
Current bias reads Neutral - coiled but not committed. Trade the pivot, not the narrative.
What it means for your trading
Vanna and charm are aligned against the tape below 770 - a VIX spike here forces mechanical delta selling, and only reclaim of the Call Wall reverses the reflex.
Cross-Asset Confirmation
Cross-asset tape reads Unknown with the index complex in lockstep - SPY, QQQ at 717.98, and IWM at 294.74 all sitting in negative gamma. This is broad-based equity de-risking, not an isolated tech unwind or a small-cap flush. When the whole complex ticks short-gamma together, hedges concentrate rather than diversify - the diversification bid you'd normally lean on isn't there.
Yet the confirmation stops at equities. MOVE at 73.10 is quiet - rates vol isn't corroborating the equity fragility, and there's no credit contagion channel opening up. Fear & Greed prints Fear at a score of 41 - cautious tilt, not capitulation. The absence of a bond bid is the tell: this is a positioning story, not a macro shock.
Regime divergence direction reads Aligned. Trade it as coordinated dealer reflex to be faded on stabilization, not the front edge of a genuine risk-off cascade.
What it means for your trading
Equity complex is uniformly short gamma but MOVE at 73.10 and a merely Fear F&G reading say this is positioning fragility, not macro stress - fade the equity vol pop rather than chase it.
The scorecard is unambiguous: iron condor ranks 44 against the put spread at 35 - the four-legged structure captures both wings of the VRP and monetizes the flat call skew rather than paying up for one-sided directional carry. Anchor the short call side into 770.00 and the short put side above 760.00.
Skip naked strangles. With net vanna at -$131.21B a VIX pop forces dealer delta selling that compounds into any unhedged short tail - the defined-risk structure is the only way to collect the 2.58% edge without wearing the amplification risk.
What it means for your trading
Sell the Iron Condor in 30-45 DTE - the scorecard prints 44 vs 35 for the put spread, and VVIX at 88.57 supports Standard Size. Wings only - vanna at -$131.21B makes undefined tails a non-starter.
Actionable Summary
Trade the setup, not the tape. Structure of choice is an Iron Condor in the 30-45 DTE window - VRP is live at 2.58%, VVIX at 88.57 greenlights standard sizing, and the Steep contango - vol sellers favored pays you to roll. Skip naked strangles; vanna at -$131.21B would punish an undefined tail.
The pivot is 770 (Call Wall). Reclaim it and vanna hostility reverses into support; stay below and charm compounds the bleed toward 760.00. Above the flip at 770.62 flow dampens, below it flow accelerates - trade the range, don't chase the edge.
Regime: Elevated / Watchful with a 15-session half-life - normalization is the base case, patient carry wins. Kill switch: VVIX printing through the mid-triple-digits cuts size in half immediately. Fade extension into 770.00, respect the put wall as the acceleration zone, harvest the contango.
What it means for your trading
Sell defined-risk premium in the 30-45 DTE bucket around the 770 pivot - Elevated / Watchful regime rewards patient carry, not directional chasing.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.73 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 770.62 against a spot of 765.80. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.82% with a volatility risk premium of 2.58%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.69. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime