Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 772.15 sitting a whisker below gamma flip at 772.56 - technically negative gamma regime with net GEX $1.51B, meaning any push through the flip flips dealer flow from amplifying to dampening. Call wall 775.00, put wall 770.00, max pain 760.00 - tight cluster keeps spot magnetized to this zone. Dealer net vanna at -$193.04B is deeply negative: a vol spike would force accelerant selling, but charm at $694.8K is mildly supportive into the close. VIX at 14.14, VVIX at 82.64, term structure Contango with near-slope 20.12%% - carry trade fully paid, VRP at 1.63%. MOVE at 74.68 and cross-asset regime Low / Carry say no macro stress despite hot jobs print. Zero-DTE captures 35.4%% of gamma - intraday chop concentrated near the flip. Bottom line: sell Iron Condor in the 30-45 DTE window, avoid naked exposure through 772.56.
Steep VIX contango with SPY pinned at gamma flip - carry regime intact but destabilizing pivot
SPY is pinned within a whisper of its gamma flip at 772.56, forcing dealers into the destabilizing zone even as VIX at 14.14 and steep VIX9D-to-VIX3M contango argue for structural vol carry. Cross-asset confirms low-stress regime - VVIX at 82.64, MOVE at 74.68 - but hot payrolls have pushed 2Y yields to cycle highs and Fear & Greed still reads Fear. Iron condors in the 30-45 DTE bucket capture VRP without touching the fragile flip zone.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
772.15
772.56
-0.05%
775
770
760
$1.51B
Short gamma
QQQ
720.07
720.10
0.00%
725
700
705
$2.38B
Short gamma
IWM
294.78
297.04
-0.76%
300
290
290
-$3.62B
Short gamma
VIX
14.14
15.92
-11.16%
20
14
19.50
$39.89M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.62
7.99
+1.63
1.76
2.55
1.27
QQQ
14.29
12.93
+1.36
-95.82
1.37
1.00
IWM
14.22
12.11
+2.11
1.39
2.45
0.63
VIX
114.62
78.49
+36.13
-131.52
0.38
0.31
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
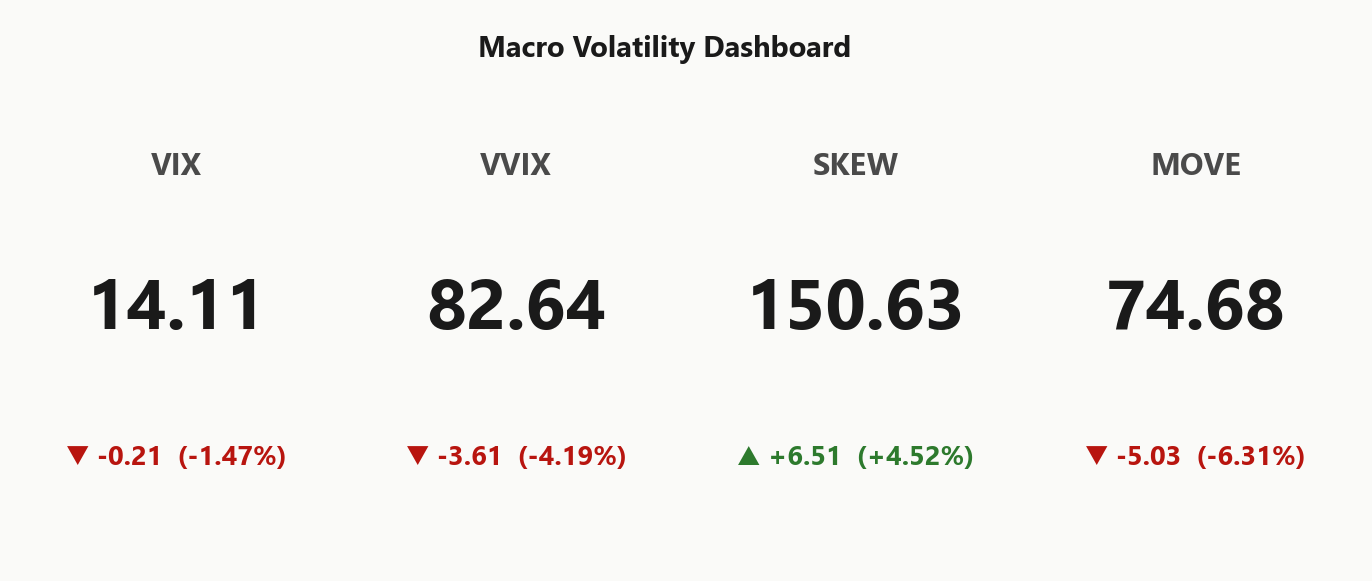
Volatility complex
Measure
Value
Change
VIX
14.11
-1.47%
VVIX
82.64
-4.19%
SPX
7,735.52
-0.16%
SKEW index
150.63
+4.52%
MOVE (bond vol)
74.68
-6.31%
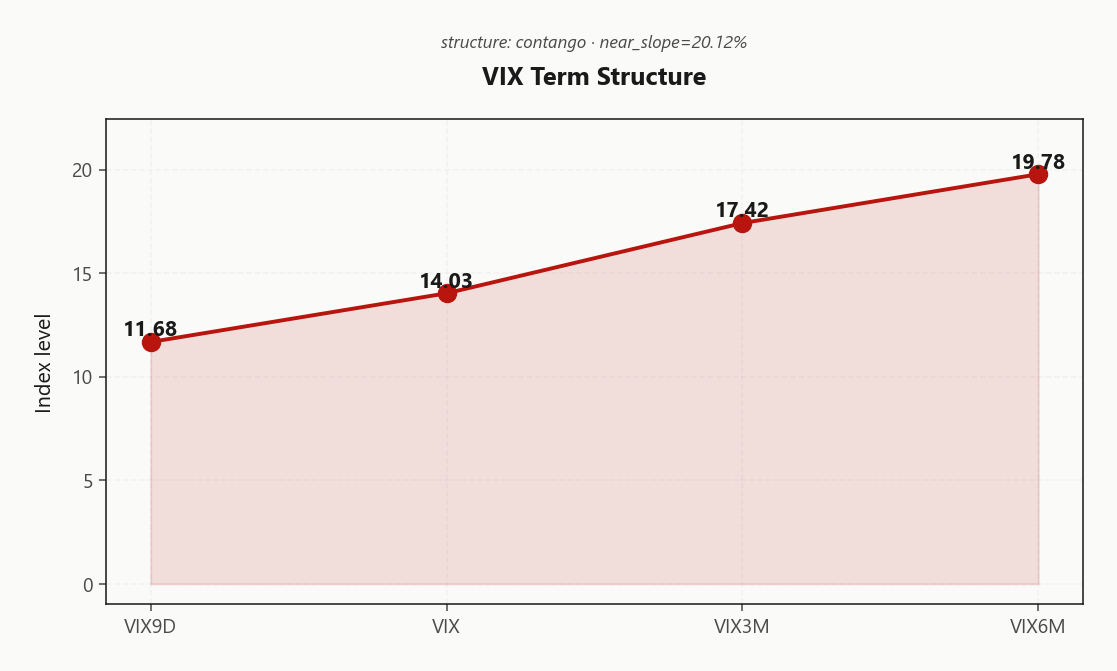
VIX term (9d/30d/3m/6m)
11.68 / 14.03 / 17.42 / 19.78
Steep contango
VVIX / VIX
5.86
Low
Regime
Low / Carry
Regime Assessment
Regime reads Low / Carry with VIX anchored at 14.11 - this is the payer's regime, and the half-life of 30 sessions says it doesn't flip on a whim. Base case: carry persists through the front expiries, and the section signal reads Low - green light for structured short-vol.
Transition math backs the stickiness: probability of a jump to panic over the next five sessions sits at 0.05, small but non-zero and worth respecting with defined-risk wings rather than naked exposure. The current regime label Low aligns with steep contango and benign VVIX - three independent reads pointing at the same trade.
Tactical read: don't front-run a regime change that the data isn't pricing. Sell the carry, keep the tails covered, and let half-life do the work.
What it means for your trading
Regime Low / Carry at VIX 14.11 with a 30-session half-life - carry structures get the green light, but the 0.05 panic-transition probability argues for defined-risk wings, not undefined-risk shorts.
Trading readVIX, VVIX, MOVE all easing while SKEW at 150.63 ticked up - divergence between the fear-of-a-crash gauge and the actual vol pricing tells you protection is being bought at the margin, but not paid up for. That's a quiet warning, not an alarm.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX complex is in Contango from front to back: VIX9D at 11.68 rolls up into spot VIX at 14.03 and out to VIX3M at 17.42, with the near-slope printing 20.12%%. That is a pristine carry curve - roll-down alone is paying before any vol crush shows up, and the regime tag Steep contango - vol sellers favored says the market is not paying up for front-end protection.
The belly is where the edge lives. Forward 30-to-60 implied at 18.8882013437% versus forward 60-to-90 at 21.8869915703% maps a clean upward glide into VIX6M at 19.78 - the market is telling you fair vol drifts higher only if nothing happens, which is exactly the shape short-dated carry structures monetize.
Trade the belly, not the wings. The scenario stack lands on Iron Condor in the 30-45 DTE bucket - long enough to shed weekend gamma, short enough to harvest theta before the curve reprices. No urgency to pay up for front-end hedges while contango holds this shape.
What it means for your trading
Steep VIX Contango with near-slope 20.12%% keeps the roll-down carry trade fully alive - sell the belly at 30-45 DTE, skip the front-end hedges.
Trading readTextbook contango with near-slope 20.12%% - the vol carry trade is fully paid, and roll-down alone delivers positive P&L before any vol crush. Only a shock steep enough to invert the curve breaks this trade.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV sits at 9.62% against 20-day realized at 7.99 - the surface is pricing meaningfully above what tape has actually delivered, and premium sellers are getting paid to show up. VRP prints 1.63%, a real cushion under short-vol structures before you even collect the roll-down leg of the trade.
The IV-RV assessment reads Thin Premium, corroborating the sell-vol thesis without needing a further vol crush to make the math work. Short-dated realized at N/A versus the 20-day at 7.99 shows the tape has already decelerated - you are not selling into a spike, you are selling into a fade.
Bottom line: options are richer than delivered vol, HV60 at 12.53 confirms recent realized has cooled from a hotter regime, and the tailwind for premium sellers extends into the next roll. Structure the short-vol book with defined wings past 775.00 and 770.00 - the VRP pays without demanding directional conviction.
What it means for your trading
IV at 9.62% against realized at 7.99 plus VRP of 1.63% makes this the cleanest short-vol setup in weeks - sell defined-risk structures, not naked exposure.
Skew Convexity
Quarter-delta skew prints at 1.76% with the put wing at 7.86% against calls at 6.1% - a clean, ordered bid for downside without the deep-wing convexity that would signal panic. ATM anchors at 7.31%, and the smile ratio at 1.29% tells you put-side conviction is doing all the work while upside conviction is functionally absent.
SKEW confirms the read at 150.63 - tail bid present, dislocation absent. Section signal reads Skew Steep: the surface is priced for a controlled drawdown, not a crash. Flat call skew means zero upside chase is embedded - rally expectations are capped in the paper itself.
Translation: sell the put wing as a spread, never naked. The premium is real but the shape argues for defined risk into the flip at 772.56. Call-side flatness makes upside condor wings cheap to layer on - asymmetric structure, asymmetric surface.
What it means for your trading
Skew is steep and ordered, not panicked - quarter-delta puts at 7.86% against calls at 6.1% with SKEW at 150.63 confirming tail bid without dislocation. Spread the puts, don't sell them naked.
Vol-of-Vol Structure
VVIX at 82.64 against VIX at 14.11 pins the vol-of-vol ratio at 5.86 - squarely in the Low bucket. The market is not paying up for bimodal outcomes, and the gamma-of-gamma surface shows no exotic bid. Jump risk is priced as tail noise, not as a scenario.
The day-over-day VVIX print at -4.19% confirms pressure is releasing, not accumulating - a clean tell that the convexity book is unwinding hedges rather than reloading them. Sub-cycle VVIX reads corroborate the steep contango regime and the active VRP: convexity sellers get paid without a jump premium overhang.
Sizing guidance reads Standard Size - no penalty box, no defensive halving. Deploy the recommended condor at full clip; the only gate is the flip pivot, not the vol-of-vol surface. Reserve tail wings, but do not pay up for gamma-of-gamma protection the tape isn't demanding.
What it means for your trading
VVIX at 82.64 and a 5.86 ratio put jump-risk pricing in the Low bucket - Standard Size is on the table with no convexity penalty.
Dispersion Spread
QQQ ATM IV at 14.29% sits meaningfully above SPY at 9.62% - single-name tech premium is doing the heavy lifting while the index itself trades cheap to its constituents. Cross-strike dispersion of 85.89 confirms the surface is bid where it counts, not at the index level. Correlation regime reads Moderate - enough co-movement to make index vol the cleaner short, not enough to make a correlation trade worth the friction.
IWM offers the richest carry of the complex with VRP at 2.11%, but SPY's tighter wall structure and deeper book make it the execution-friendly vehicle. QQQ's IV premium is information, not opportunity - that vol is priced for the single-name story, not the index tape.
Preferred expression: SPX/SPY iron condors in the 30-45 DTE window over single-name premium selling. The dispersion signal says the index is where the mispricing lives; harvest it there.
What it means for your trading
Index vol reads cheap to constituents with correlation at Moderate - sell SPY/SPX condors, not single-name premium. IWM carries the richest VRP at 2.11% for those willing to trade tighter book depth for fatter theta.
Liquidity & Microstructure
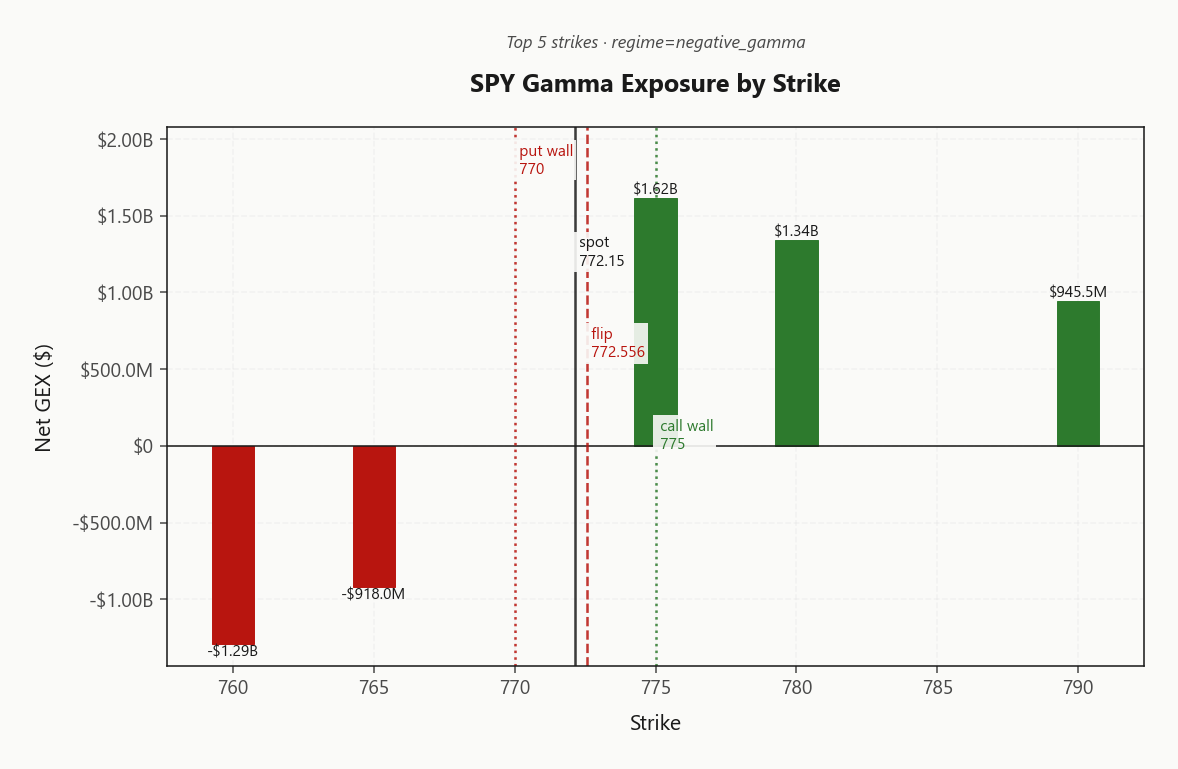
The tape today lives and dies at the gamma flip at 772.56, with spot at 772.15 sitting a whisker below it. Above flip, dealer hedging cushions rallies and mean-reverts weakness; below, dealer selling amplifies every leg down. The 775.00 call wall and 770.00 put wall bracket a punishingly tight zone - the top gamma cluster at 775.00 carries $1.62B of dealer defense, real size sitting on any rally attempt.
The highest OI strike at 525 is a legacy LEAPS cluster and does not magnetize today's tape - ignore it and trade the walls. Below the flip, the put wall at 770.00 is where dealer buying accelerates on retest, giving you a defined support shelf if the pivot fails.
0DTE captures 35.4% of net gamma - intraday whip risk is elevated straight through the pivot. Book depth reads deep: execution is not the problem, positioning through the flip is.
What it means for your trading
Trade the bracket between 770.00 and 775.00 with wings outside both walls; the flip at 772.56 is the line that separates mean-reversion from acceleration.
Trading readDealer gamma cluster at the call wall dampens rallies while the put wall below acts as a shock absorber - the 772.15 spot sitting between them means mean-reversion wins any move that stays inside the bracket. Break the flip at 772.56 and the amplification switch flips on.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna at -$193.04B is the fragility in an otherwise clean carry tape - vol-up mechanically forces delta-down, meaning any pop in 14.11 cascades directly into spot selling before macro even gets a chance to weigh in. The classic accelerant setup is armed.
Charm at $694.8K supplies a mild into-close bid from time decay - constructive, but nowhere near enough to offset a vanna cascade if VVIX at 82.64 wakes up. The pivot is the gamma flip at 772.5563595333: above it, vanna dampens; below it, it amplifies. Spot currently reads Destabilizing.
Vanna at -$193.04B is the loaded spring under a benign tape - the pivot at 772.5563595333 decides whether dealer flow dampens or accelerates the next move. Charm at $694.8K offers only a modest into-close cushion.
Cross-Asset Confirmation
Cross-asset tape is telling a coherent story: MOVE at 74.68 (-6.31%%) is leaking lower, meaning rates vol is releasing pressure even as equity vol carries a bid. That asymmetry is the fingerprint of an isolated equity uncertainty, not a credit event - if this were a systemic shock, MOVE would be leading vol higher, not fading.
Sentiment is where the divergence lives. Fear & Greed at 44 reads Fear while vol gauges chill - the classic setup for a contrarian bullish undertone. Positioning is defensive; pricing is not. That gap tends to close the constructive way when the flip zone holds.
Index breadth confirms: QQQ at 720.07 and IWM at 294.78 both sit in negative gamma alongside SPY - no divergence between the complex, no fragility hotspot to isolate. Cross-asset tone reads Unknown with regime divergence Aligned, which is a green light for carry structures rather than a signal to chase hedges.
What it means for your trading
Rates vol is easing while equity sentiment stays defensive - a benign macro backdrop dressed in cautious clothes, and the aligned Aligned regime across SPY, QQQ, and IWM removes any cross-asset excuse to fade the carry trade.
Scenario EV
Scenario EV screens Iron Condor at score 41, decisively ahead of the put-spread alternative at 29. With VRP at 1.63% paying, VVIX at 82.64 keeping jump-risk pricing Low, and the term structure in Contango with near-slope 20.12%, the condor harvests theta from both wings without demanding a directional call.
Optimal window is the 30-45 DTE bucket — long enough to shed this week’s flip-zone chop and weekend gamma, short enough to lock in roll-down before the belly compresses. Wings should sit outside the call wall at 775.00 and the put wall at 770.00, bracketing the magnetized zone rather than fighting it. Sizing is Standard Size per the VVIX read — no defensive haircut warranted.
Put-spread only earns a look if you have real directional conviction into the pivot at 772.5563595333; absent that, the condor is the cleaner neutral premium play with the regime tailwind fully aligned.
What it means for your trading
Sell the Iron Condor in the 30-45 DTE bucket with wings outside 775.00 and 770.00 — VRP, contango, and VVIX all green-light the carry, and standard sizing applies.
Actionable Summary
Bottom line: sell the Iron Condor in the 30-45 DTE window, wings parked outside call wall 775.00 and put wall 770.00. Regime reads Low / Carry with forward vol geometry Steep Contango - two green lights confirming the carry trade is fully paid, VRP at 1.63% and VVIX bucket Low both cosign standard sizing.
Level to watch: the gamma flip at 772.5563595333 - spot bias is currently Destabilizing, meaning a decisive break lower flips dealer flow from dampener to accelerant and reignites the negative vanna feedback loop from -$193.04B. Avoid naked short-vol spanning the pivot and any 0DTE positioning that ignores the 35.4% concentration hugging the flip zone.
Hedge note: jump-risk pricing is benign, so no need to overpay for tails - but keep the condor's wings intact rather than legging into naked strangles. This is a paid-to-wait regime with one pivot to respect.
Hot payrolls pushing 2Y yields to a cycle high resets the near-term Fed path and directly tests whether the current low-vol carry regime absorbs the rates shock or breaks.
Confirms the read that today's tape is bond-yield-led - equity dip is not organic, it's rates-driven, which matters for how vanna feedback loops behave.
Diesel at record highs on Ukraine and Iran refinery strikes plants an inflation seed that feeds directly back into the Fed-hike thesis driving yields today.
Oil rallying alongside diesel means the energy complex is quietly repricing supply risk - a slow-burn stagflation input that argues against selling long-dated vol.
Retail-favorite options frenzy into a historically weak month is a contrarian tell - supports the read that VVIX at 82.64 is understating jump risk in single names, not indices.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.14 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 772.56 against a spot of 772.15. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.62% with a volatility risk premium of 1.63%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.11. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime