Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 770.67 is in negative gamma with net GEX at -$2.2B - dealers short, moves amplified inside the 770.00 - 772.00 bracket. Gamma flip sits at 771.59, meaning spot is fractionally below the pivot; a reclaim flips dealer flow supportive, a break of 770.00 accelerates lower via vanna. Call wall at 772.00 caps rallies; put wall at 770.00 is the immediate battleground. 0DTE contributes 83%% of total gamma - expect intraday chop that resolves at the pin. VIX at 14.02 with steep contango to 17.24 and VVIX subdued at 82.24 - the vol complex is priced for carry, not crisis. VRP at 1.3% vol points confirms options are rich to realized. Bottom line: iron condor in the 30-45 DTE window, wings outside the wall pair, half-size only if spot breaks 770.00 on volume.
Short-gamma SPY at 770.67 sits fractionally below flip; VIX contango and low VVIX favor premium sellers
SPY sits fractionally under gamma flip at 771.59 with short-dealer positioning across the index complex, yet VIX at 14.02 and steep contango out to 17.24 say the macro regime remains carry-friendly. VVIX at 82.24 confirms no jump premium is being paid, so the tape is choppy-but-mean-reverting rather than fragile. Bottom line: harvest the VRP through defined-risk structures in the 30-45 DTE window, and let the 770.00/772.00 bracket define your wings.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
770.67
771.59
-0.12%
772
770
760
-$2.20B
Short gamma
QQQ
718.64
718.73
-0.01%
720
700
705
$784.10M
Short gamma
IWM
295.85
295.96
-0.04%
300
295
290
-$3.00B
Short gamma
VIX
14.02
14.02
+0.02%
20
14
19.50
$24.73M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.36
8.06
+1.30
1.56
2.62
1.25
QQQ
13.58
12.86
+0.72
2.03
1.39
0.99
IWM
13.35
12.16
+1.19
1.49
2.43
1.18
VIX
115.03
78.49
+36.54
-144.37
0.38
0.23
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
14.02
-2.09%
VVIX
82.24
-4.65%
SPX
7,721.93
-0.33%
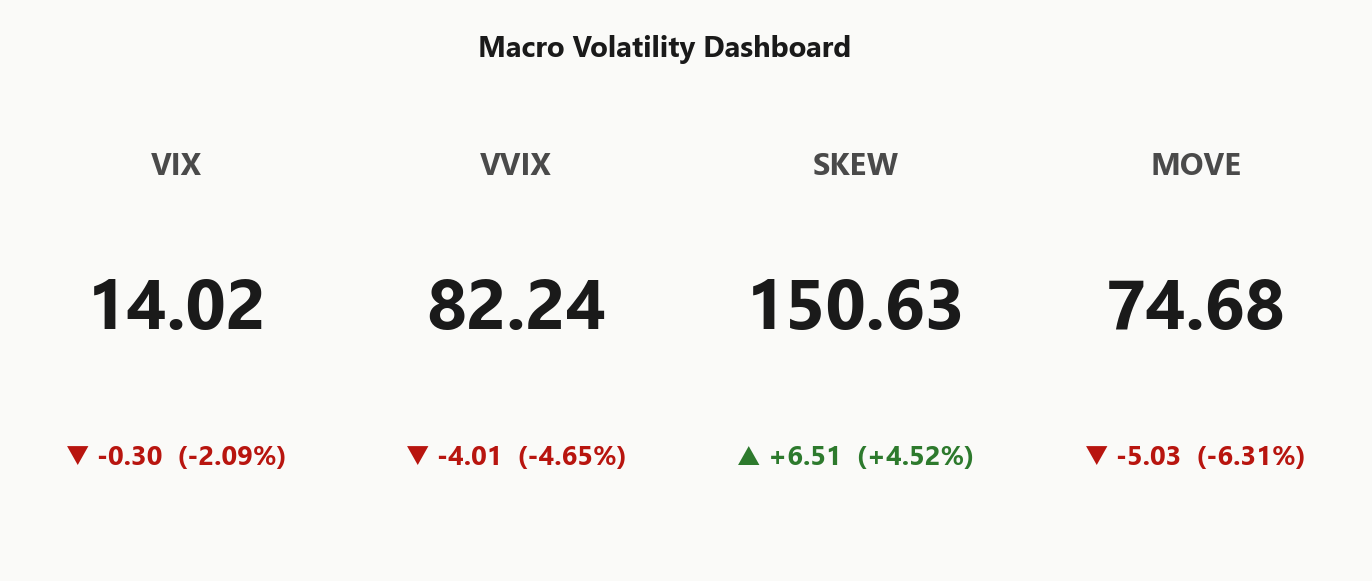
SKEW index
150.63
+4.52%
MOVE (bond vol)
74.68
-6.31%
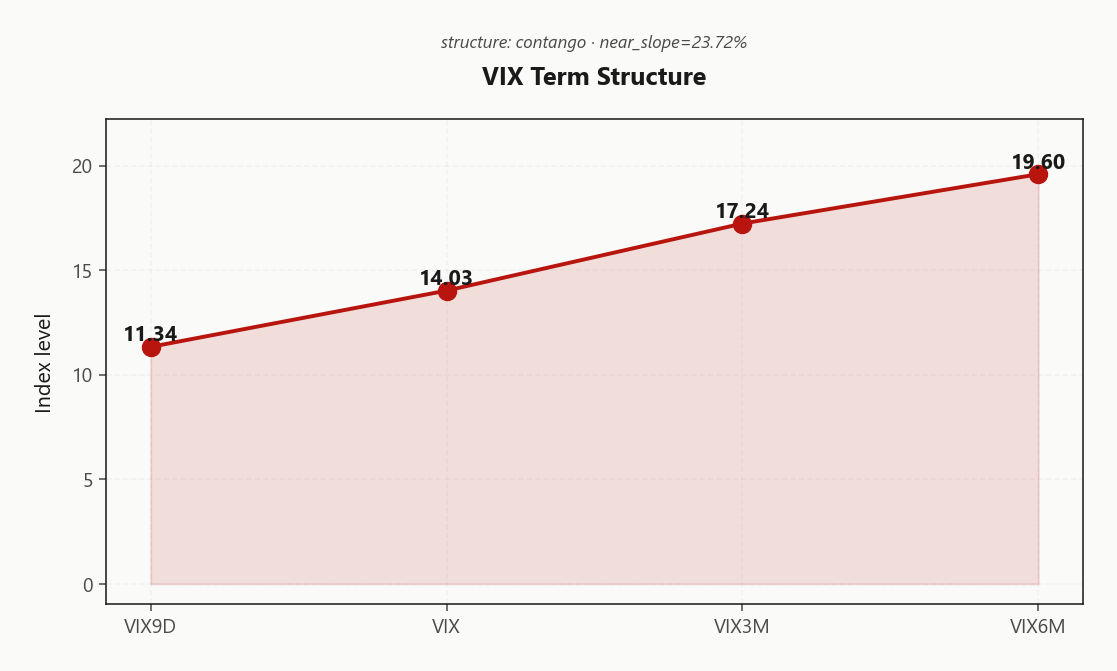
VIX term (9d/30d/3m/6m)
11.34 / 14.03 / 17.24 / 19.60
Steep contango
VVIX / VIX
5.87
Low
Regime
Low / Carry
Regime Assessment
Regime print reads Low / Carry with VIX anchored at 14.02 and a half-life measured in 30 sessions - this is a sticky state, not a fleeting one. Signal color trips Green, forward vol geometry sits in Steep Contango, and VVIX at 82.24 confirms no jump premium is being paid. Carry is the trade, and the tape is telling you to size it.
The asymmetry sits underneath the calm. To-panic probability across the next five sessions prints 0.05 - low, but the tail is not zero, and with SPY already parked below the flip at 771.59 the mechanical accelerant is loaded. To-low continuation over ten sessions runs 0.45: the modal path is more of the same grind.
Harvest the VRP through the 30-45 window, but write the tail hedge ticket now - steep put skew and a low VVIX mean OTM ratio spreads are cheap insurance you buy before you need them, not after.
What it means for your trading
Regime is Low / Carry with a 30-session half-life - carry is confirmed but the transition asymmetry runs downside, so pre-position the tail hedge while VVIX at 82.24 keeps it cheap.
Trading readVIX and VVIX are dropping in tandem while SKEW ticks up and MOVE collapses - this is a rare four-way divergence where equity vol relaxes but tail insurance gets bid. Read: professionals are cheaply loading tail hedges into calm.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve is Contango from front to back, with VIX9D at 11.34 printing well beneath spot VIX at 14.03 - the near-term tape is priced for calm, and the front-end slope at 23.72%% is the fattest roll-down we get in this complex. That's structural carry, and the derived regime label of Steep Contango confirms it.
Further out the curve, VIX3M at 17.24 and VIX6M at 19.60 bake in a modest event-vol term premium - the market is pricing something on the mid-curve, not the immediate window. Forward vol from thirty to sixty days sits at 18.6388290941, giving sellers a defensible entry that isn't front-running an obvious catalyst.
Trade the curve, not the front tick. Size the harvest in the thirty-to-sixty DTE belly where the roll-down is richest and vanna risk is manageable - not the zero-to-nine DTE window where any VIX pop repriced you before the roll pays.
What it means for your trading
Contango is Steep Contango with front slope 23.72%% - the carry trade is on, but only for desks willing to own front-end gamma and only if sized in the belly, not the front tick.
Trading readSteep contango from VIX9D through VIX6M is the strongest vol-carry setup we've seen this week - sellers of front-month vol are being paid a fat roll-down, provided nothing breaks the flip and forces a re-pricing.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied at 9.36% is trading above realized on the 8.06 window, and the resulting VRP of 1.3% vol points is doing exactly what a carry regime asks of it - paying sellers to lease the tape. The spread is not heroic, but it is positive and persistent, and with the index complex printing Aligned across SPY, QQQ and IWM, the premium is broad-based rather than a single-name artefact.
The more instructive read sits one window out: HV60 at 12.56 is elevated versus the 8.06 print, so recent tape has cooled off a noisier stretch and mean-reversion in realized is actively compressing the denominator of the VRP calculation. That is the sellers' tailwind - options are being marked to a memory of vol that spot has stopped delivering.
Section signal reads Vrp Active. Harvest the spread through defined-risk structures at index level; do not confuse a working VRP with a free one.
What it means for your trading
IV at 9.36% sits above HV20 at 8.06 with VRP of 1.3% vol points - the sellers' edge is live, and HV60 at 12.56 confirms realized is mean-reverting lower, widening the harvest.
Skew Convexity
Quarter-delta puts print 7.16% against calls at 5.6%, a skew reading of 1.56% vol points that is ordered rather than spiking. The put wing carries the classic risk-off insurance premium, but the smile ratio at 1.28% confirms convexity without tail panic - desks are hedging, not scrambling.
ATM sits at 6.64%, meaningfully below the downside wing and with no upside chase repricing the calls. That geometry is a paid-for downside cushion against a flat top - the market is buying protection on principle, not on catalyst. With spot fractionally under the flip at 771.59 and the complex Aligned in negative gamma, the steepness is structural, not signal.
Trade the steepness, do not pay it: put spreads finance the fat wing rather than lease it outright, and defined-risk condor wings outside the 770.00/772.00 bracket monetize the convexity premium without owning the vanna risk.
What it means for your trading
Skew at 1.56% vol points and smile ratio 1.28% describe ordered downside insurance demand, not tail panic - sell the wing through spreads, do not buy it naked.
Vol-of-Vol Structure
VVIX prints 82.24 against VIX at 14.02, putting the ratio at 5.87 - squarely in the Low band. Translation: the market is not paying up for a binary outcome, and the jump premium that would normally accompany a short-gamma tape is conspicuously absent.
A ratio sitting in the normal band means no bimodal pricing, no forced tail-hedge crowding, and no cohort of dealers scrambling to reload convexity into the close. That gives sizing guidance of Standard Size - vol sellers can lean in without the half-size discipline that a stressed vol-of-vol reading would demand.
Pair this with steep contango and a rich VRP and the read is clean: harvest the premium at standard size, keep wings defined outside the 770.00/772.00 pair, and treat any VVIX tick higher - not the VIX print itself - as the first signal that the carry regime is losing its footing.
What it means for your trading
VVIX at 82.24 and a ratio of 5.87 confirm a Low vol-of-vol regime - sellers get Standard Size without needing tail-hedge crowding discipline.
Dispersion Spread
Index ATM IV at 9.36% is trading at a stark discount to the mag-7 single-name complex - this is not a market lacking movement, it is a market where correlation is doing the suppressing. The top GEX movers underline it: $2.92B at NVDA, $1.79B at META, and $1.63B at MSFT are all repricing hard while SPY's aggregate vol prints comfortably below what the components imply.
The preferred expression is clean: sell the index premium, own single-name convexity via calls. Iron condors on SPY inside the 770.00/772.00 bracket harvest the correlation discount, while long-vol overlays on the dispersion leaders lease optionality where it is genuinely mispriced. The trap to avoid: leaning on index puts as a hedge against a mag-7 idiosyncratic drawdown - that hedge underperforms by construction when one name tanks and the rest hold.
Regime is Aligned across the complex, which reinforces the trade - index sellers with stock-specific long-vol overlays are the correlation-weighted winners here.
What it means for your trading
Sell SPY vol at 9.36%, own single-name upside where dispersion is repricing - index hedges will not save you in an idiosyncratic mag-7 drawdown.
Liquidity & Microstructure
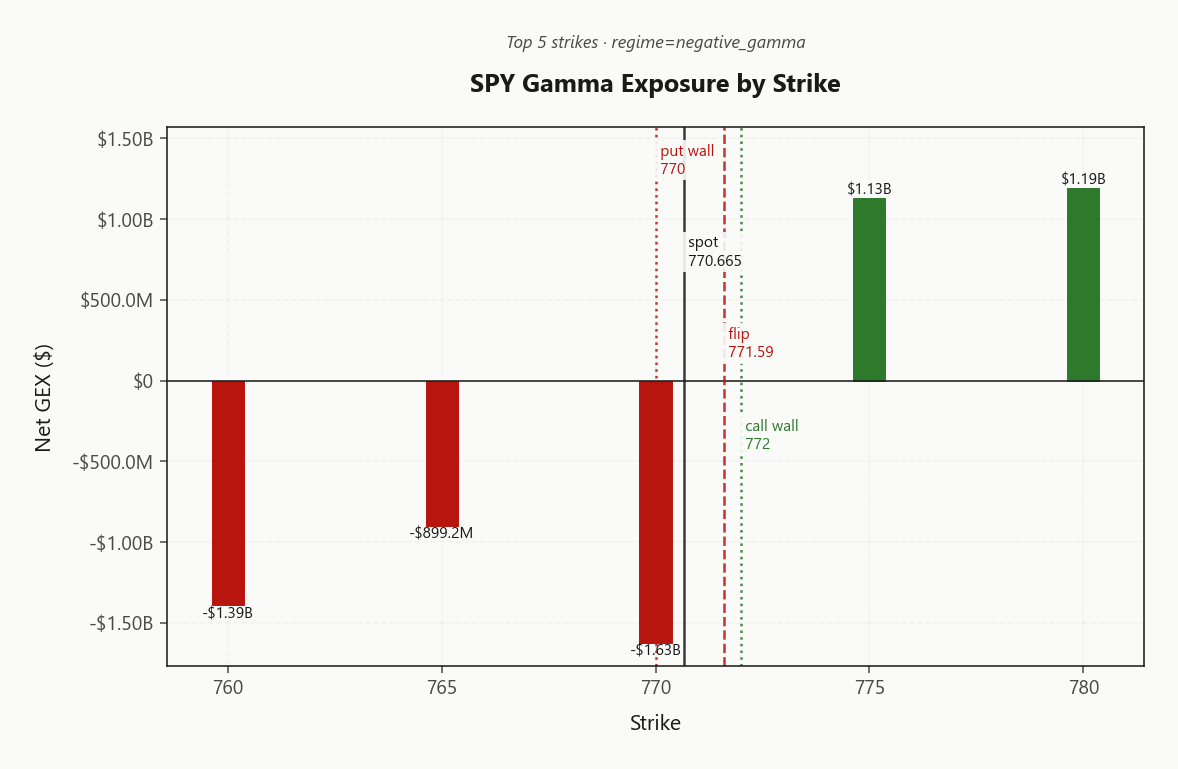
The long-dated book anchors on the massive open-interest stack at 525, but that's tomorrow's problem - today's battle is at 770.00, where net GEX prints -$1.63B. That's the strike dealers either defend or capitulate on, and spot is sitting right in the crosshairs. The gamma flip at 771.59 is the line: reclaim it and dealer flow rotates from destabilizing to supportive; lose it and the negative-gamma feedback loop tightens.
Bracket the tape with the 770.00 put wall and the 772.00 call wall - the first is the acceleration trigger, the second caps any upside chase. Inside that pair, 0DTE gamma share at 83% is elevated enough to compress the intraday range into a late-session pin, most likely at the put wall or the flip itself.
What it means for your trading
Spot is pressed against the 770.00 pivot with the flip at 771.59 overhead - a reclaim flips dealer hedging supportive, a break accelerates lower, and the intraday tape pins between the walls in the meantime.
Trading readThe gamma-by-strike stack shows dealers short right at spot with a supportive shelf above at 772.00 - the tape is coiled inside the wall pair, so fade excursions to the walls rather than chase breakouts unless the flip is decisively reclaimed.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Net VEX prints -$183.71B - a meaningful downside accelerant if the vol complex catches a bid. Any tick higher in 14.02 forces dealers to sell delta into weakness via the vanna channel, and with spot fractionally below the flip at 771.59, that reflexive hedge lands on an already-fragile tape.
Charm sits at -$1.2M, a modest but persistent bleed that pushes dealers to sell into strength as the session decays. The pivot registers at 770 - a Put Wall anchor rather than a gamma inflection - so flow direction hinges on defense of that level. Current read is Neutral: no directional tailwind, just mechanics.
Trade the tell, not the tape. Watch 14.02 ticks as the leading indicator for SPY hedging flow - vol-up mechanically prints dealer supply, and the 770.00/772.00 bracket defines where that supply gets absorbed or accelerates.
What it means for your trading
Vanna is loaded as a downside accelerant with charm bleeding dealers into supply through the session; the 770 pivot is the mechanical fulcrum and VIX ticks are the leading indicator for hedging flow.
Cross-Asset Confirmation
MOVE at 74.68 is bleeding lower on the session - rates vol is easing hard even as equity dealers sit short gamma. That's the tell: credit stress is not spilling in from bonds, so the fragility you feel in the SPX tape is a microstructure story, not a macro one. When rates vol relaxes into an equity gamma pocket, the historical read is mean-reversion, not cascade.
The equity complex is aligned rather than fracturing: QQQ at 718.64 and IWM at 295.85 both sit in negative gamma alongside SPY, with cross-asset regime tagged Aligned. No index is carrying the others - the short-gamma posture is uniform, which reduces the odds of a dispersion-driven unwind and raises the odds that any break in one drags the pack rather than getting absorbed.
Sentiment is the contrarian kicker. Fear & Greed prints 42 (Fear) against a compressed VIX at 14.02 and steep contango out to 17.24 - the classic coil for a grind-higher squeeze into the next catalyst if news cooperates.
What it means for your trading
Rates vol easing at 74.68 while equity gamma stays short is a supportive cross-asset read - the fragility is local, not systemic. Fear at 42 with a low VIX is the setup for a squeeze, not a slide.
Scenario EV
The scoring stack lands on Iron Condor at 40, and the composition tells you why: VVIX prints Low so jump premium isn't being paid, yet the 1.56% skew keeps the wings convex - naked strangles get you the theta but leave you naked into any vanna impulse. Defined wings are mandatory here, not stylistic, and the model reflects that in the spread between the condor score and the runner-up.
The 30-45 DTE window is the operative call. Anything inside that band sidesteps the 83% 0DTE gamma share dominating the intraday tape while still parking you in the fattest theta band before charm bleeds accelerate. Wings sit outside the 770.00/772.00 bracket - that pair is the dealer battle line, not a coincidence to bracket around.
Secondary trade for the directional desks: put spread at 27 - a way to lease the steep put wing rather than pay it, and the cleaner expression if you actually want short beta rather than pure VRP capture.
What it means for your trading
Model favors Iron Condor at 30-45 DTE because low VVIX with steep skew and short-gamma dealer positioning rewards defined wings over open-ended premium selling. Put spread is the secondary expression for directional bears leasing rather than paying the put wing.
Actionable Summary
Bottom line: sell Iron Condor structures in the 30-45 DTE window, wings parked outside the 770.00/772.00 pair. Regime reads Low / Carry with VVIX at 82.24 - no jump premium being paid, so size standard rather than half. VRP at 1.3% confirms options are rich to realized, and the steep contango from 11.34 through 19.60 gives the roll-down its teeth.
Watch the charm pivot at 770: a reclaim flips dealer flow supportive, a loss of 770.00 triggers vanna-driven accelerant selling into short-gamma air. Avoid naked 0DTE strangles inside the wall pair - with 83% of gamma stacked at expiry, any VIX tick runs you over. Hedge the steep put wing cheaply via OTM ratio spreads; second trade is single-name long vol overlays on the mag-7 dispersion leaders where index-suppressed correlation isn't doing the work.
What it means for your trading
Carry regime with a fragile microstructure: harvest the 1.3% VRP through defined-risk Iron Condors at 30-45 DTE, and let the 770 pivot dictate whether you press or trim.
A hot jobs report pushing 2-year yields to multi-quarter highs is the day's macro axis - it tightens Fed expectations, threatens the vol-carry trade if front-end rates keep climbing, and explains why MOVE dropped even as duration re-priced.
Two consecutive weeks of equity fund outflows amid Iran headlines corroborates the Fear reading - positioning is defensive despite the compressed VIX, which is a coil for either a squeeze higher or an accelerated break if news deteriorates.
Diesel at record highs and Ukraine strikes on Russian refineries reintroduce a stagflationary inflation channel - this is the kind of slow-drip macro that broadens the vol premium at longer dates without moving the front-end.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.02 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 771.59 against a spot of 770.67. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.36% with a volatility risk premium of 1.3%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.02. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime